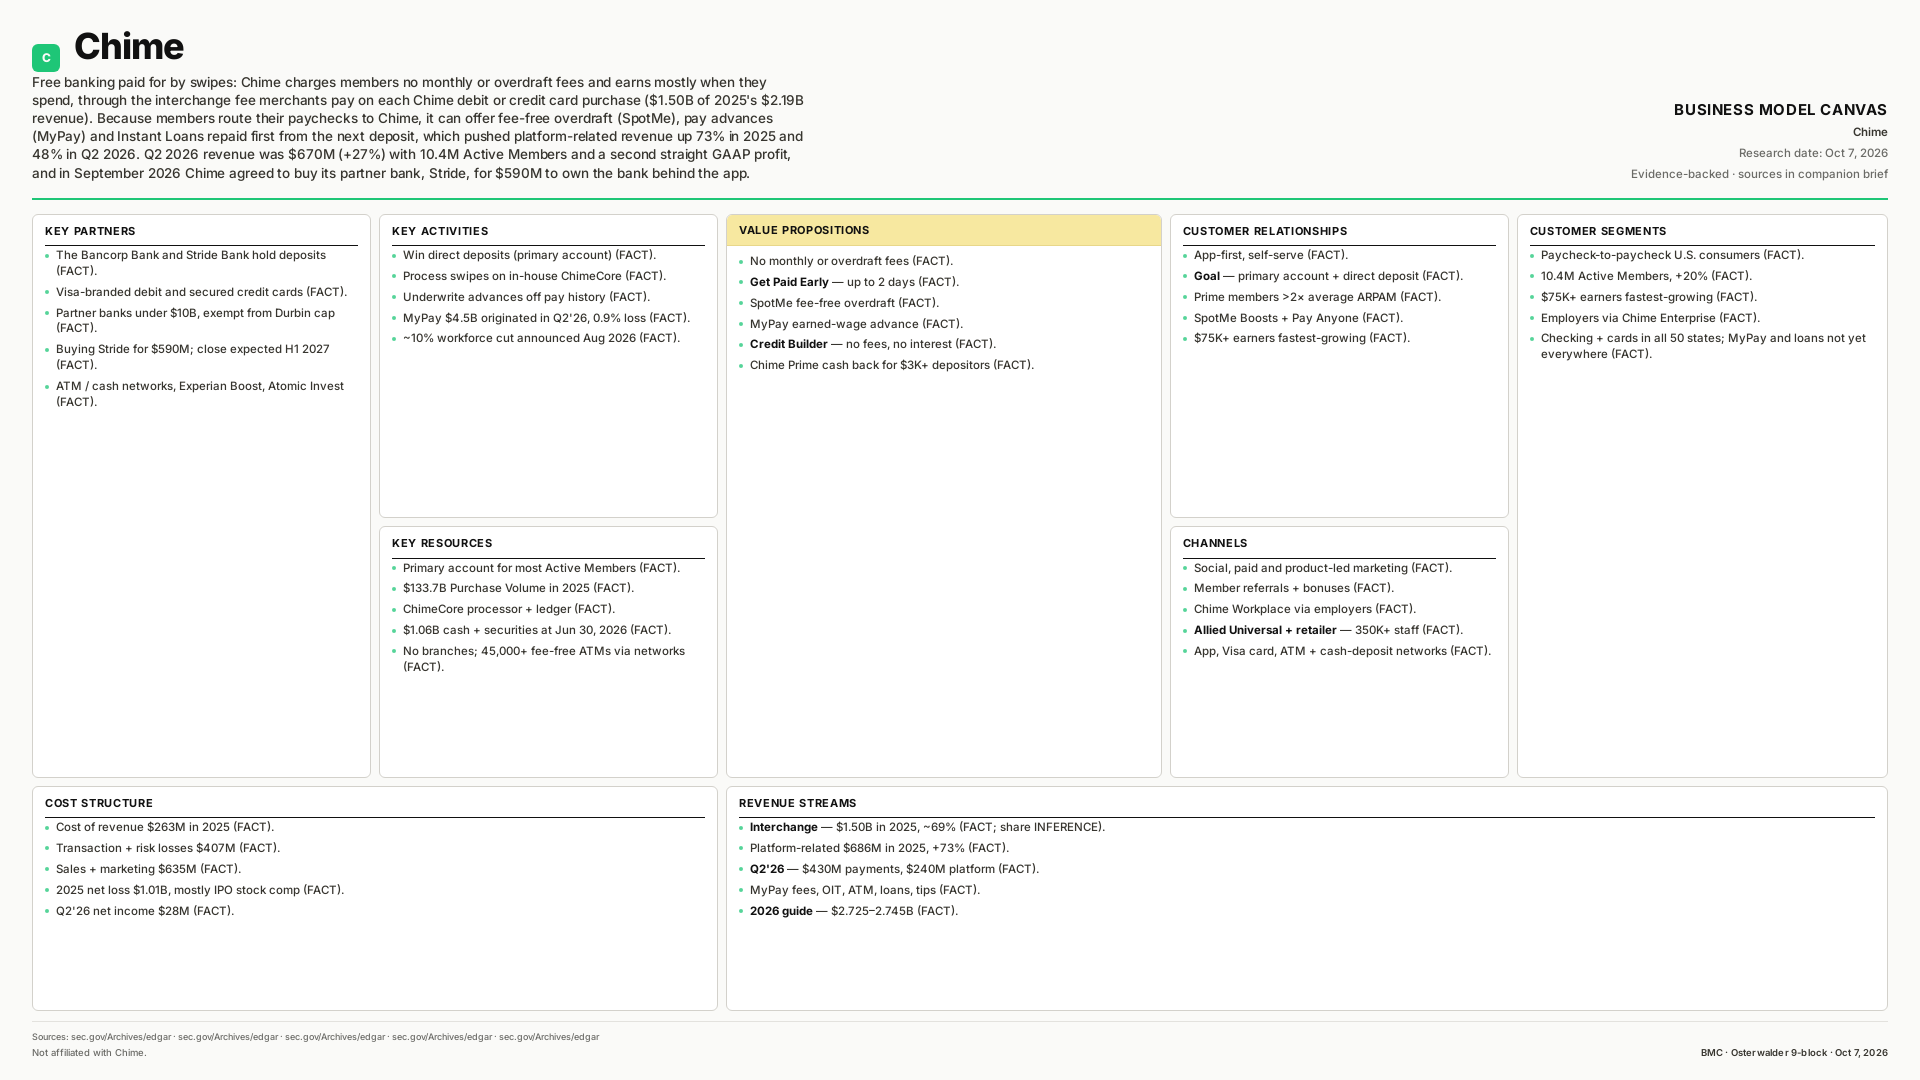
Free banking paid for by swipes: Chime charges members no monthly or overdraft fees and earns mostly when they spend, through the interchange fee merchants pay on each Chime debit or credit card purchase ($1.50B of 2025's $2.19B revenue). Because members route their paychecks to Chime, it can offer fee-free overdraft (SpotMe), pay advances (MyPay) and Instant Loans repaid first from the next deposit, which pushed platform-related revenue up 73% in 2025 and 48% in Q2 2026. Q2 2026 revenue was $670M (+27%) with 10.4M Active Members and a second straight GAAP profit, and in September 2026 Chime agreed to buy its partner bank, Stride, for $590M to own the bank behind the app.
Click any of the 9 blocks below for a plain-language story of how that part of the model works for Chime — and how it connects to the others.
Static handout preview — use Downloads in the top bar for PDF, PNG, poster HTML, or the research brief. The interactive canvas above is the primary experience.