Four-party network (no lending)Volume-based assessments less rebatesValue-added services attachStablecoins + agentic commerce
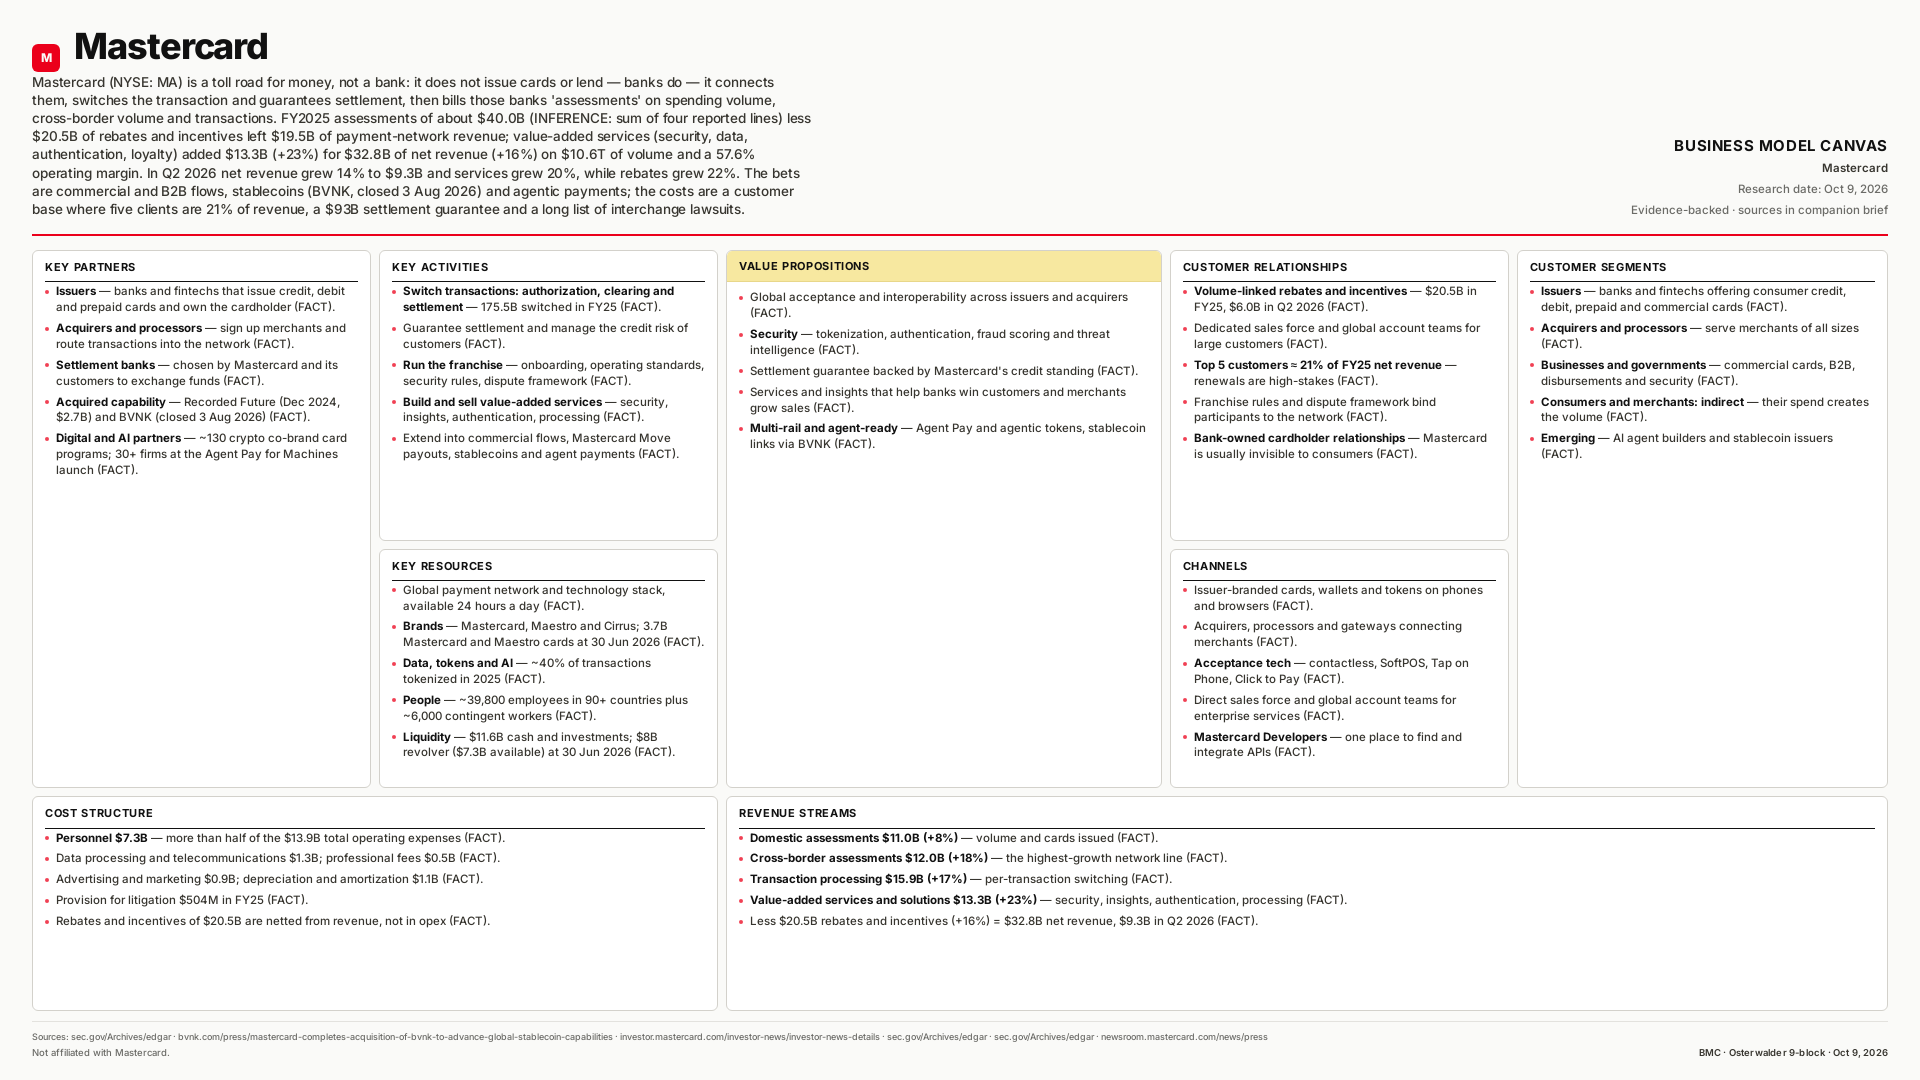
Mastercard (NYSE: MA) is a toll road for money, not a bank: it does not issue cards or lend — banks do — it connects them, switches the transaction and guarantees settlement, then bills those banks 'assessments' on spending volume, cross-border volume and transactions. FY2025 assessments of about $40.0B (INFERENCE: sum of four reported lines) less $20.5B of rebates and incentives left $19.5B of payment-network revenue; value-added services (security, data, authentication, loyalty) added $13.3B (+23%) for $32.8B of net revenue (+16%) on $10.6T of volume and a 57.6% operating margin. In Q2 2026 net revenue grew 14% to $9.3B and services grew 20%, while rebates grew 22%. The bets are commercial and B2B flows, stablecoins (BVNK, closed 3 Aug 2026) and agentic payments; the costs are a customer base where five clients are 21% of revenue, a $93B settlement guarantee and a long list of interchange lawsuits.
Click any of the 9 blocks below for a plain-language story of how that part of the model works for Mastercard — and how it connects to the others.
Static handout preview — use Downloads in the top bar for PDF, PNG, poster HTML, or the research brief. The interactive canvas above is the primary experience.