Fintech infrastructure / Open-banking network · Oct 8, 2026
Usage-based API pricingFree to consumers, apps payNetwork data → credit + fraudBank data fees + 1033 reset
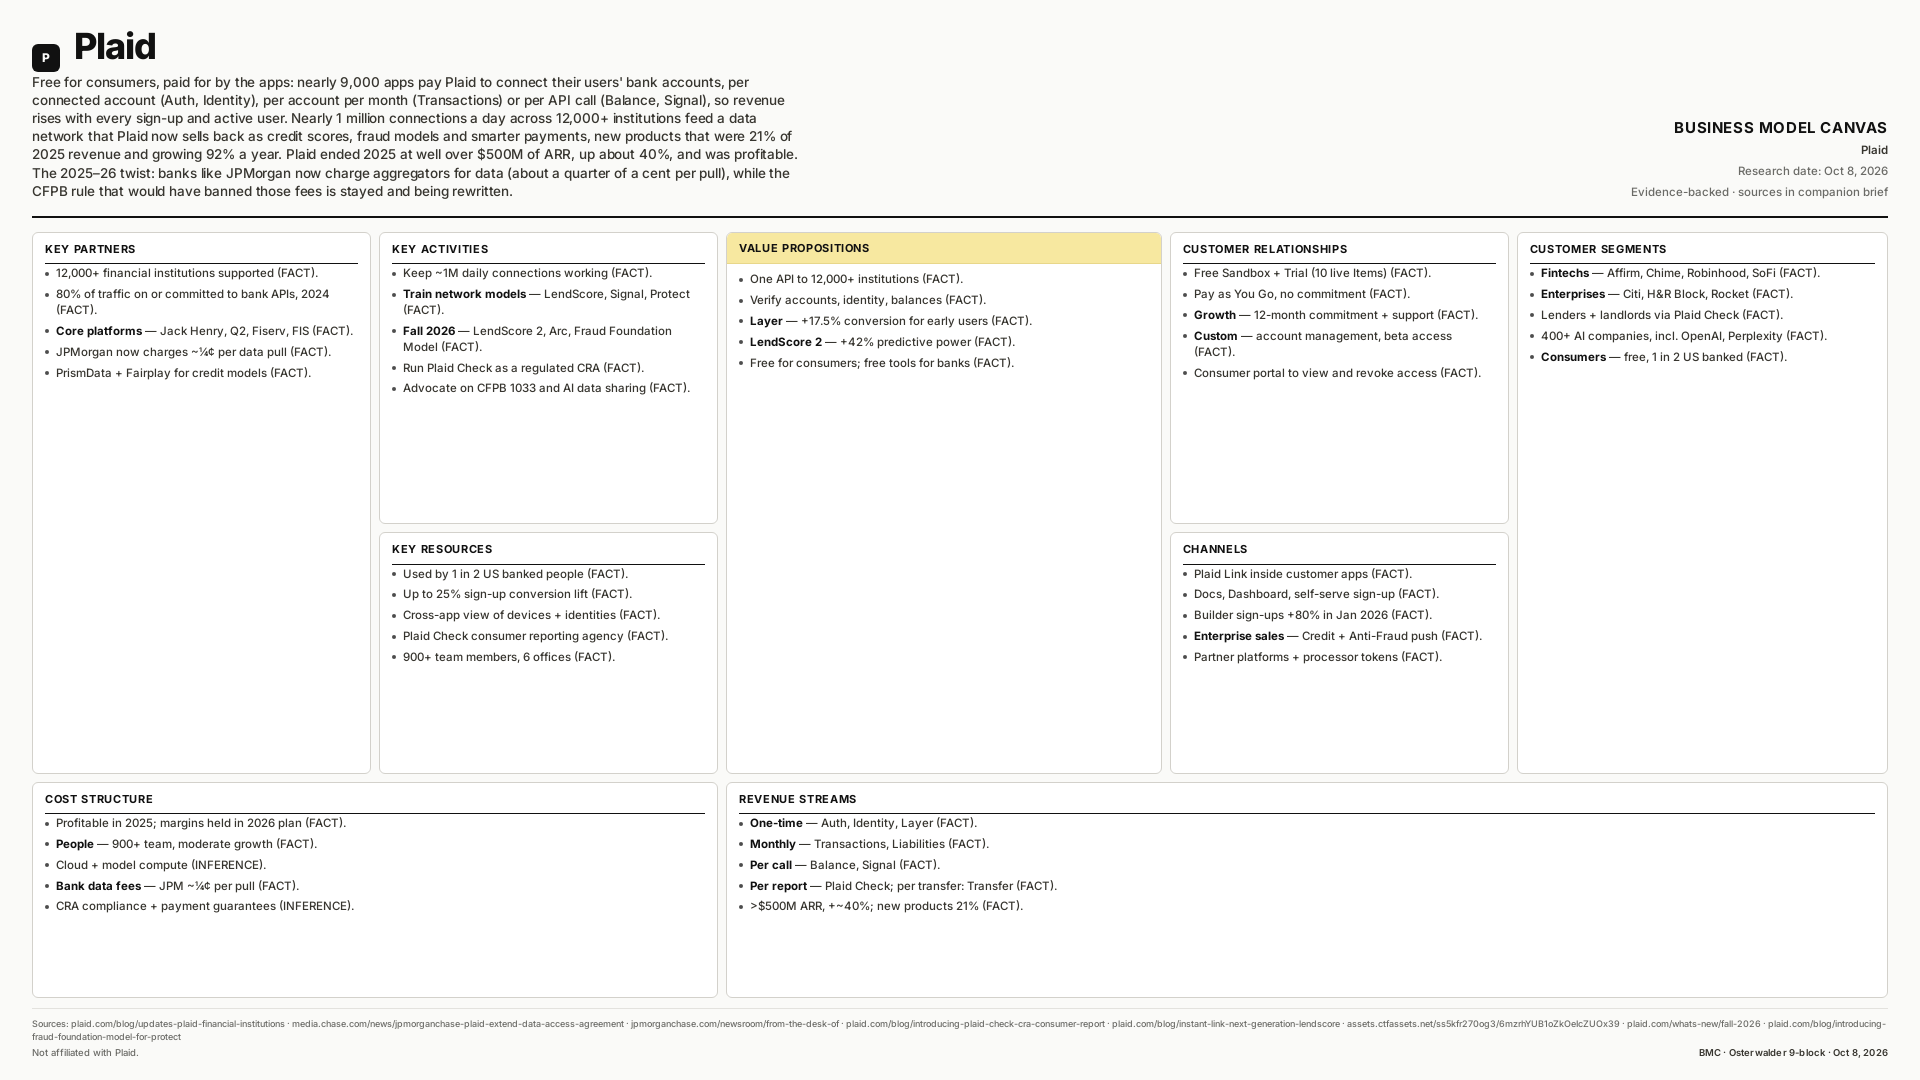
Free for consumers, paid for by the apps: nearly 9,000 apps pay Plaid to connect their users' bank accounts, per connected account (Auth, Identity), per account per month (Transactions) or per API call (Balance, Signal), so revenue rises with every sign-up and active user. Nearly 1 million connections a day across 12,000+ institutions feed a data network that Plaid now sells back as credit scores, fraud models and smarter payments, new products that were 21% of 2025 revenue and growing 92% a year. Plaid ended 2025 at well over $500M of ARR, up about 40%, and was profitable. The 2025–26 twist: banks like JPMorgan now charge aggregators for data (about a quarter of a cent per pull), while the CFPB rule that would have banned those fees is stayed and being rewritten.
Click any of the 9 blocks below for a plain-language story of how that part of the model works for Plaid — and how it connects to the others.
Static handout preview — use Downloads in the top bar for PDF, PNG, poster HTML, or the research brief. The interactive canvas above is the primary experience.