Hardware as loss leaderPer-location SaaS + paymentsAttach flywheel (modules + AI)Embedded finance (Capital, payroll)
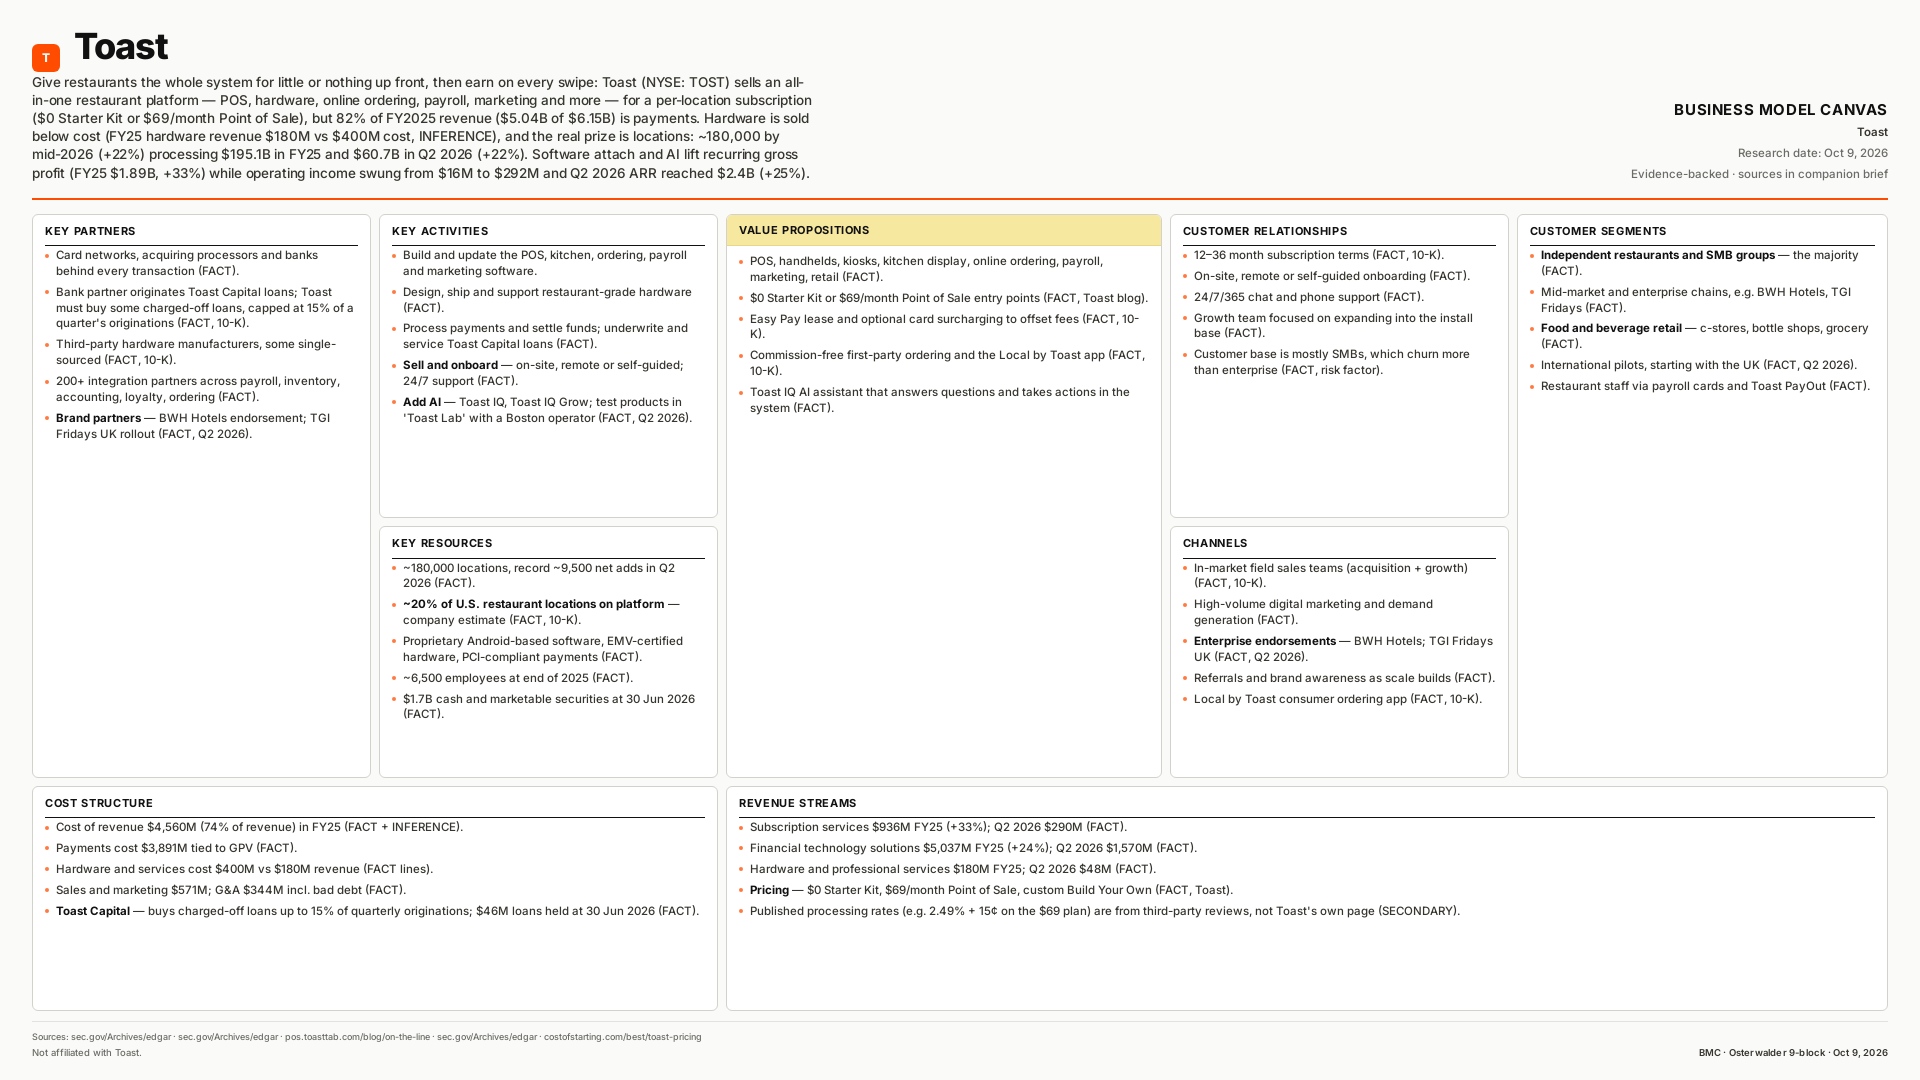
Give restaurants the whole system for little or nothing up front, then earn on every swipe: Toast (NYSE: TOST) sells an all-in-one restaurant platform — POS, hardware, online ordering, payroll, marketing and more — for a per-location subscription ($0 Starter Kit or $69/month Point of Sale), but 82% of FY2025 revenue ($5.04B of $6.15B) is payments. Hardware is sold below cost (FY25 hardware revenue $180M vs $400M cost, INFERENCE), and the real prize is locations: ~180,000 by mid-2026 (+22%) processing $195.1B in FY25 and $60.7B in Q2 2026 (+22%). Software attach and AI lift recurring gross profit (FY25 $1.89B, +33%) while operating income swung from $16M to $292M and Q2 2026 ARR reached $2.4B (+25%).
Click any of the 9 blocks below for a plain-language story of how that part of the model works for Toast — and how it connects to the others.
Static handout preview — use Downloads in the top bar for PDF, PNG, poster HTML, or the research brief. The interactive canvas above is the primary experience.