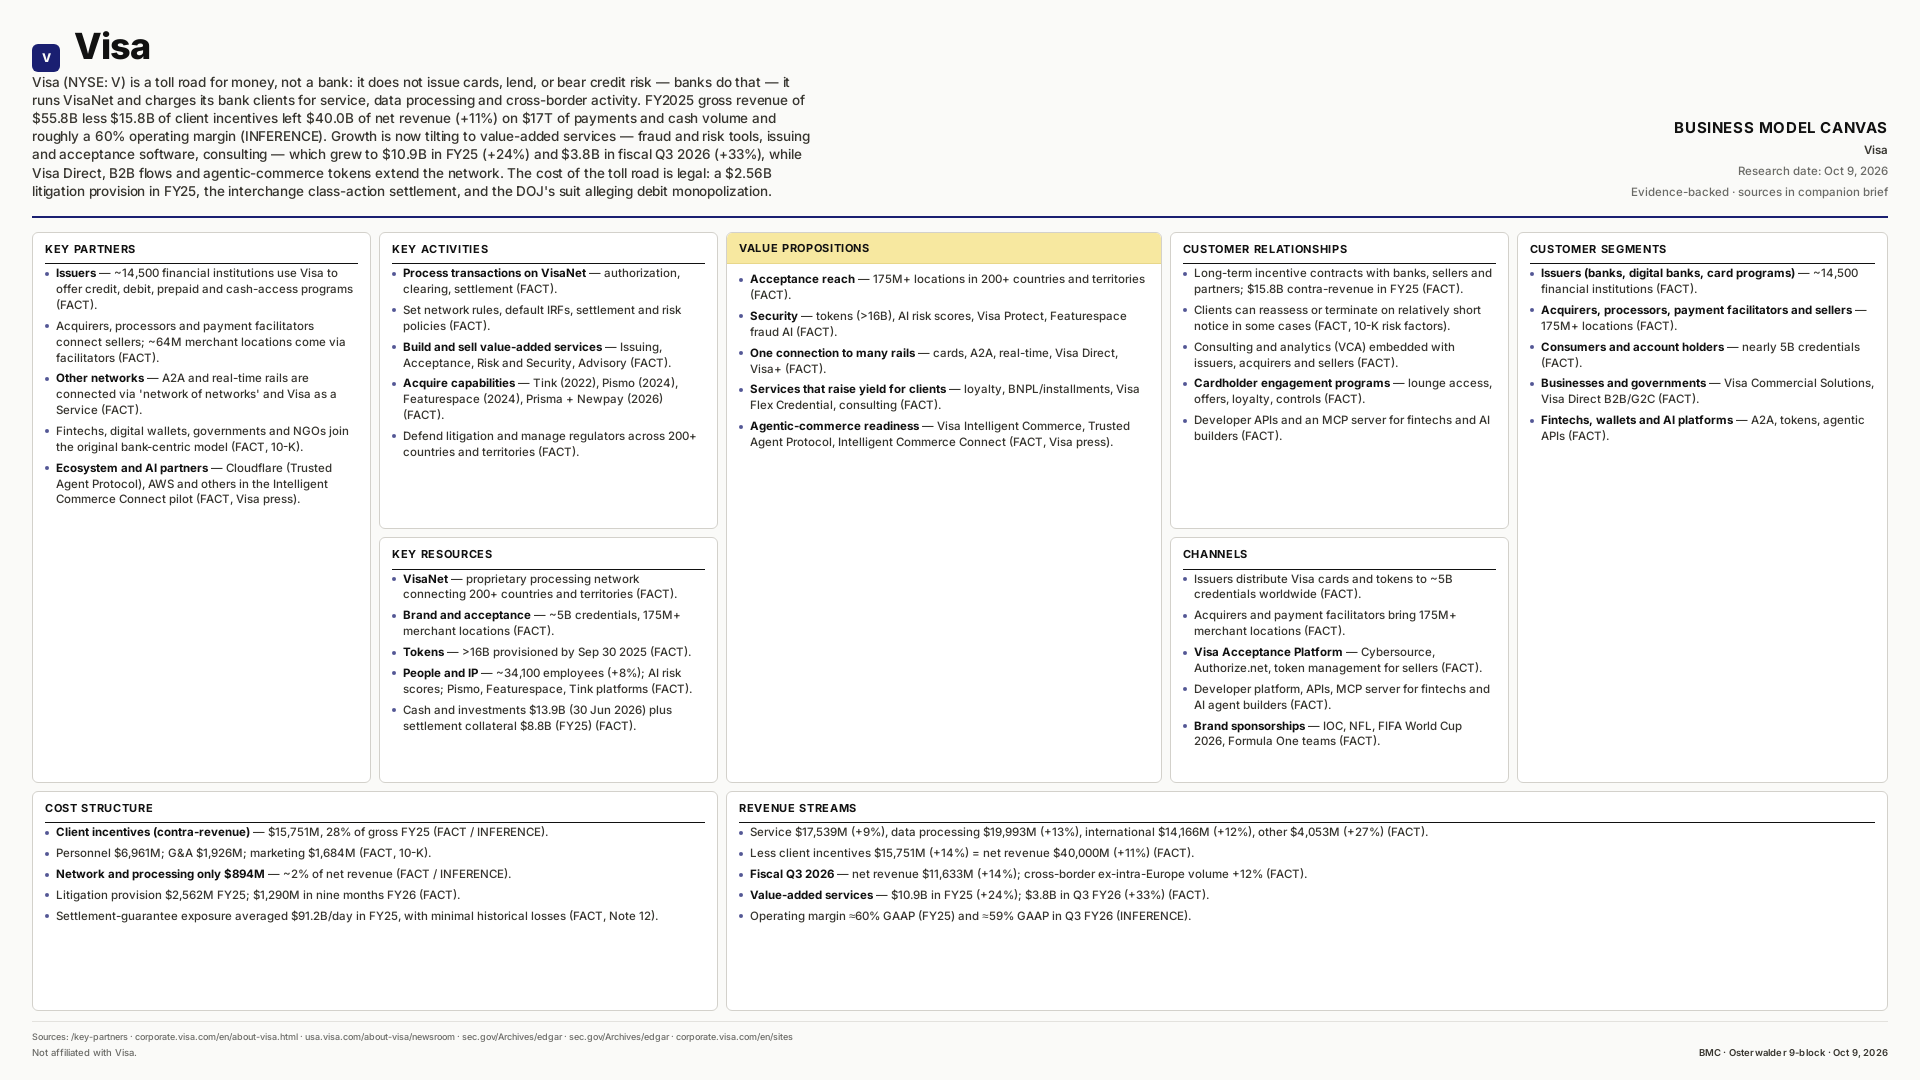
Visa (NYSE: V) is a toll road for money, not a bank: it does not issue cards, lend, or bear credit risk — banks do that — it runs VisaNet and charges its bank clients for service, data processing and cross-border activity. FY2025 gross revenue of $55.8B less $15.8B of client incentives left $40.0B of net revenue (+11%) on $17T of payments and cash volume and roughly a 60% operating margin (INFERENCE). Growth is now tilting to value-added services — fraud and risk tools, issuing and acceptance software, consulting — which grew to $10.9B in FY25 (+24%) and $3.8B in fiscal Q3 2026 (+33%), while Visa Direct, B2B flows and agentic-commerce tokens extend the network. The cost of the toll road is legal: a $2.56B litigation provision in FY25, the interchange class-action settlement, and the DOJ's suit alleging debit monopolization.
Click any of the 9 blocks below for a plain-language story of how that part of the model works for Visa — and how it connects to the others.
Static handout preview — use Downloads in the top bar for PDF, PNG, poster HTML, or the research brief. The interactive canvas above is the primary experience.