BMC Atlas · Evidence-backed business models
Business Model Canvas Gallery
A growing gallery of interactive, evidence-backed Business Model Canvases — click any block for plain-language detail, connections, and sources.
118 companies · interactive canvases
 8:31
How to use this gallery▶ Watch the walkthrough
Explore the Money Map → how these companies make money, side by side
Most requested
No canvas yet
We haven’t published yet. Request it — the most-requested companies are added first.
See the queue · what’s being built next

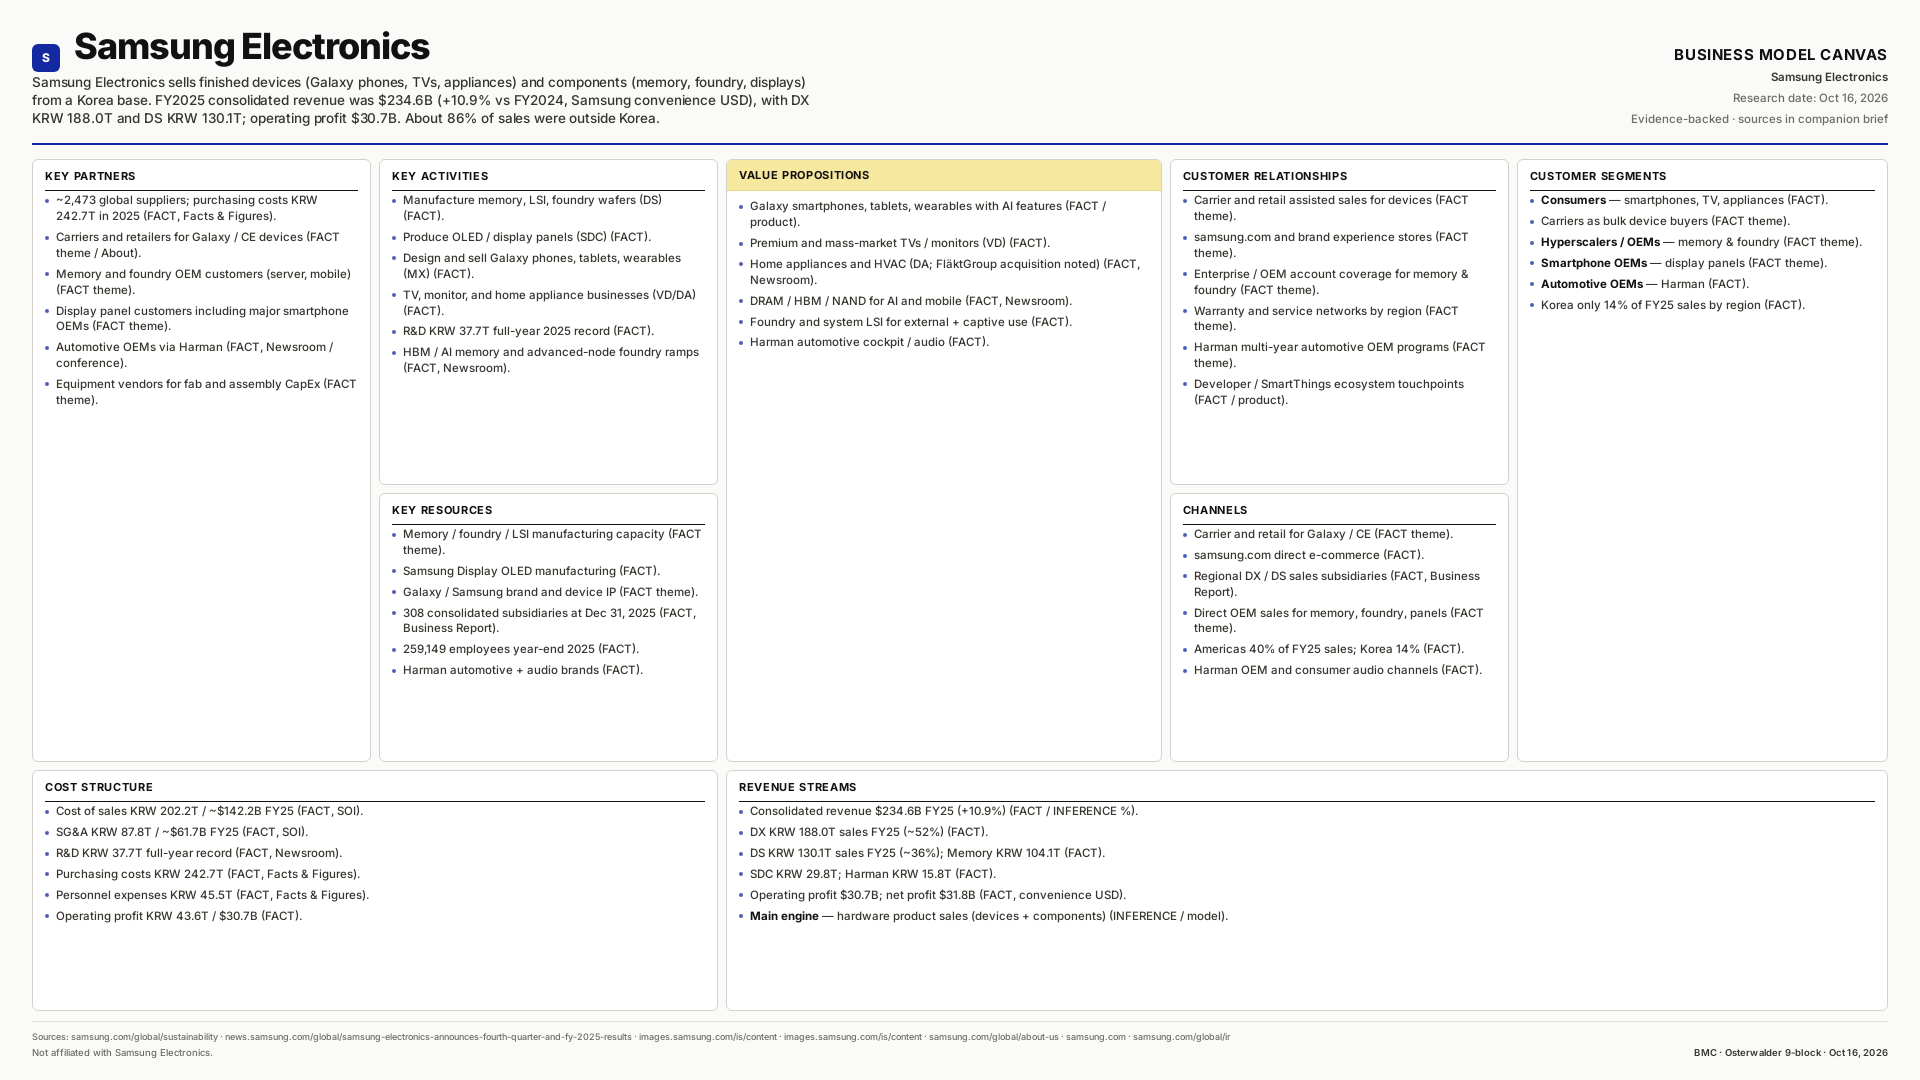

Samsung Electronics
Devices + semiconductors: DX KRW 188.0T and DS KRW 130.1T; consolidated revenue $234.6B FY2025 (+10.9%, Samsung convenience USD).
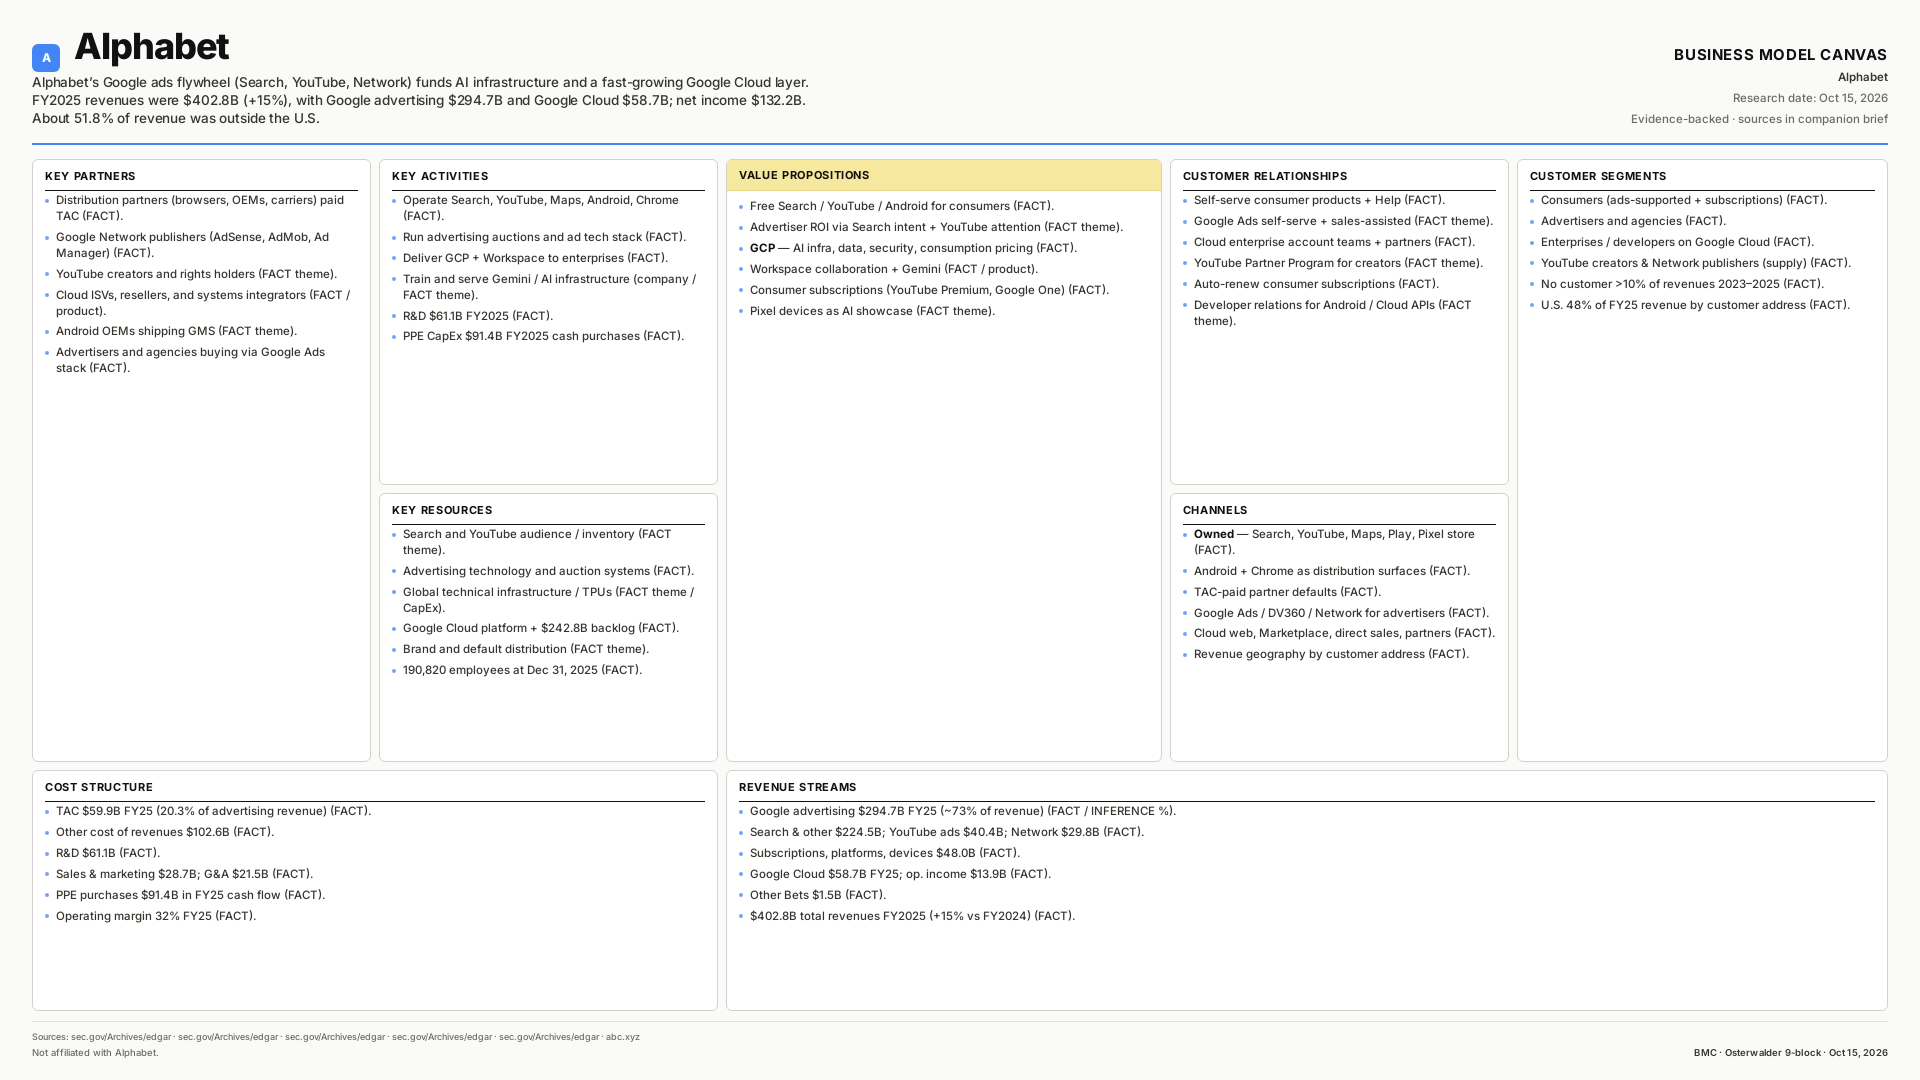

Alphabet
Ads cash engine funding Cloud + AI: Search/YouTube/Network ads $294.7B; Google Cloud $58.7B; total revenue $402.8B FY2025 (+15%).

Apple
Hardware + Services flywheel: iPhone-led devices plus App Store, Care, cloud & content; $416.2B net sales FY2025 (+6.4%); Products $307B / Services $109B.

OfferUp
U.S. mobile local marketplace: free meetups with $0 commission; monetizes via promoted listings, Premium/Promote Plus, business plans & ads; ~$150M estimated sales FY2023 (company to AIM); shipping take-rate retired 2025.

Craigslist
Ultra-lean local classifieds: most posts free; paid fees on jobs ($10–75), services, housing & vehicles in selected U.S./CA markets; AIM estimates ~$302M revenue FY2024 (down from ~$1.0B peak in 2018).

Depop
Gen-Z C2C fashion resale: zero seller fees in UK/US/AUS, buyers pay a Marketplace fee (up to 5% + £/$1); FY2025 revenue £140.8M (+39%) on $1.07B GMS; eBay-owned since Jul 2026 (~$1.4B).

Vinted
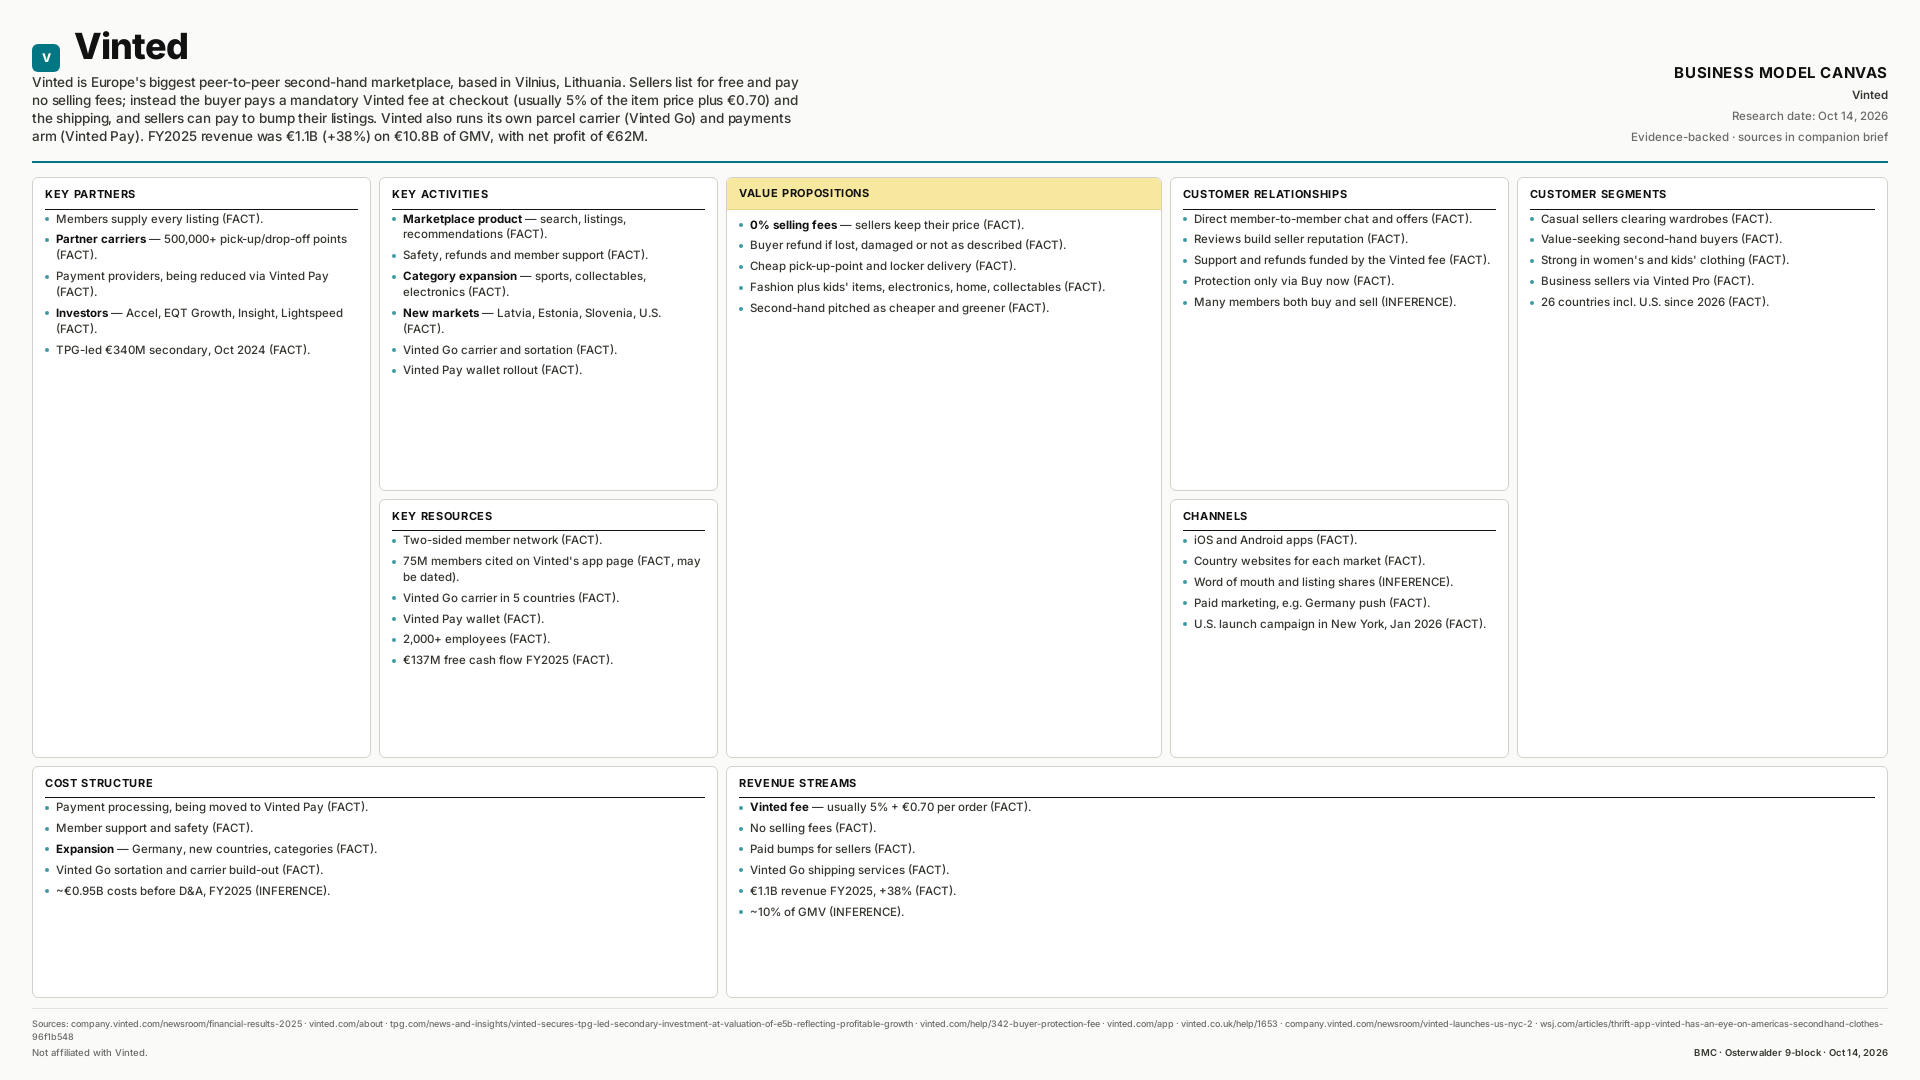
Europe's biggest C2C second-hand marketplace: zero seller fees, buyers pay a Vinted fee (usually 5% + €0.70) plus shipping; FY2025 revenue €1.1B (+38%) on €10.8B GMV, net profit €62M.

Poshmark
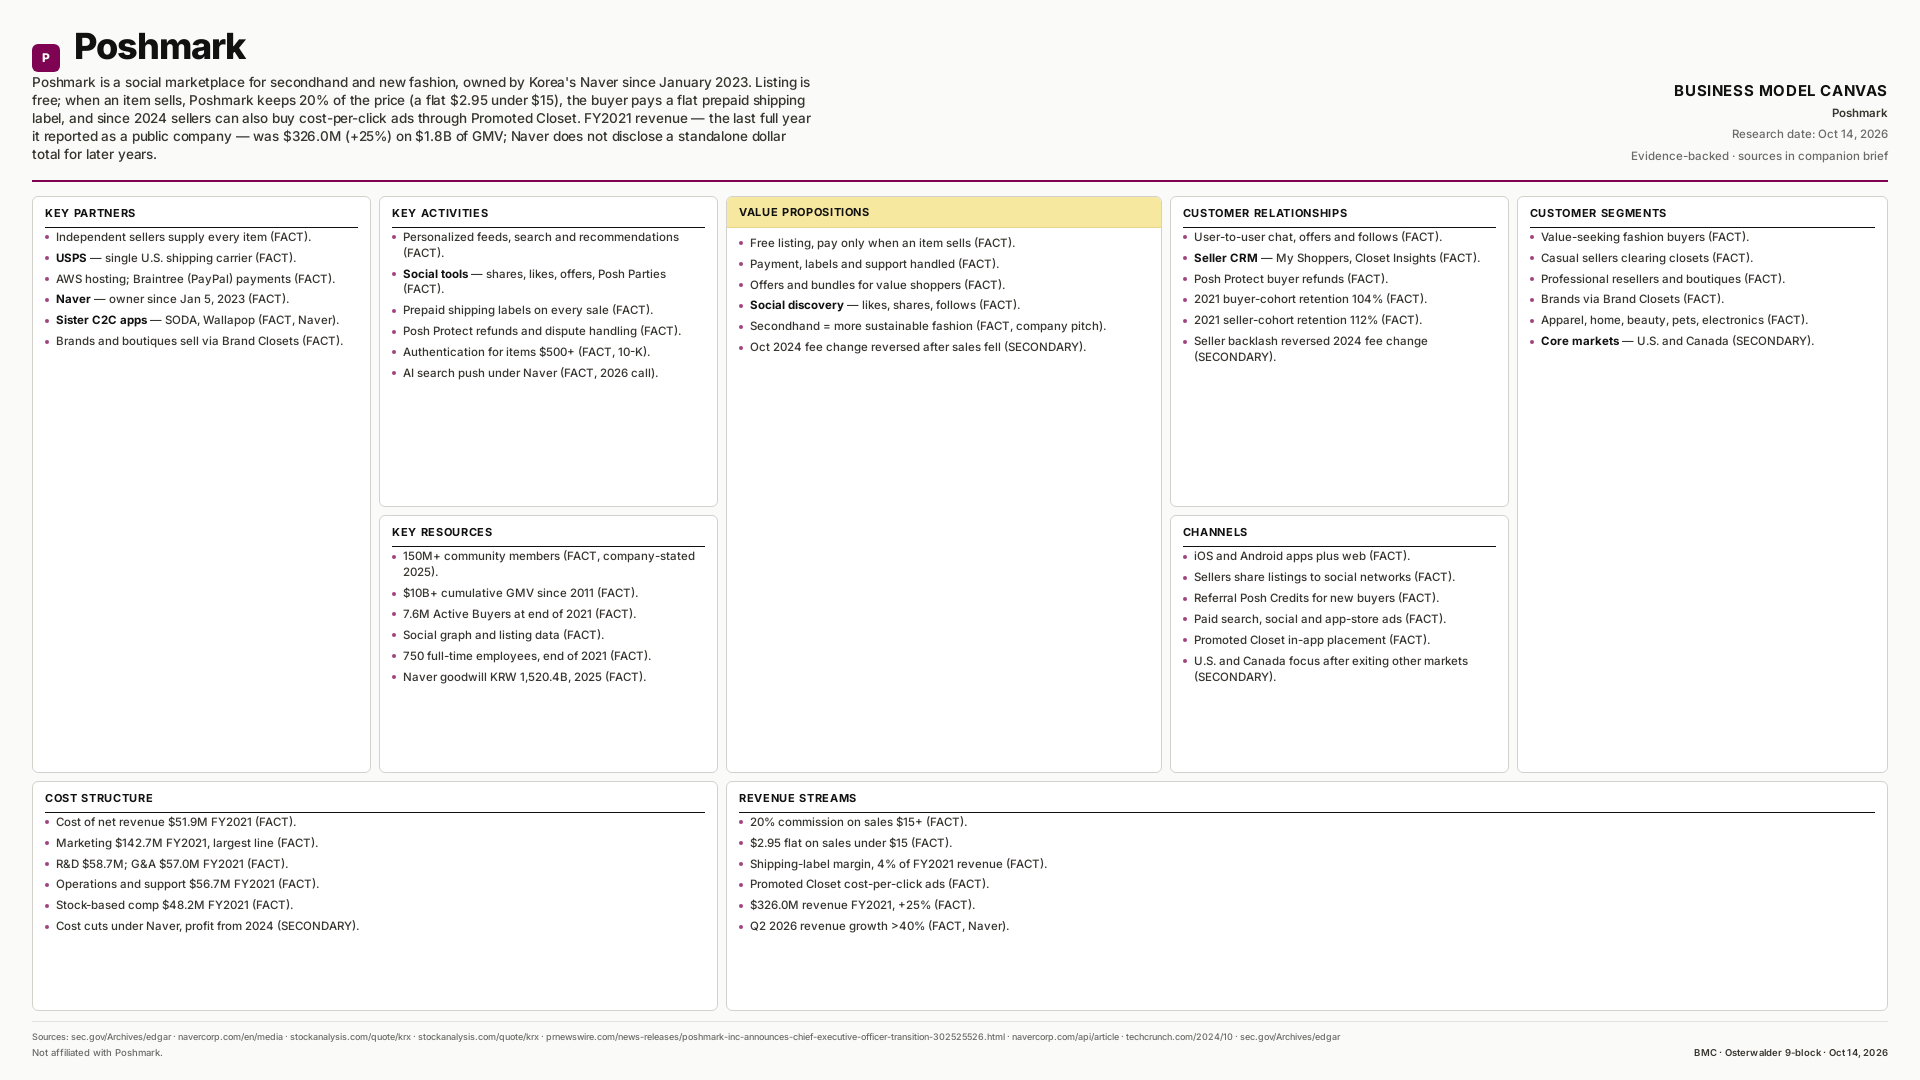
Naver-owned social fashion resale marketplace keeping 20% of each sale ($2.95 under $15) plus shipping-label margin and Promoted Closet ads; FY2021 revenue $326.0M (+25%) on $1.8B GMV, its last full year as a public company.

Thumbtack
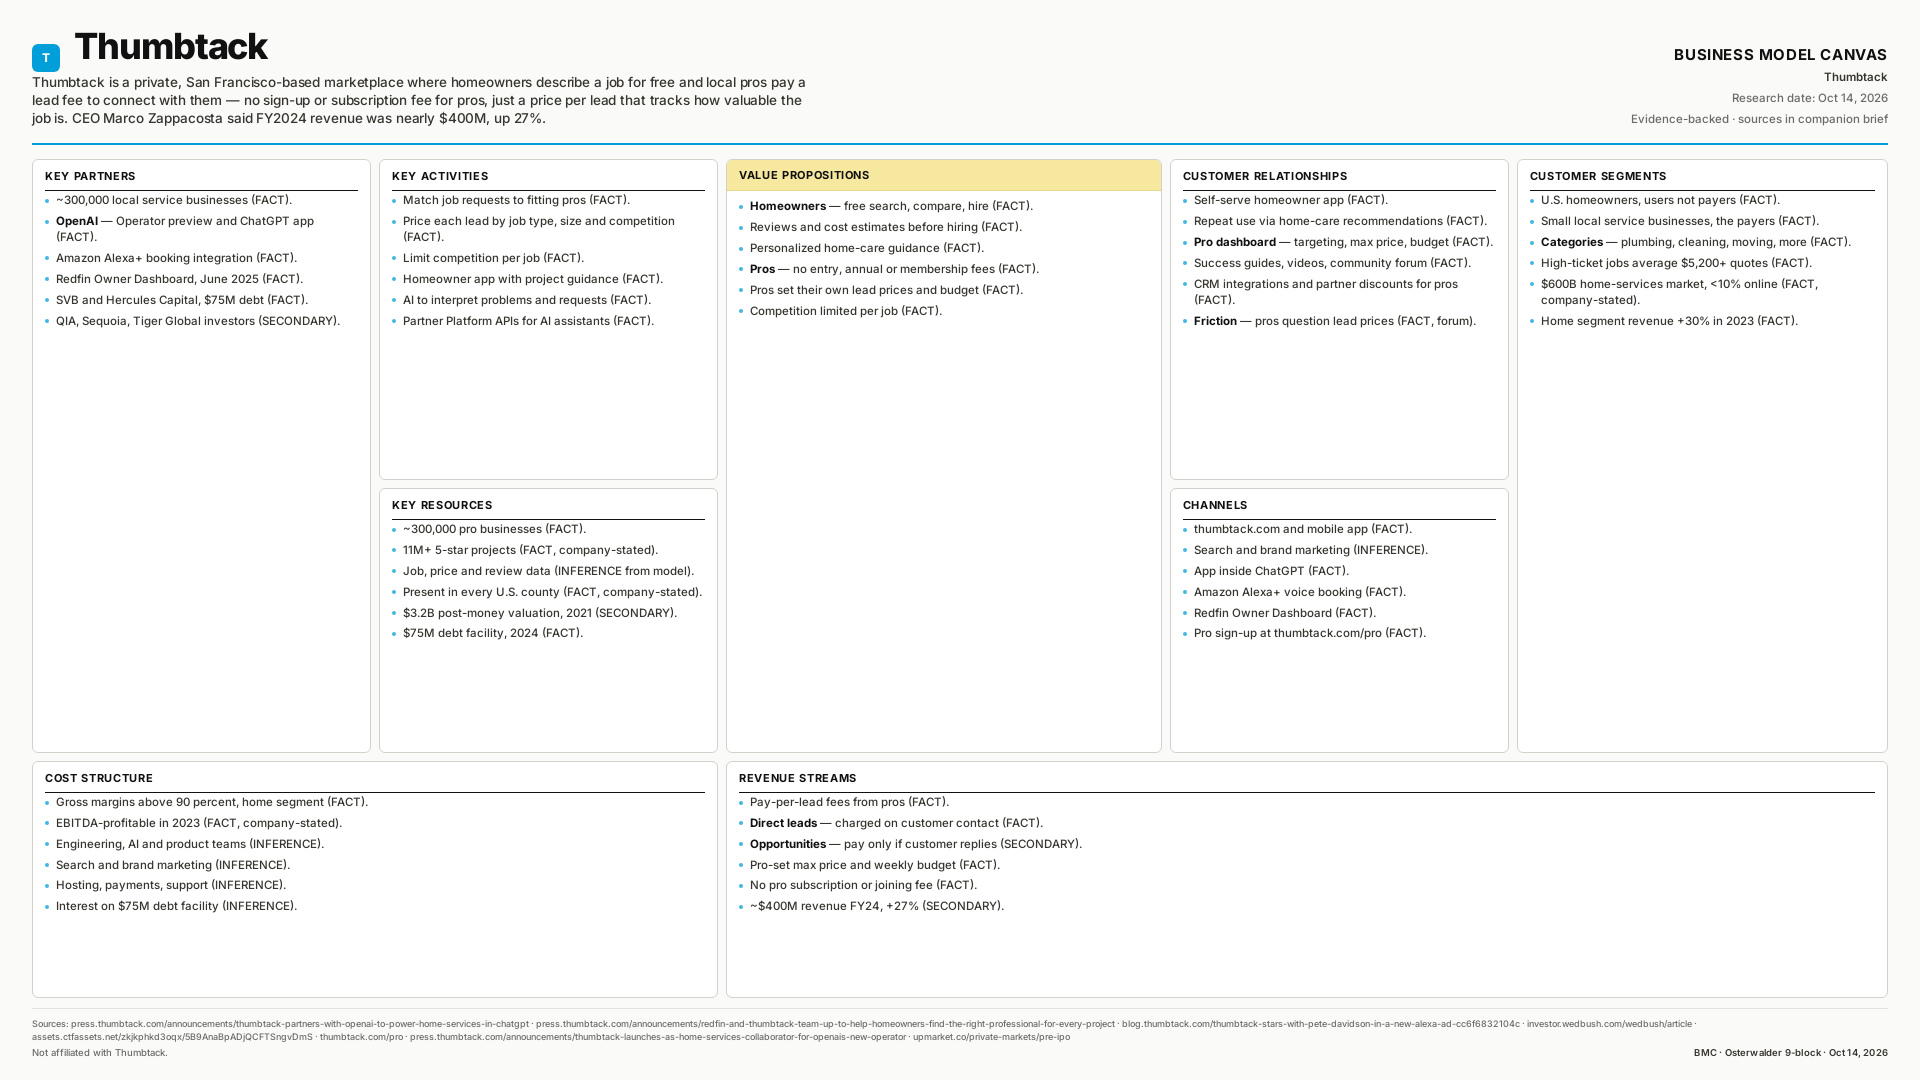
Private home-services marketplace: homeowners search free, local pros pay per lead at prices tied to job value; company-stated FY2024 revenue nearly $400M (+27%).

Fiverr
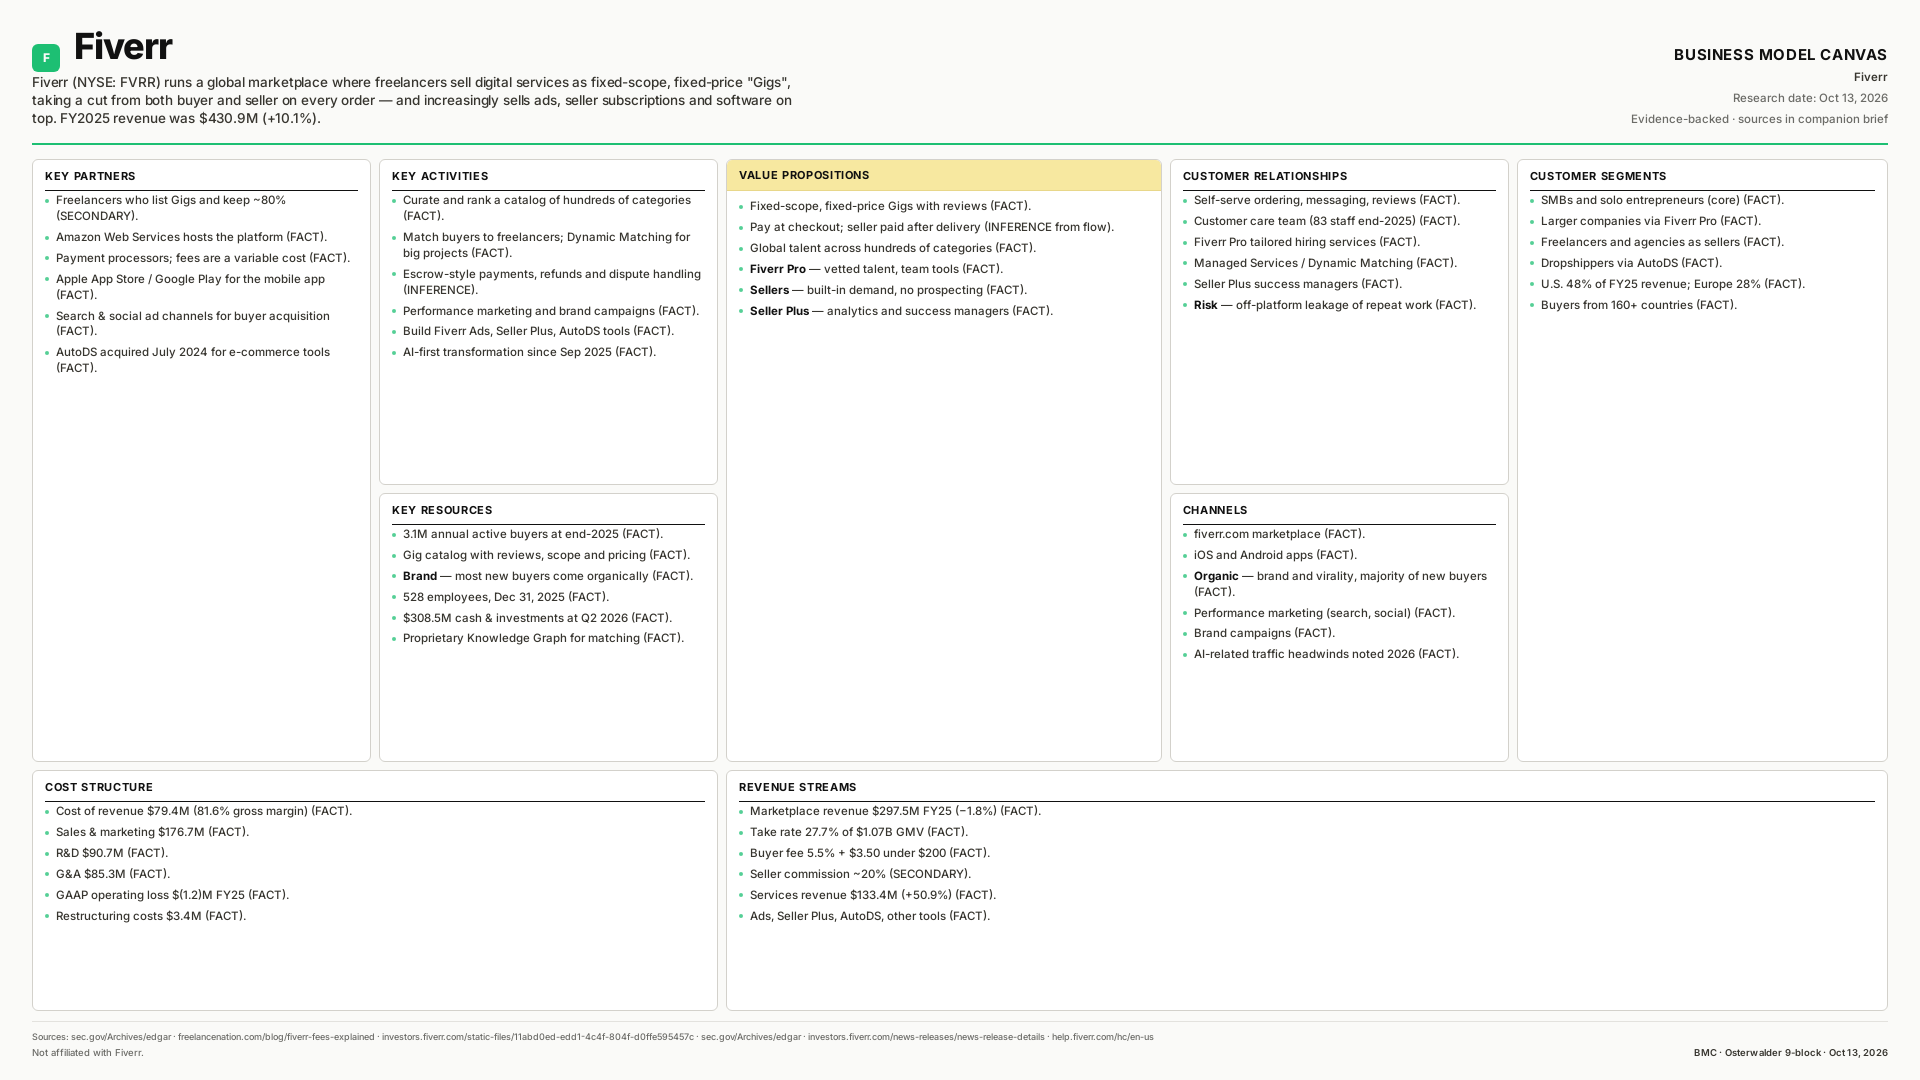
Marketplace for productized freelance Gigs earning a 27.7% two-sided take rate plus ads and seller subscriptions; FY2025 revenue $430.9M (+10.1%), net income $21.0M.
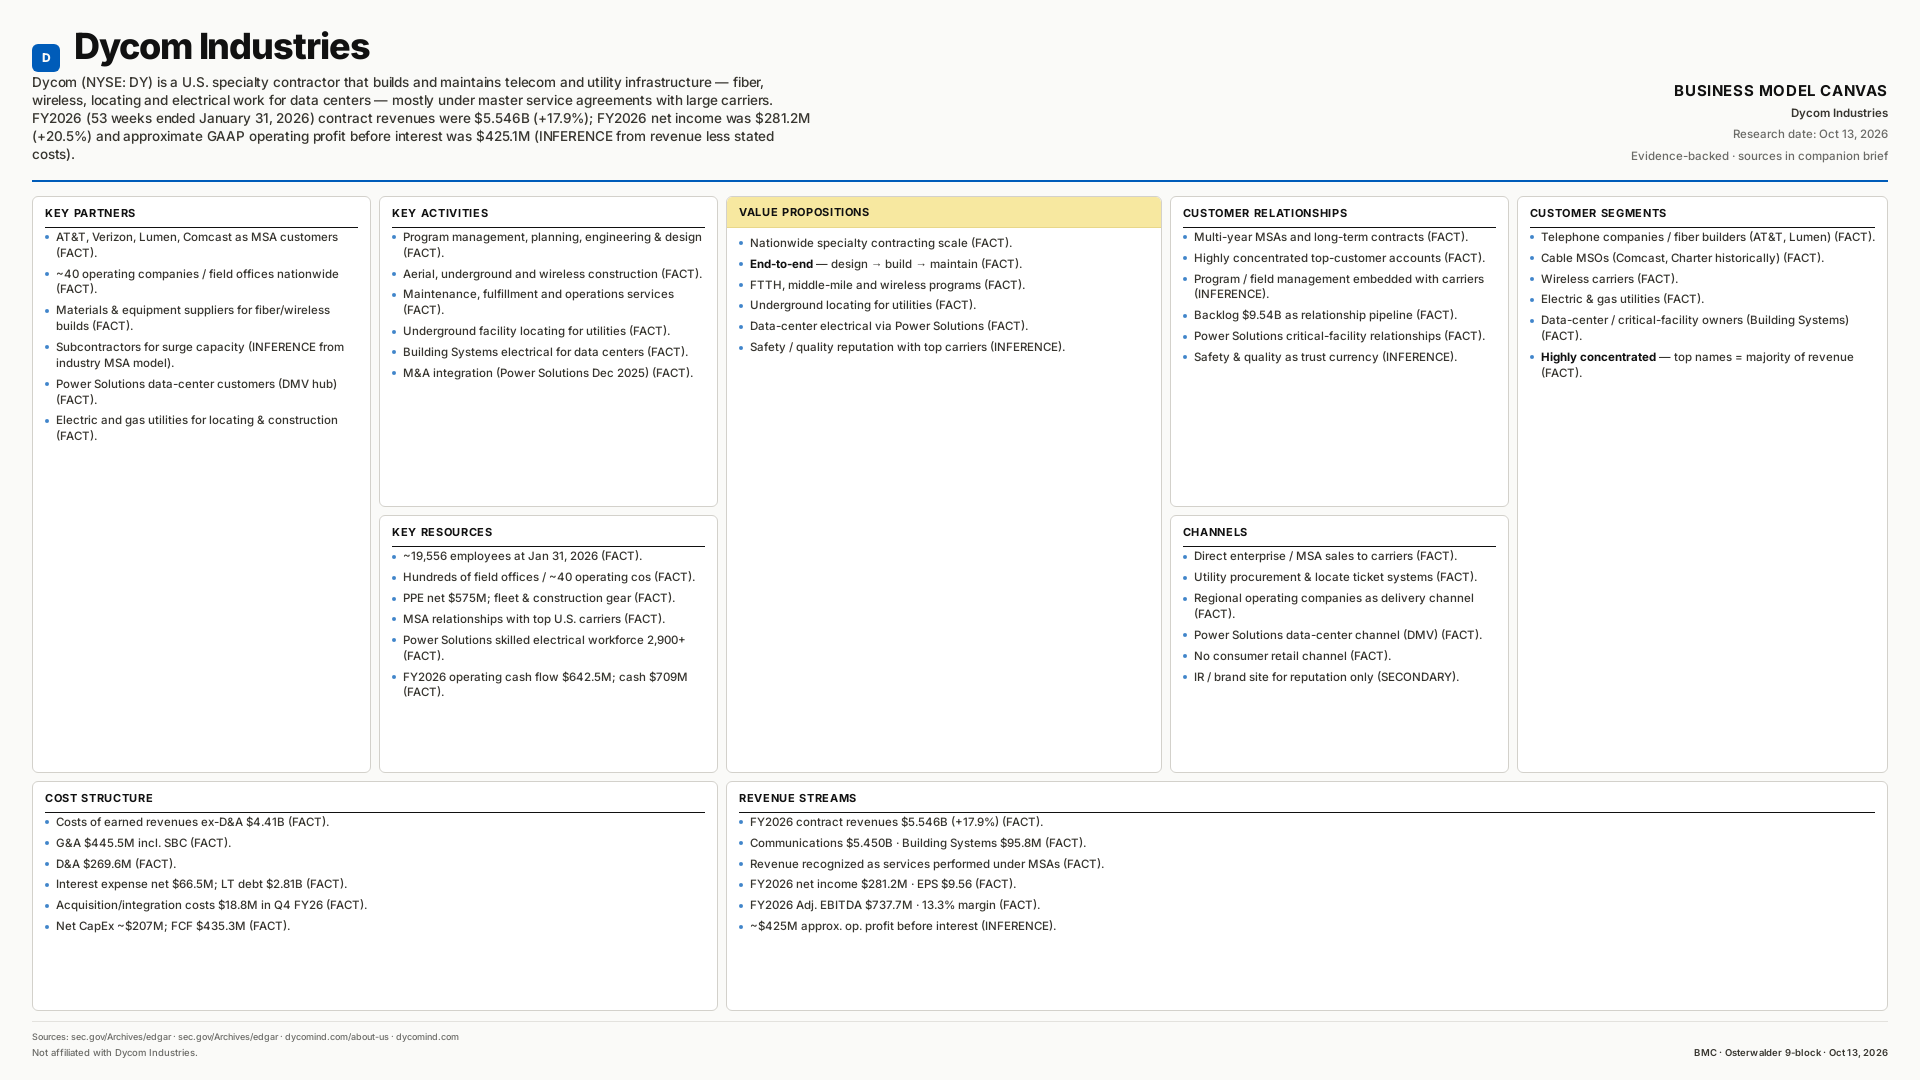

Dycom Industries
Specialty contractor for telecom fiber/wireless and utility infrastructure under MSAs; FY2026 contract revenues $5.546B (+17.9%), net income $281.2M, backlog $9.54B.
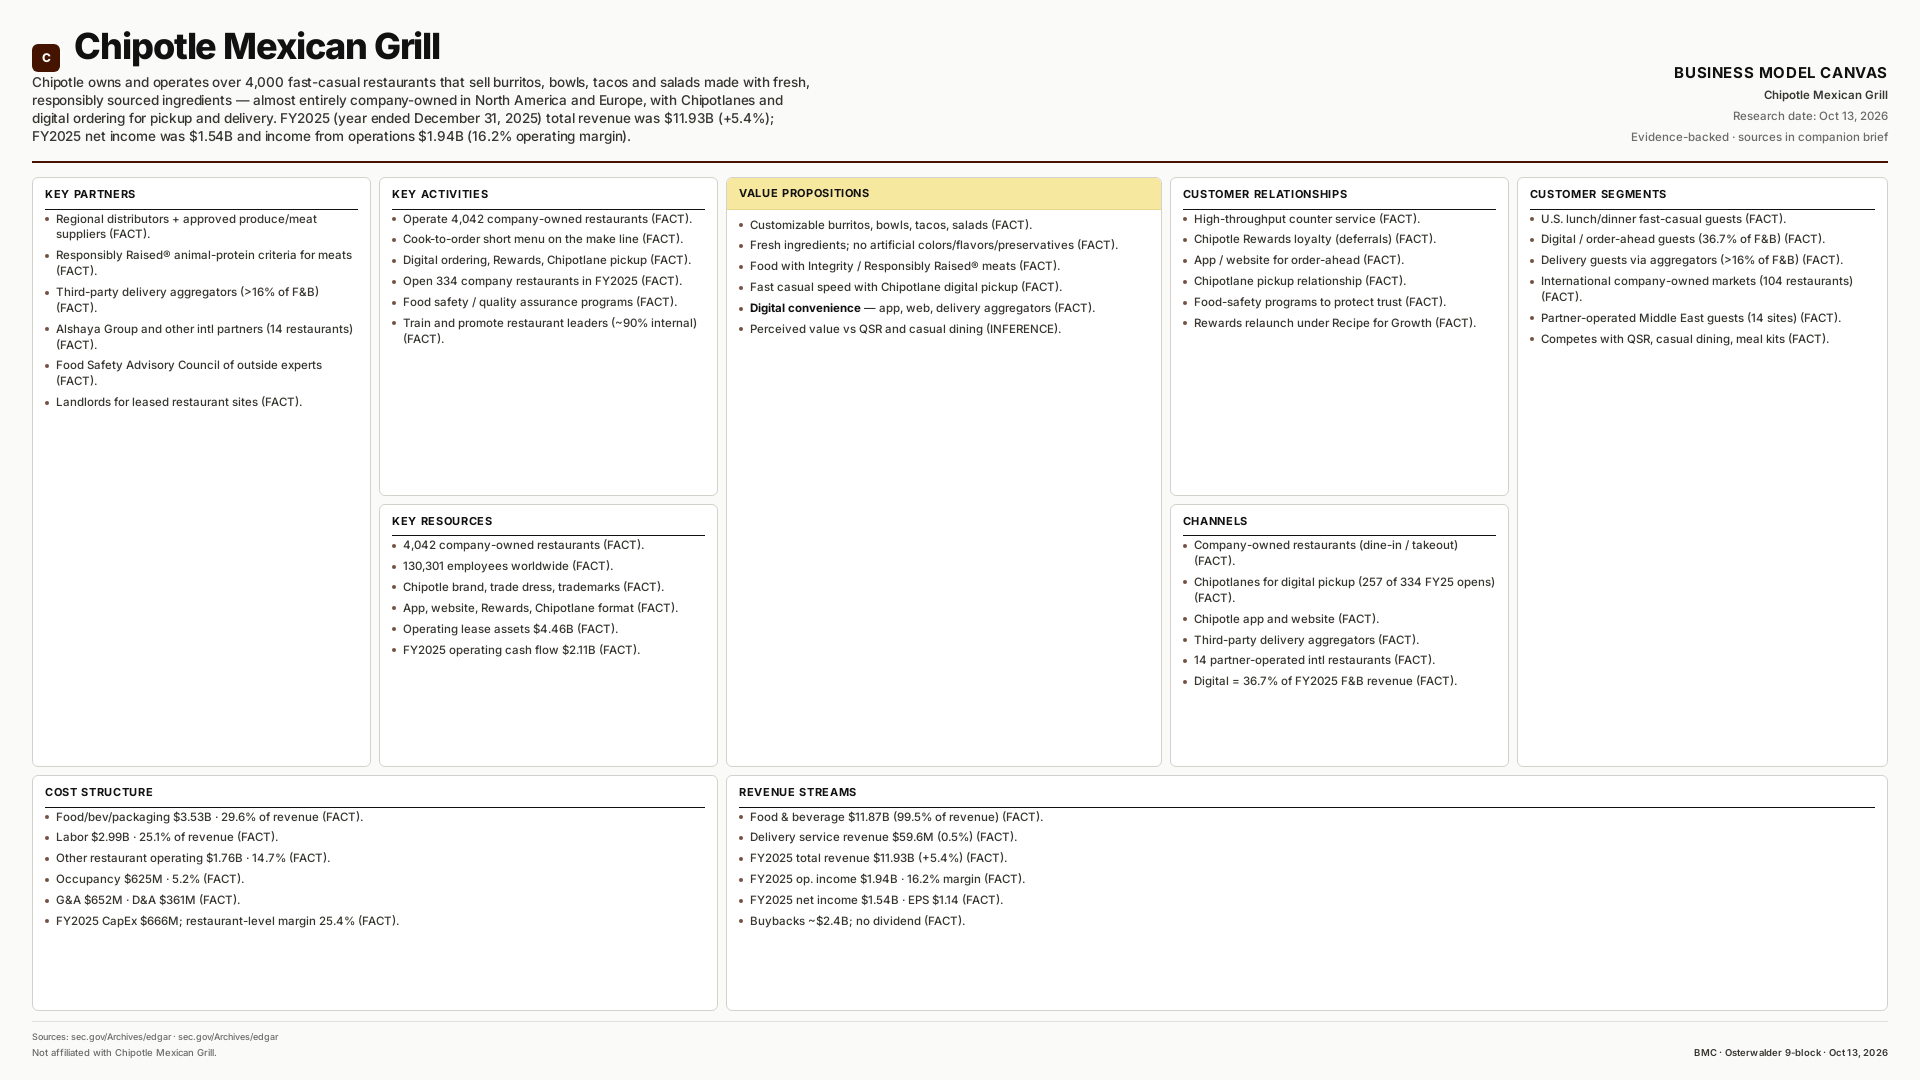

Chipotle Mexican Grill
Company-owned fast-casual restaurants with Food with Integrity, Chipotlanes and digital ordering; FY2025 revenue $11.93B (+5.4%), operating income $1.94B, net income $1.54B.
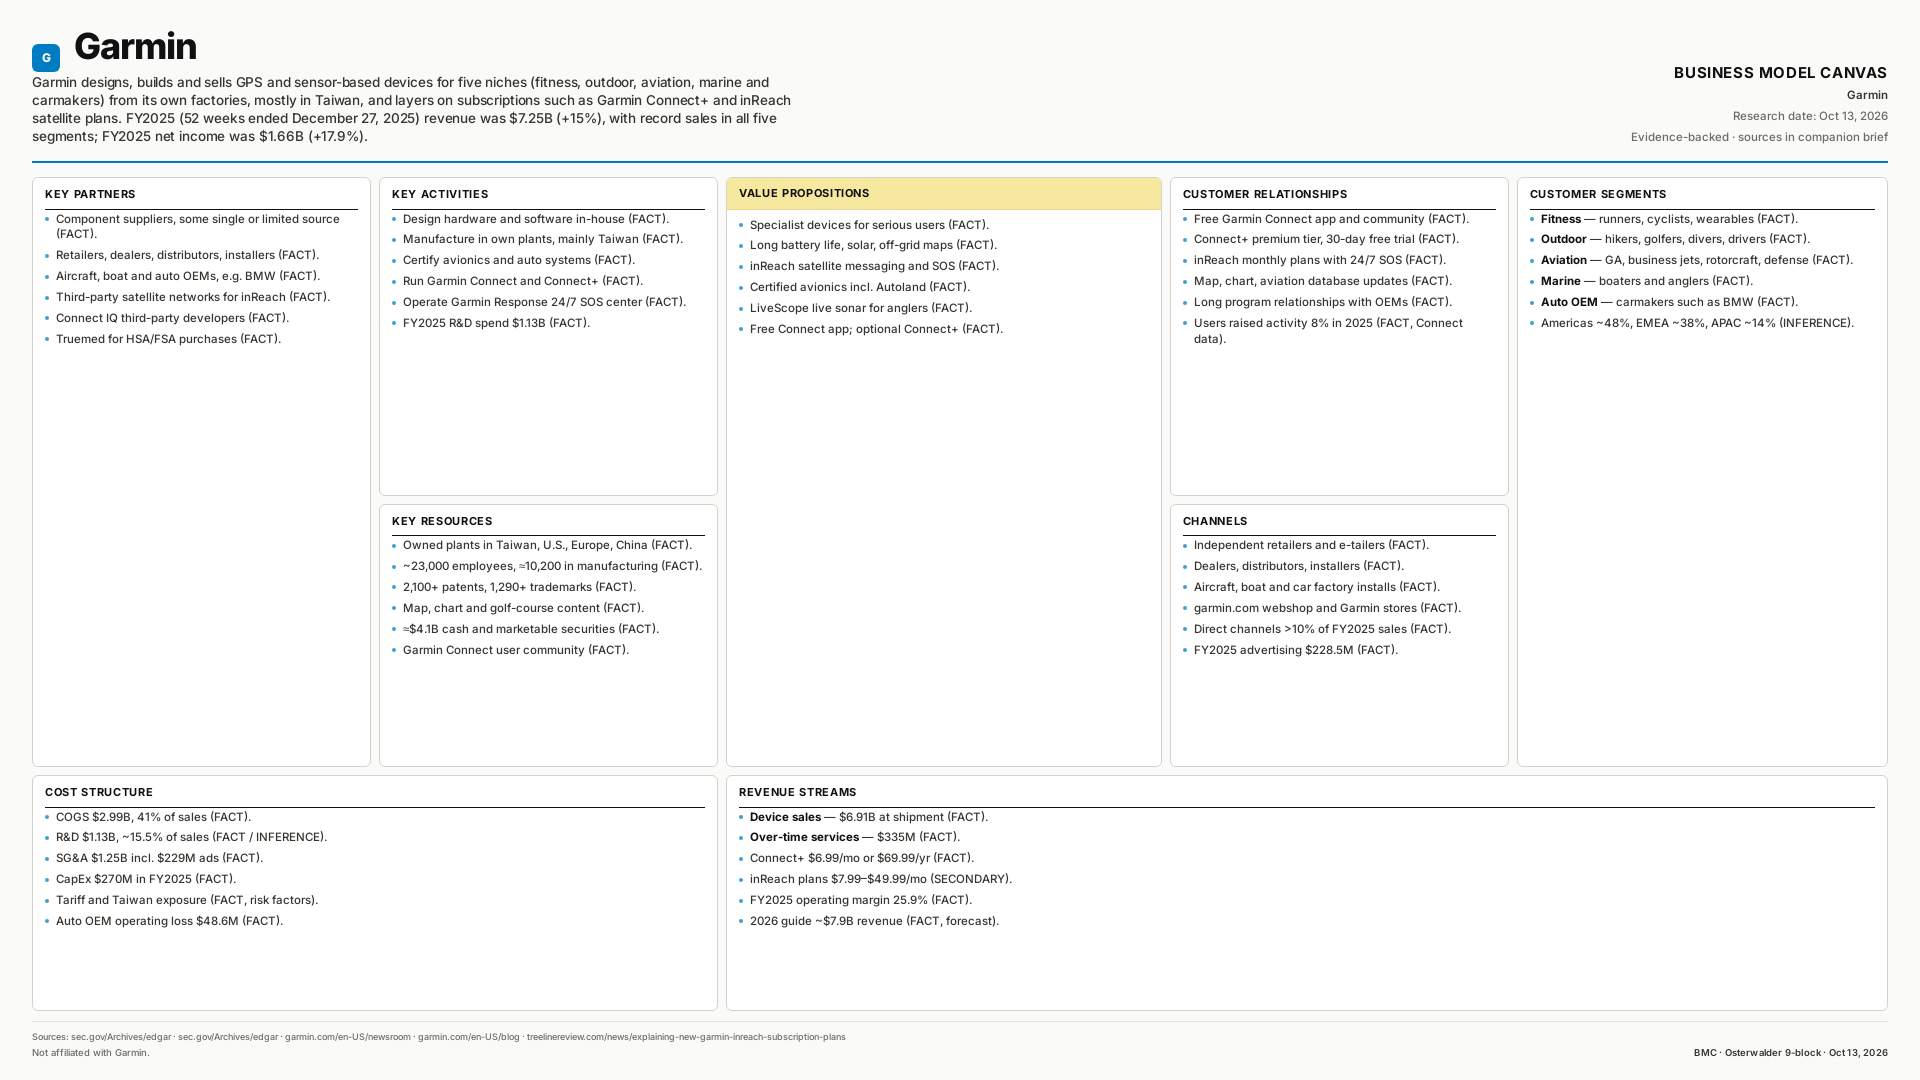

Garmin
Premium, purpose-built GPS and sensor devices for five niches, made in its own factories, with a small subscription layer; FY2025 revenue $7.25B (+15%), operating income $1.88B, net income $1.66B (+17.9%).
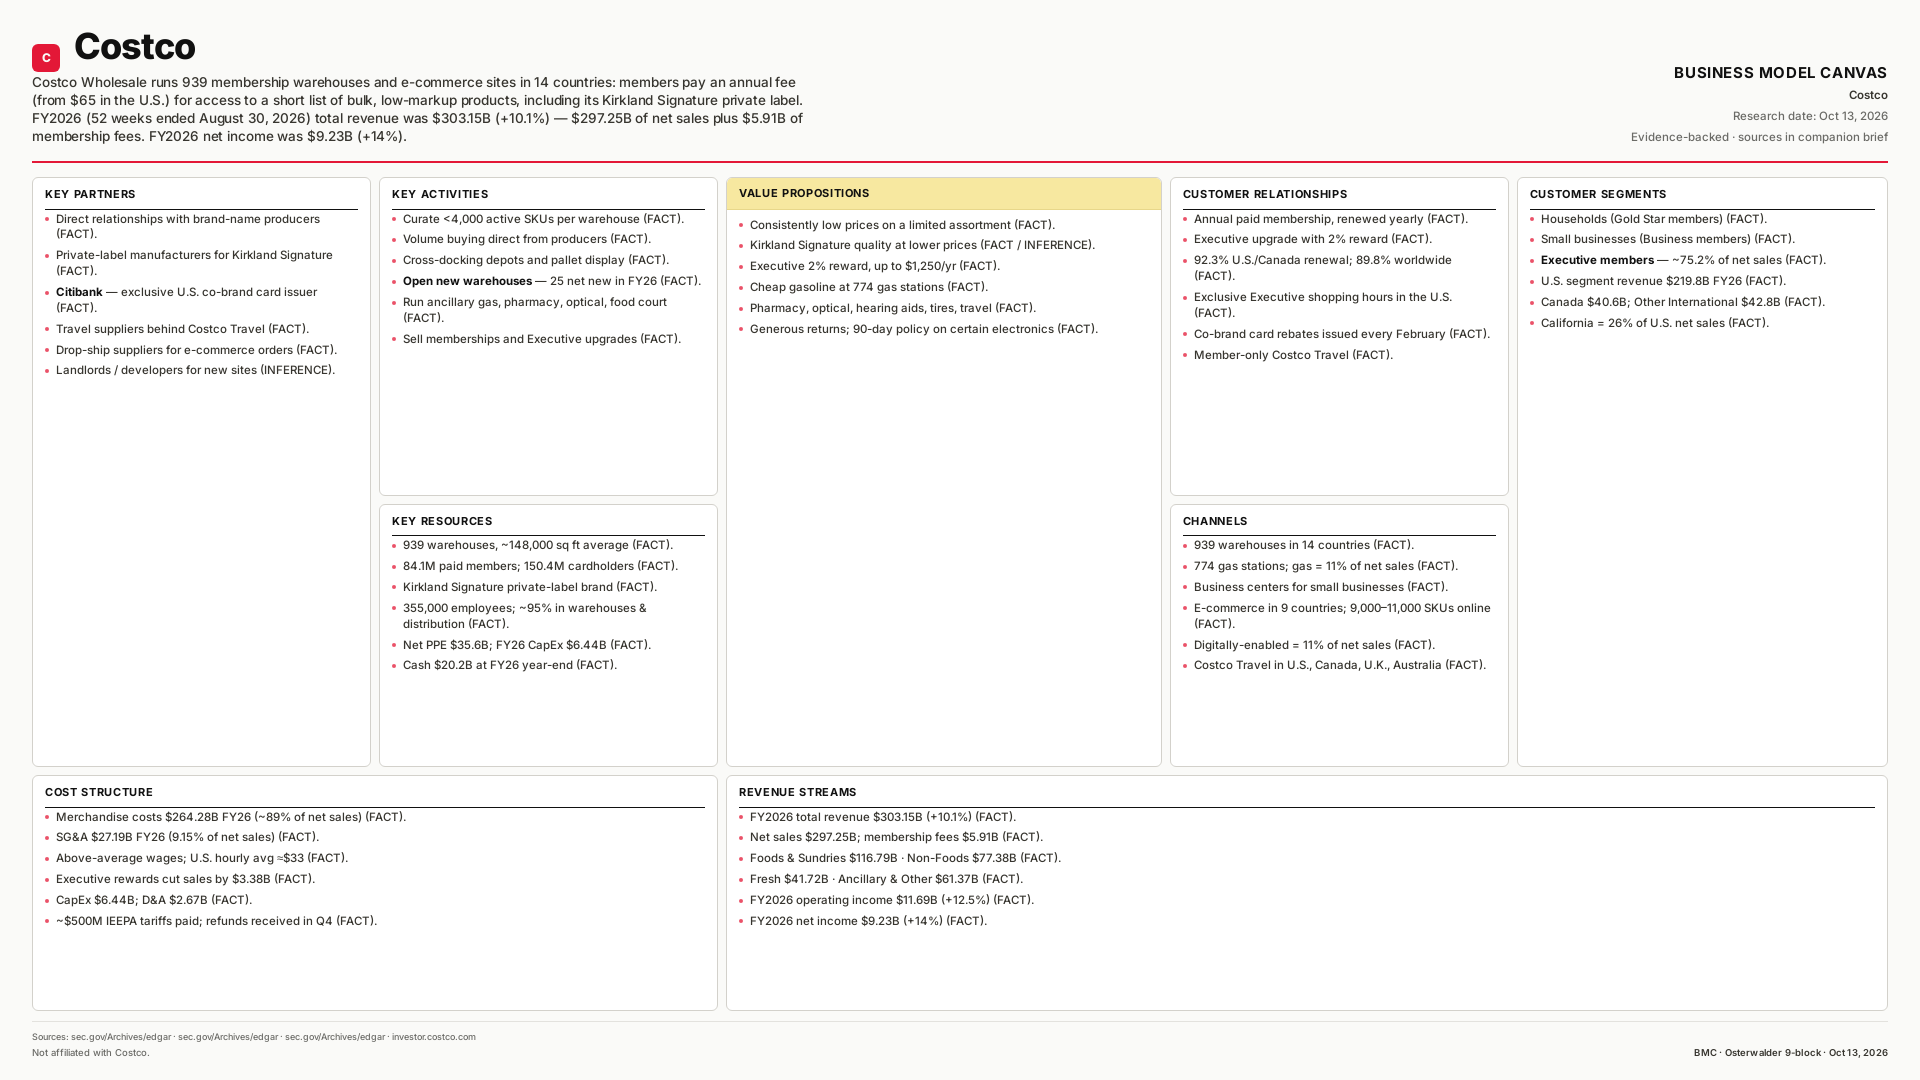

Costco
A membership warehouse club that sells a short list of bulk, low-markup goods to fee-paying members; FY2026 total revenue $303.15B (+10.1%), membership fees $5.91B (+11%), net income $9.23B (+14%).
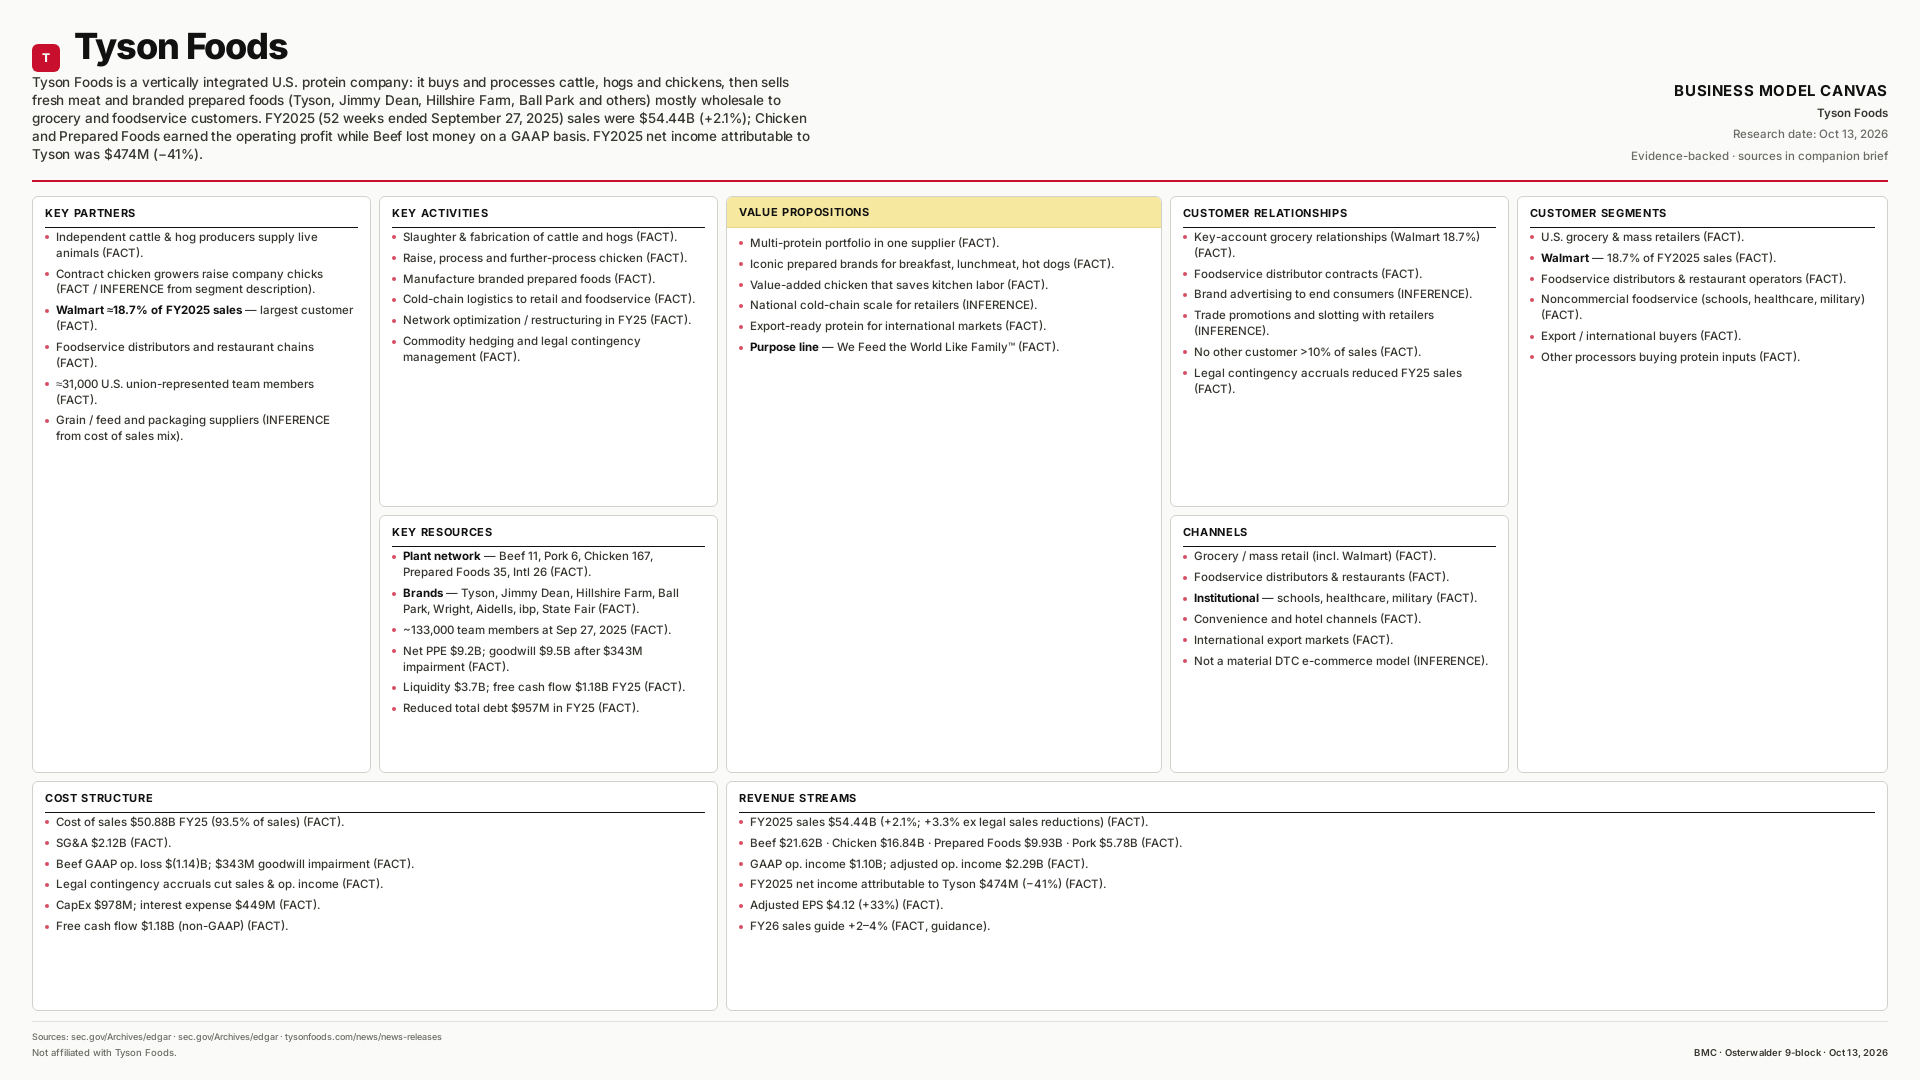

Tyson Foods
A multi-protein processor that sells fresh beef, pork and chicken plus branded prepared foods wholesale to grocery and foodservice; FY2025 sales $54.44B (+2.1%), net income attributable to Tyson $474M (−41%).
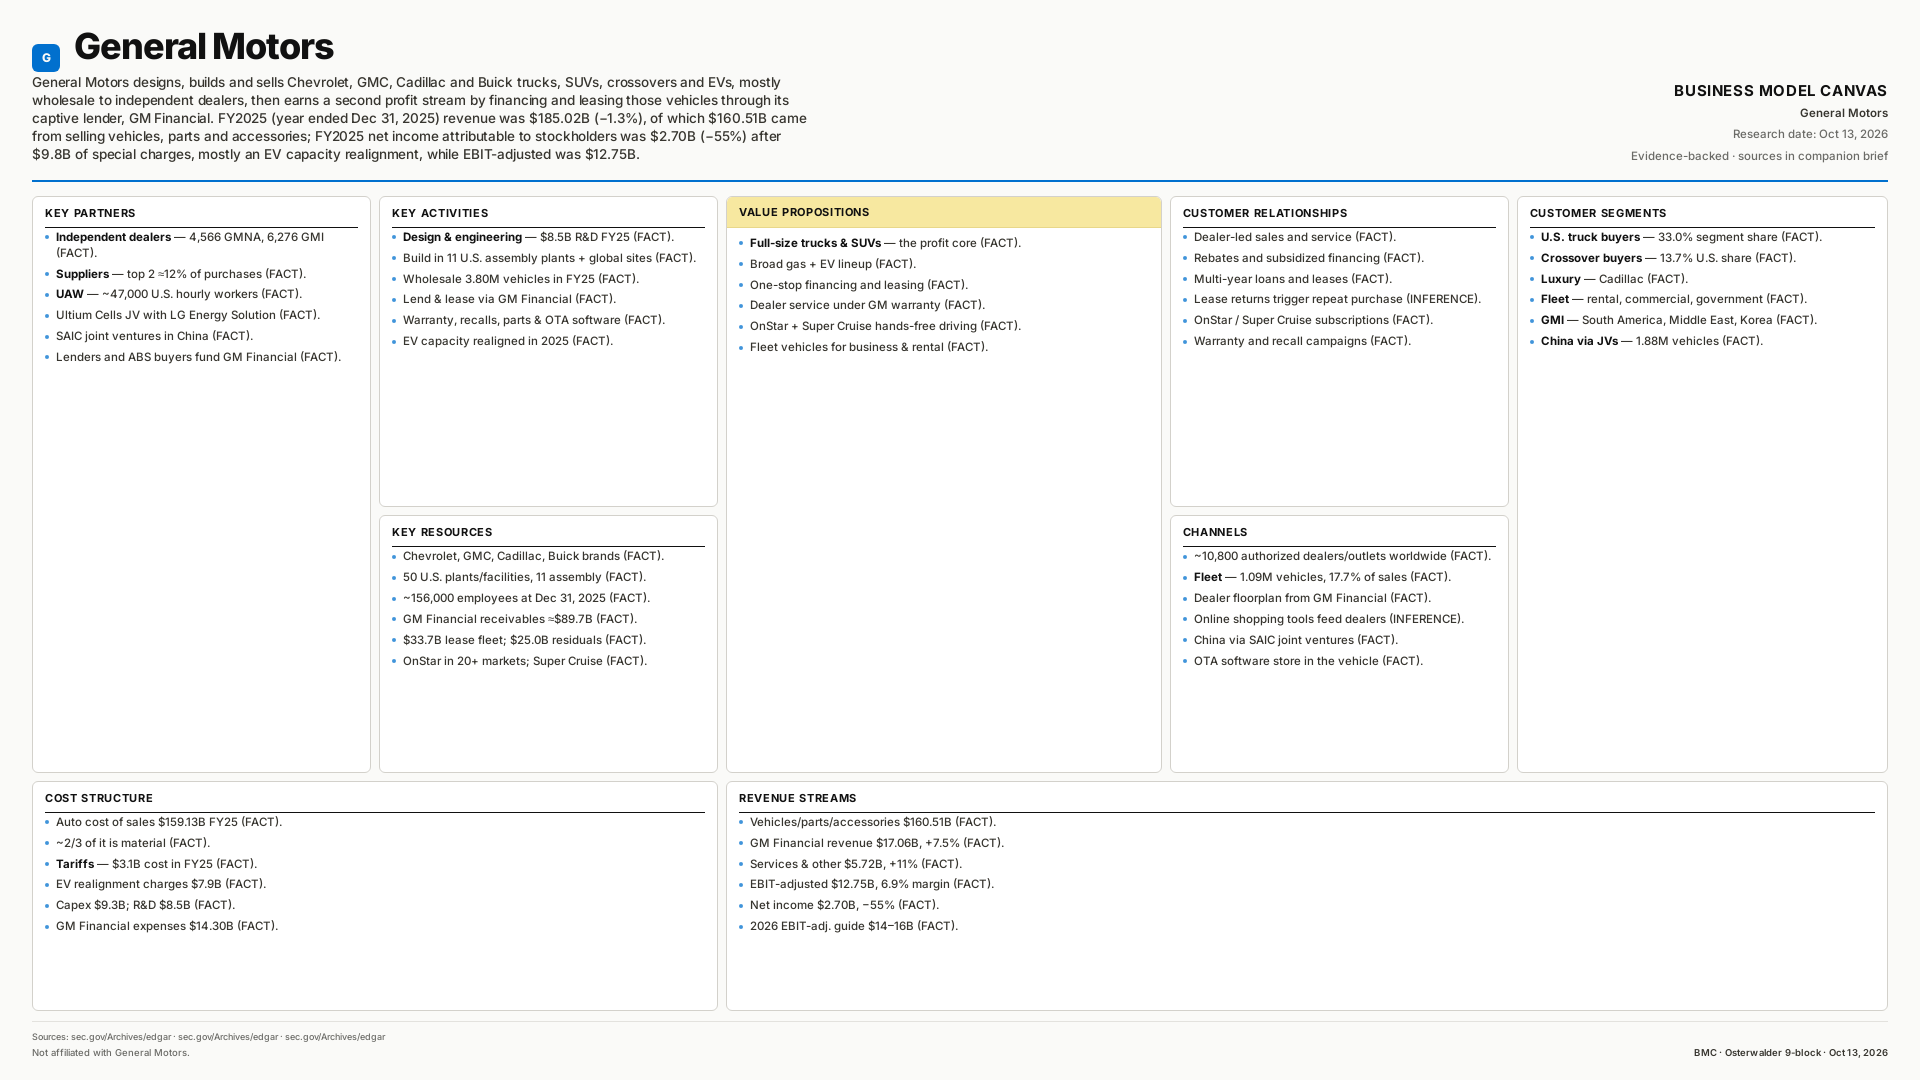

General Motors
A U.S. truck-and-SUV maker that sells vehicles wholesale to independent dealers and finances them through GM Financial; FY2025 revenue $185.02B (−1.3%), net income $2.70B after EV charges, EBIT-adjusted $12.75B.
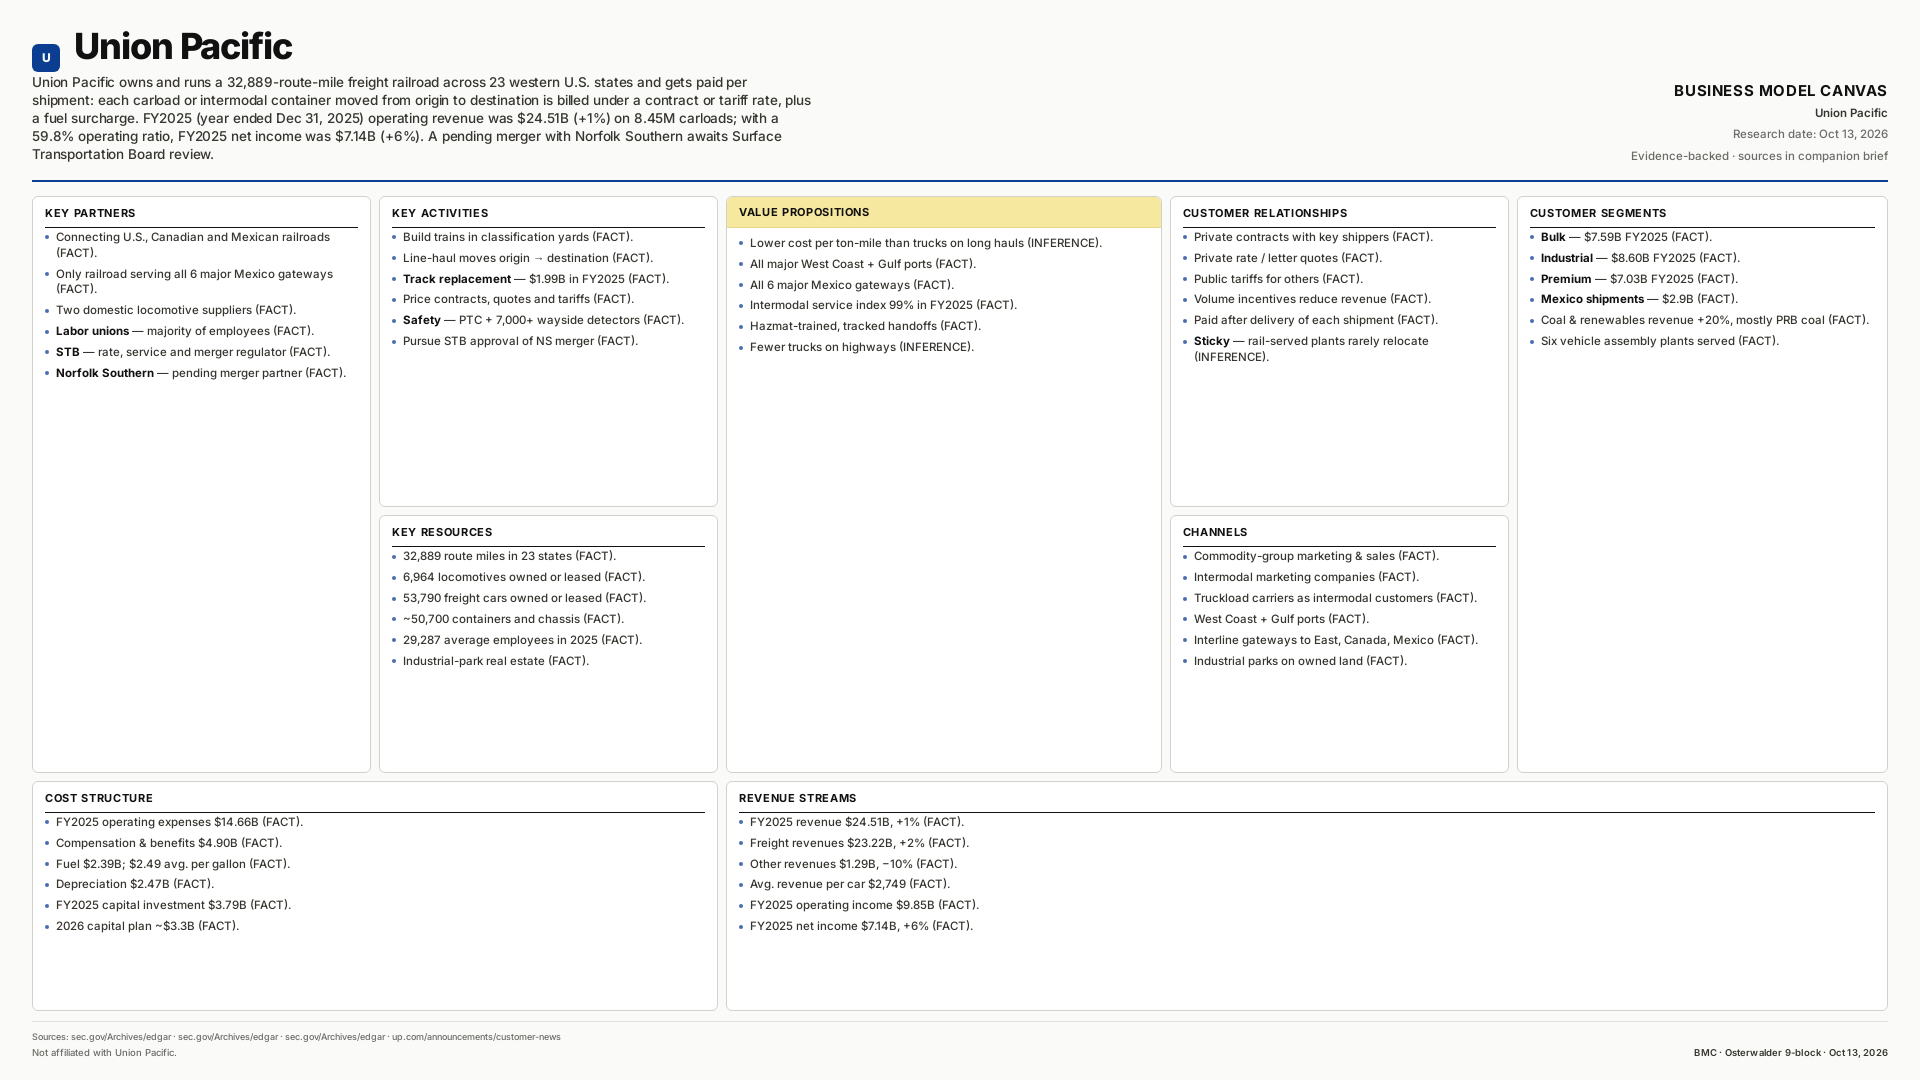

Union Pacific
A western U.S. freight railroad paid per shipment — a rate per carload or container plus fuel surcharge on 32,889 route miles; FY2025 revenue $24.51B (+1%), net income $7.14B at a 59.8% operating ratio.
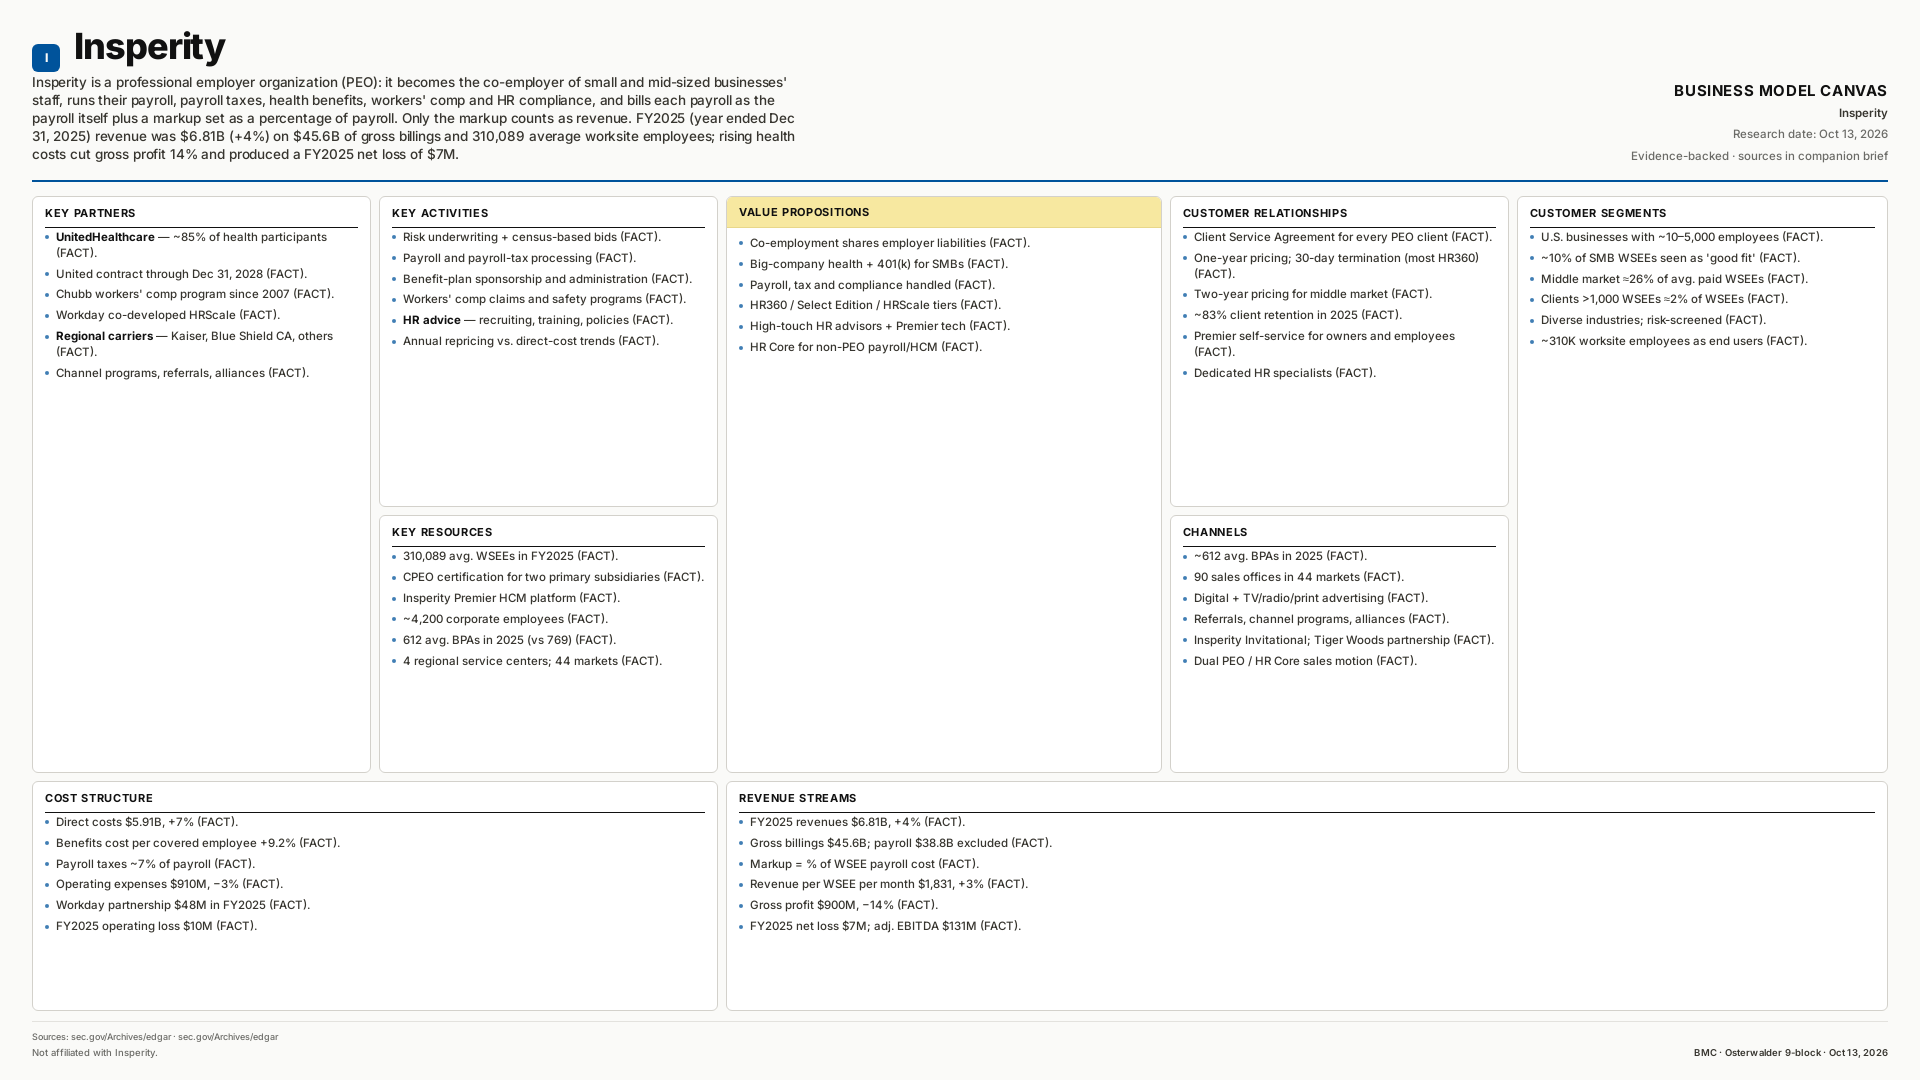

Insperity
A professional employer organization that co-employs ~310,000 worksite employees at U.S. small and mid-sized firms and earns a markup on every payroll; FY2025 revenue $6.81B (+4%), net loss $7M as health costs spiked.
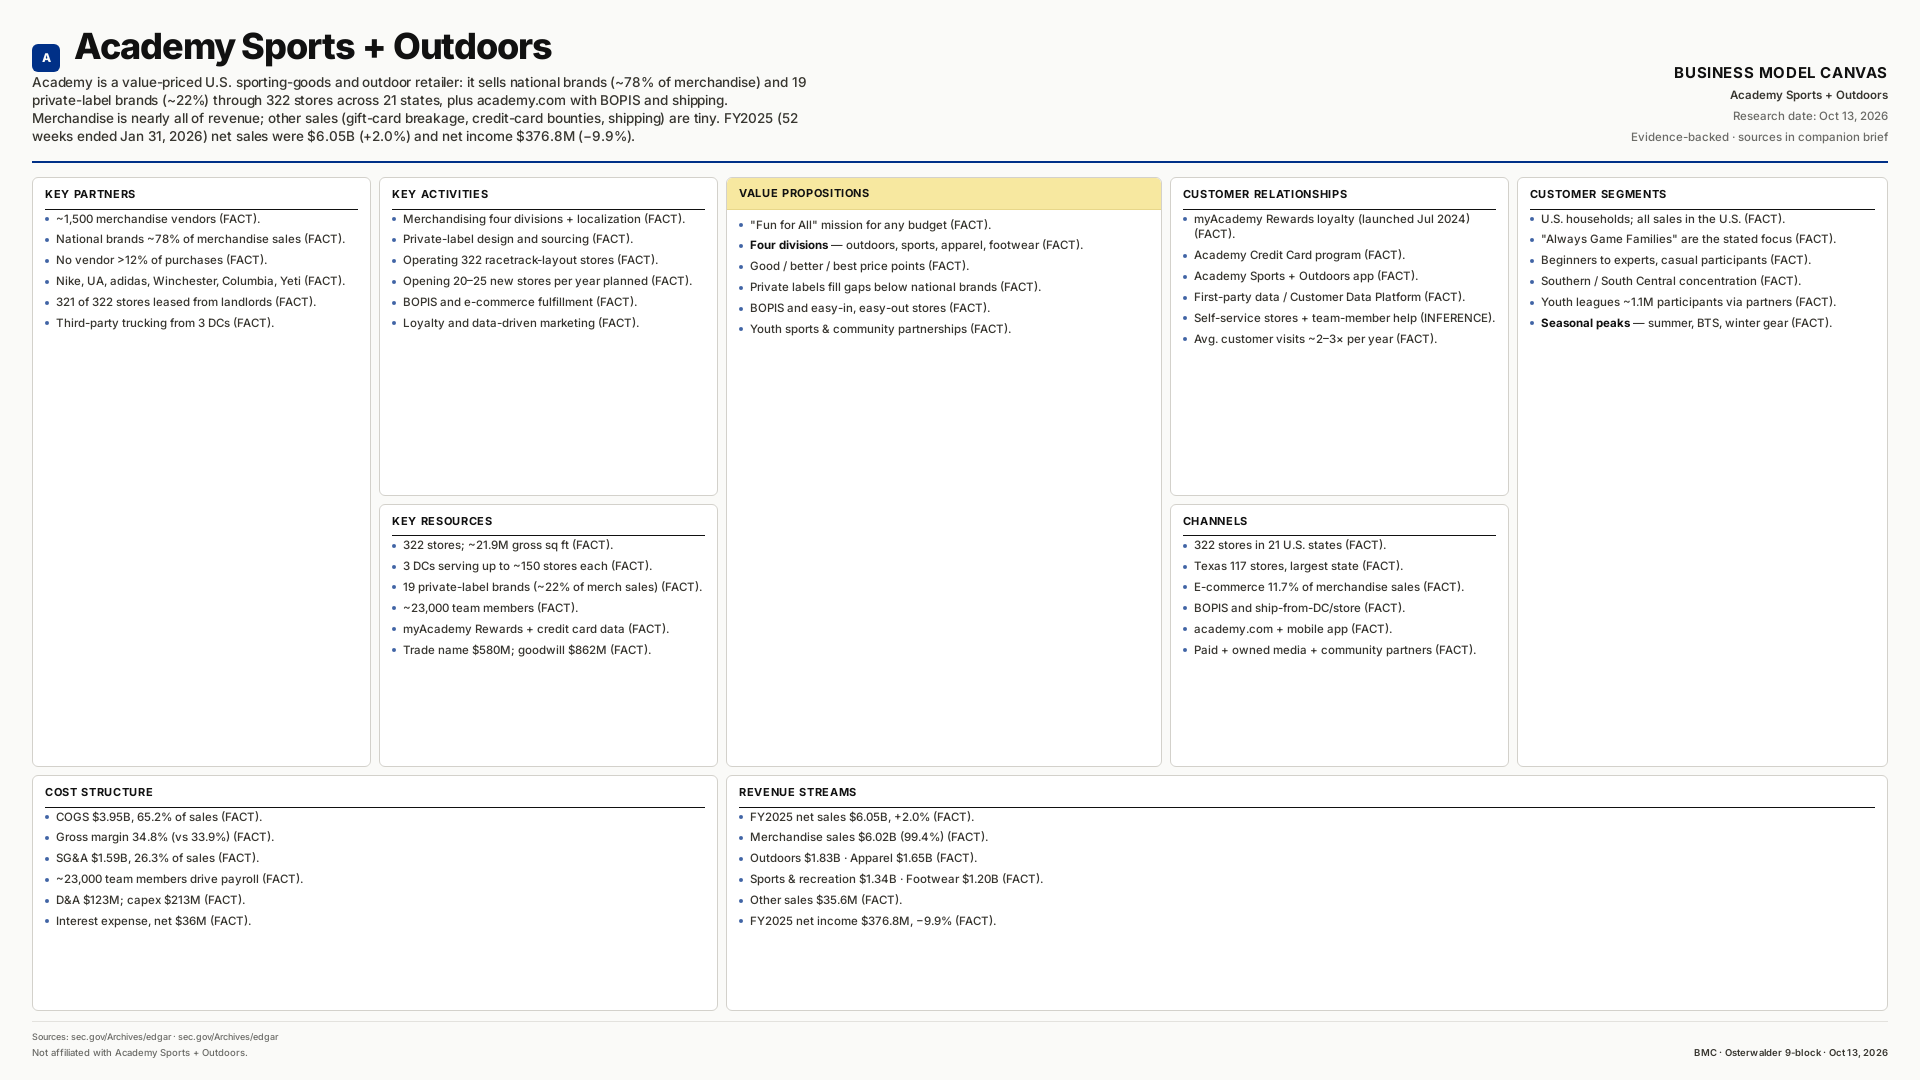

Academy Sports + Outdoors
A value-priced sporting-goods retailer with 322 southern U.S. stores: national brands (~78%) plus 19 private labels (~22%), growing via new stores and BOPIS; FY2025 revenue $6.05B (+2.0%), net income $376.8M.
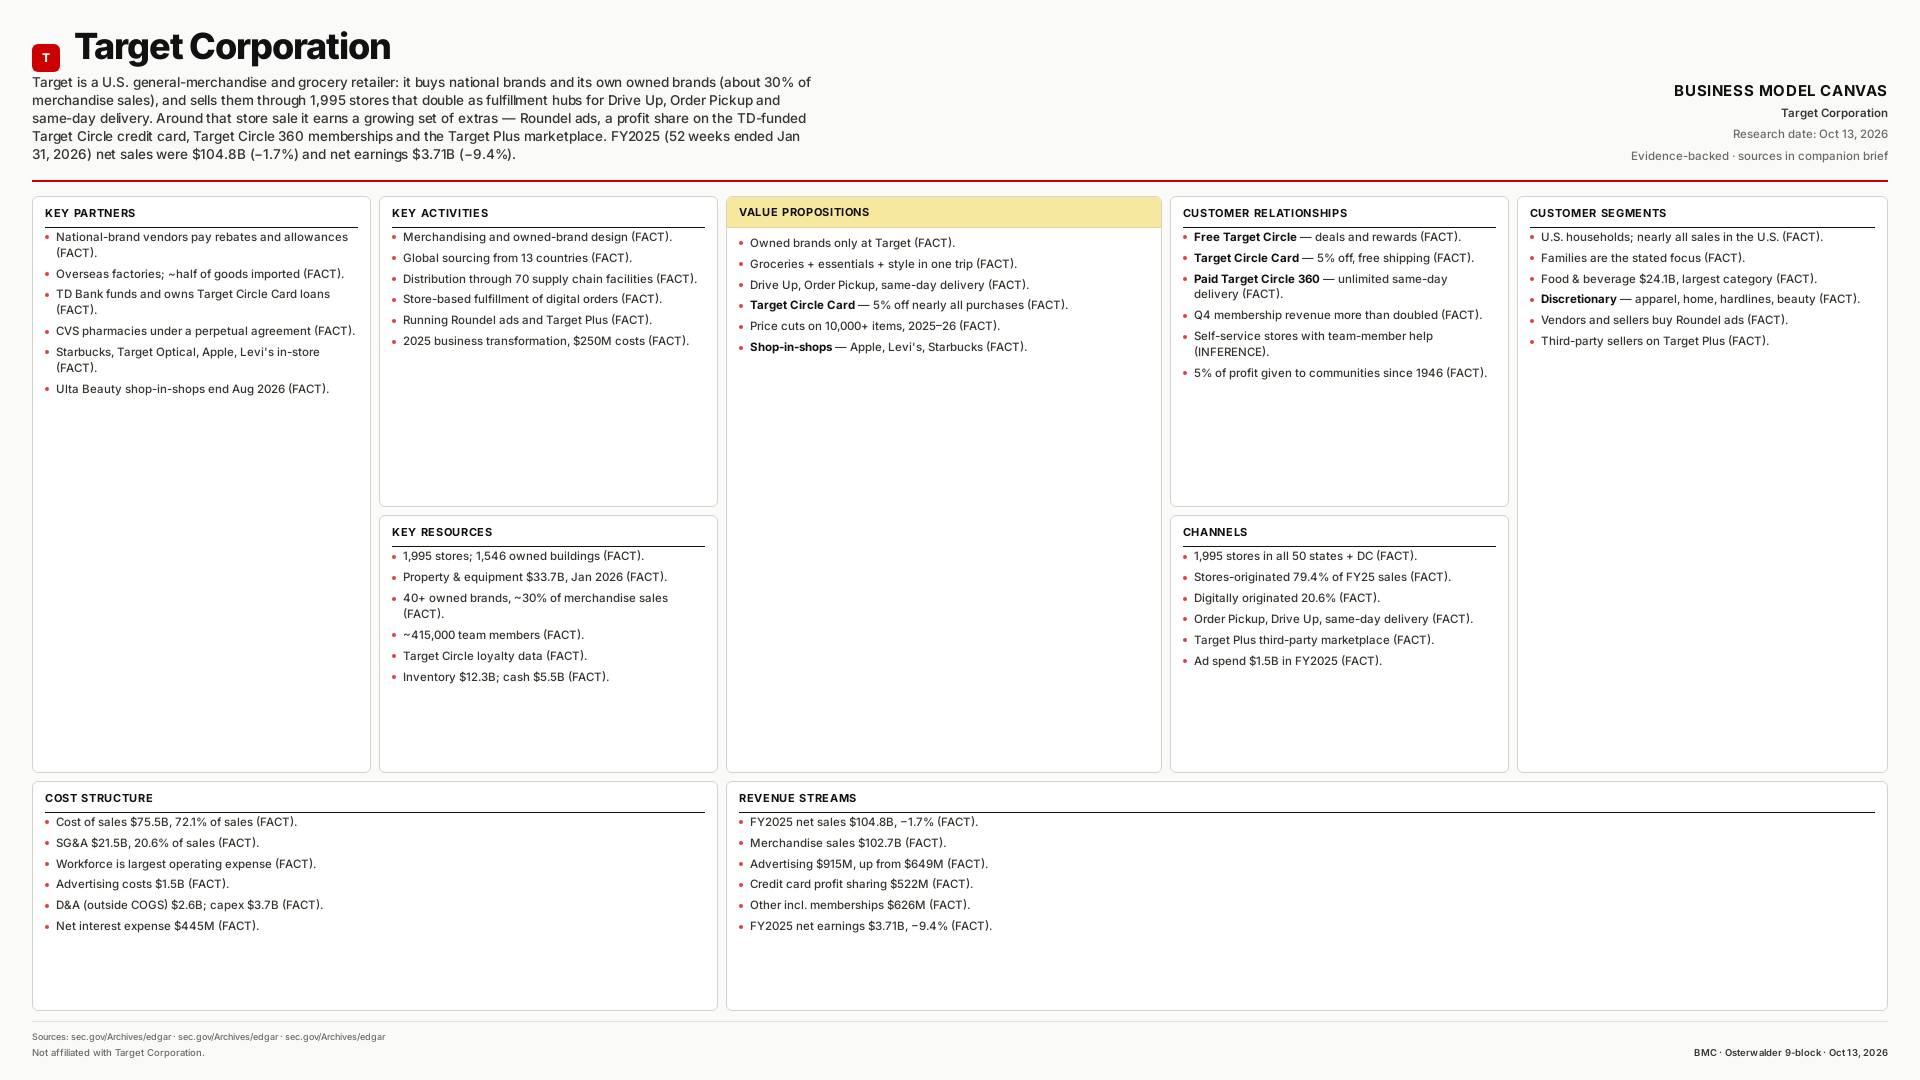

Target Corporation
A big-box retailer whose 1,995 stores double as fulfillment hubs: national and owned brands (~30% of sales), plus Roundel ads, a TD card profit share and Circle 360 memberships; FY2025 revenue $104.8B (−1.7%), net earnings $3.71B.
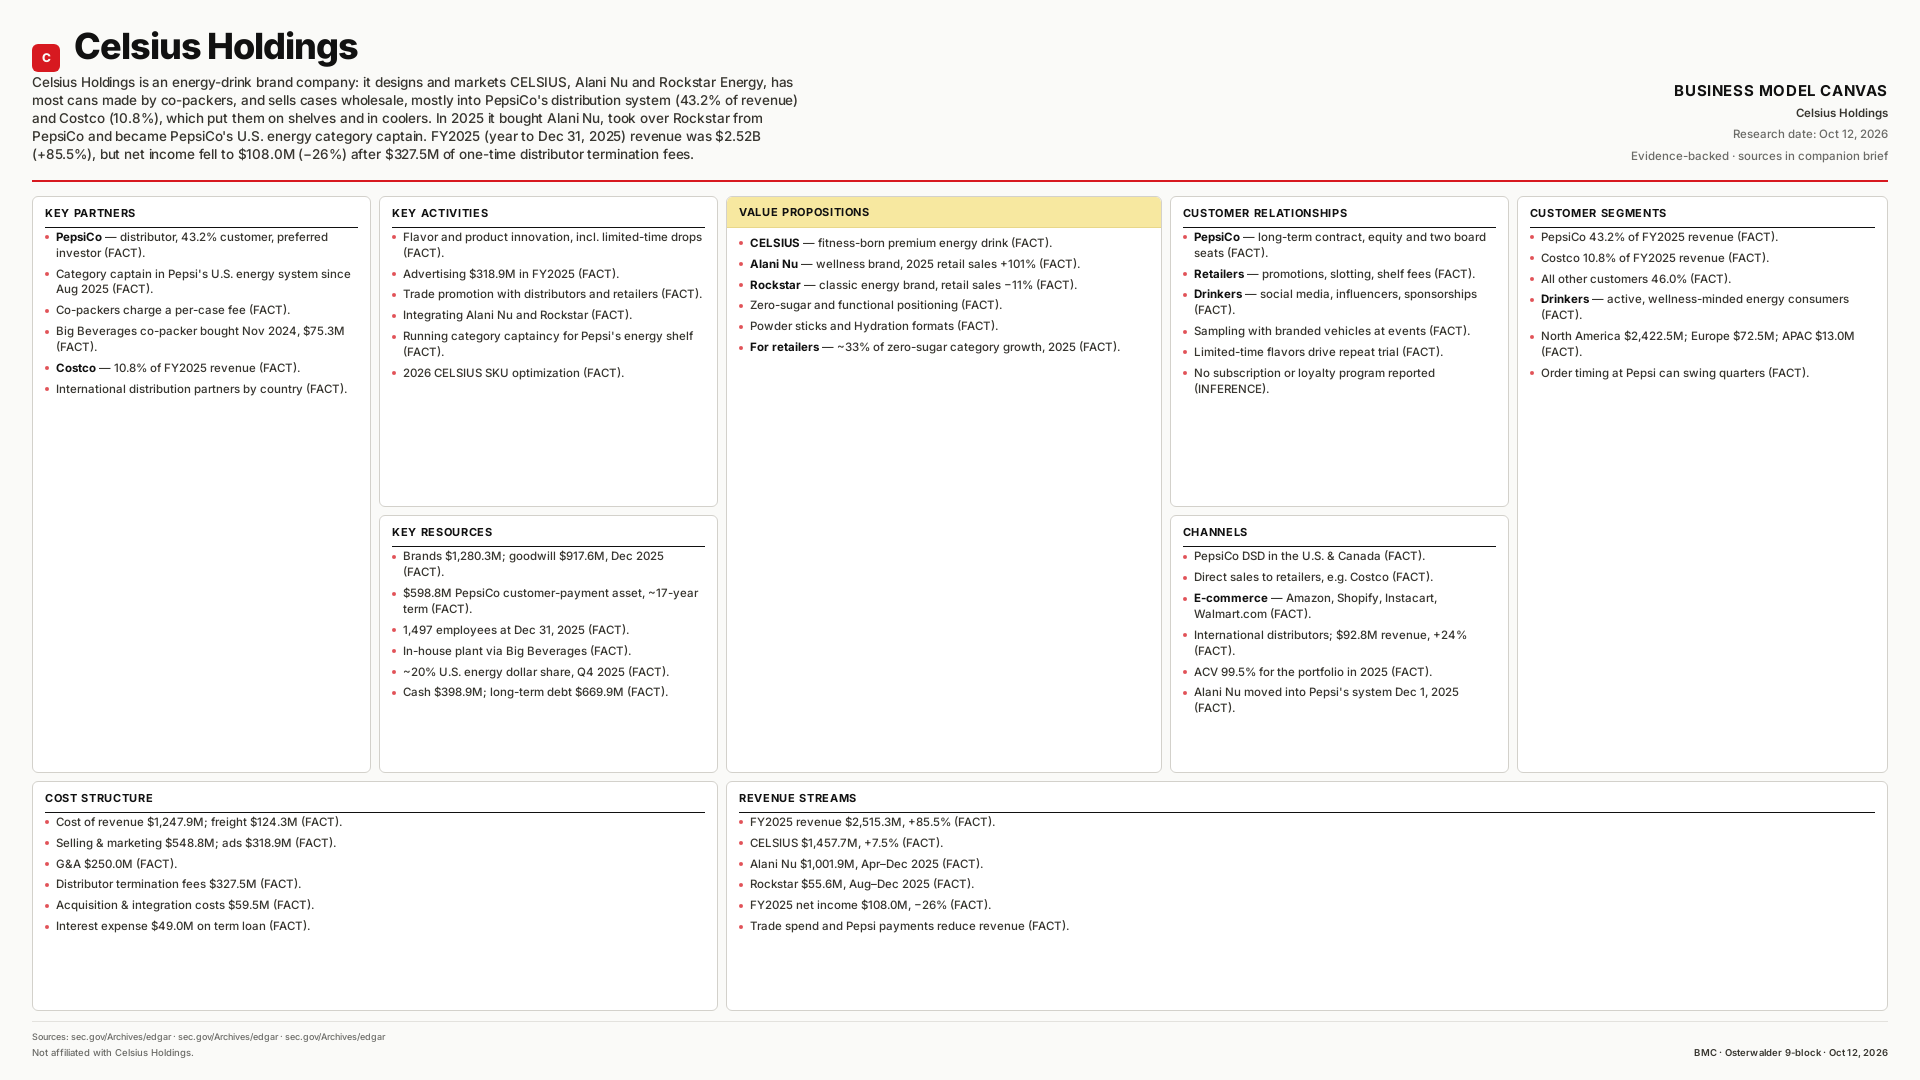

Celsius Holdings
An asset-light energy-drink brand company: three brands (CELSIUS, Alani Nu, Rockstar) made mostly by co-packers and sold wholesale, 43.2% to PepsiCo; FY2025 revenue $2.52B (+85.5%), net income $108.0M.
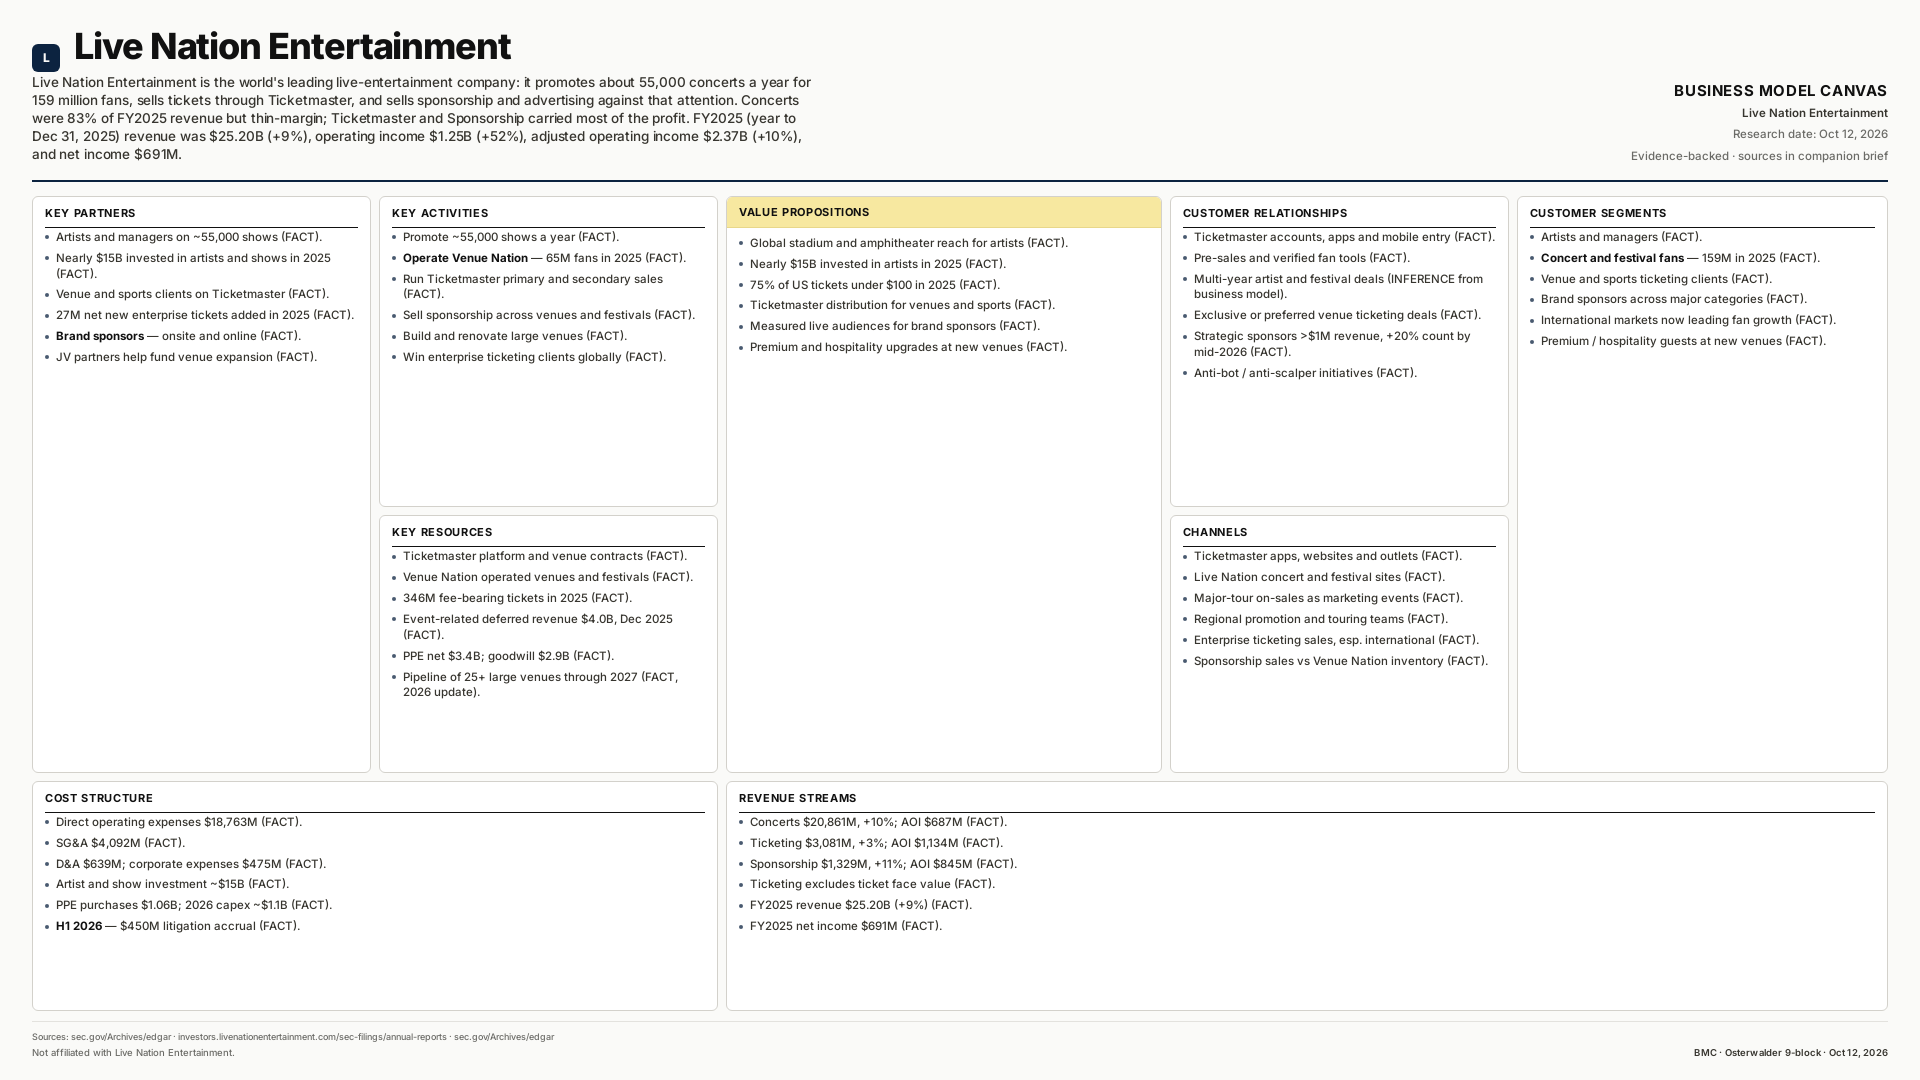

Live Nation Entertainment
A live-entertainment flywheel: promote concerts for 159M fans, take Ticketmaster service fees on 346M tickets, and sell sponsorship against that attention; FY2025 revenue $25.20B (+9%), operating income $1.25B, net income $691M.
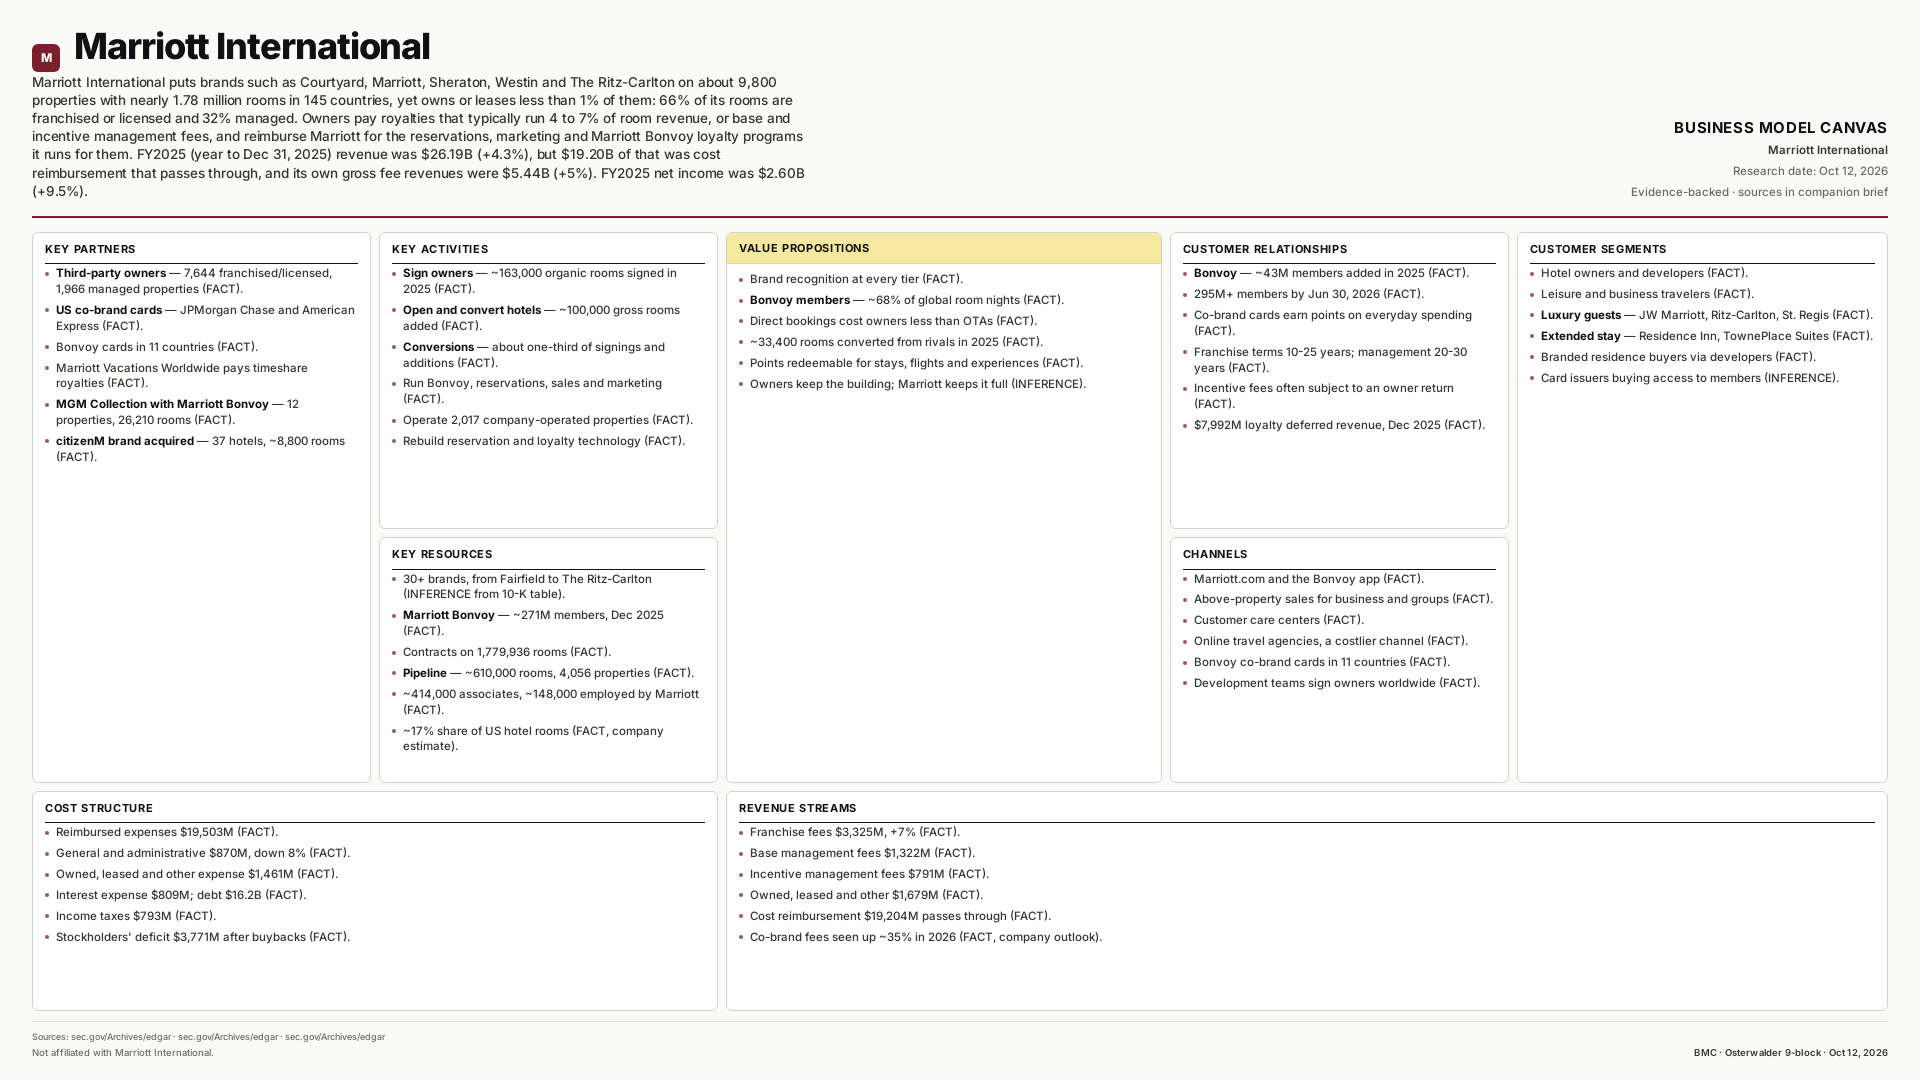

Marriott International
The world's biggest hotel brand owner barely owns hotels: it puts Courtyard, Sheraton, Westin, Ritz-Carlton and dozens more on ~9,800 owners' properties for fees on their revenue and profit, with Marriott Bonvoy (~271M members) as the draw; FY2025 revenue $26.19B (+4.3%), net income $2.60B.
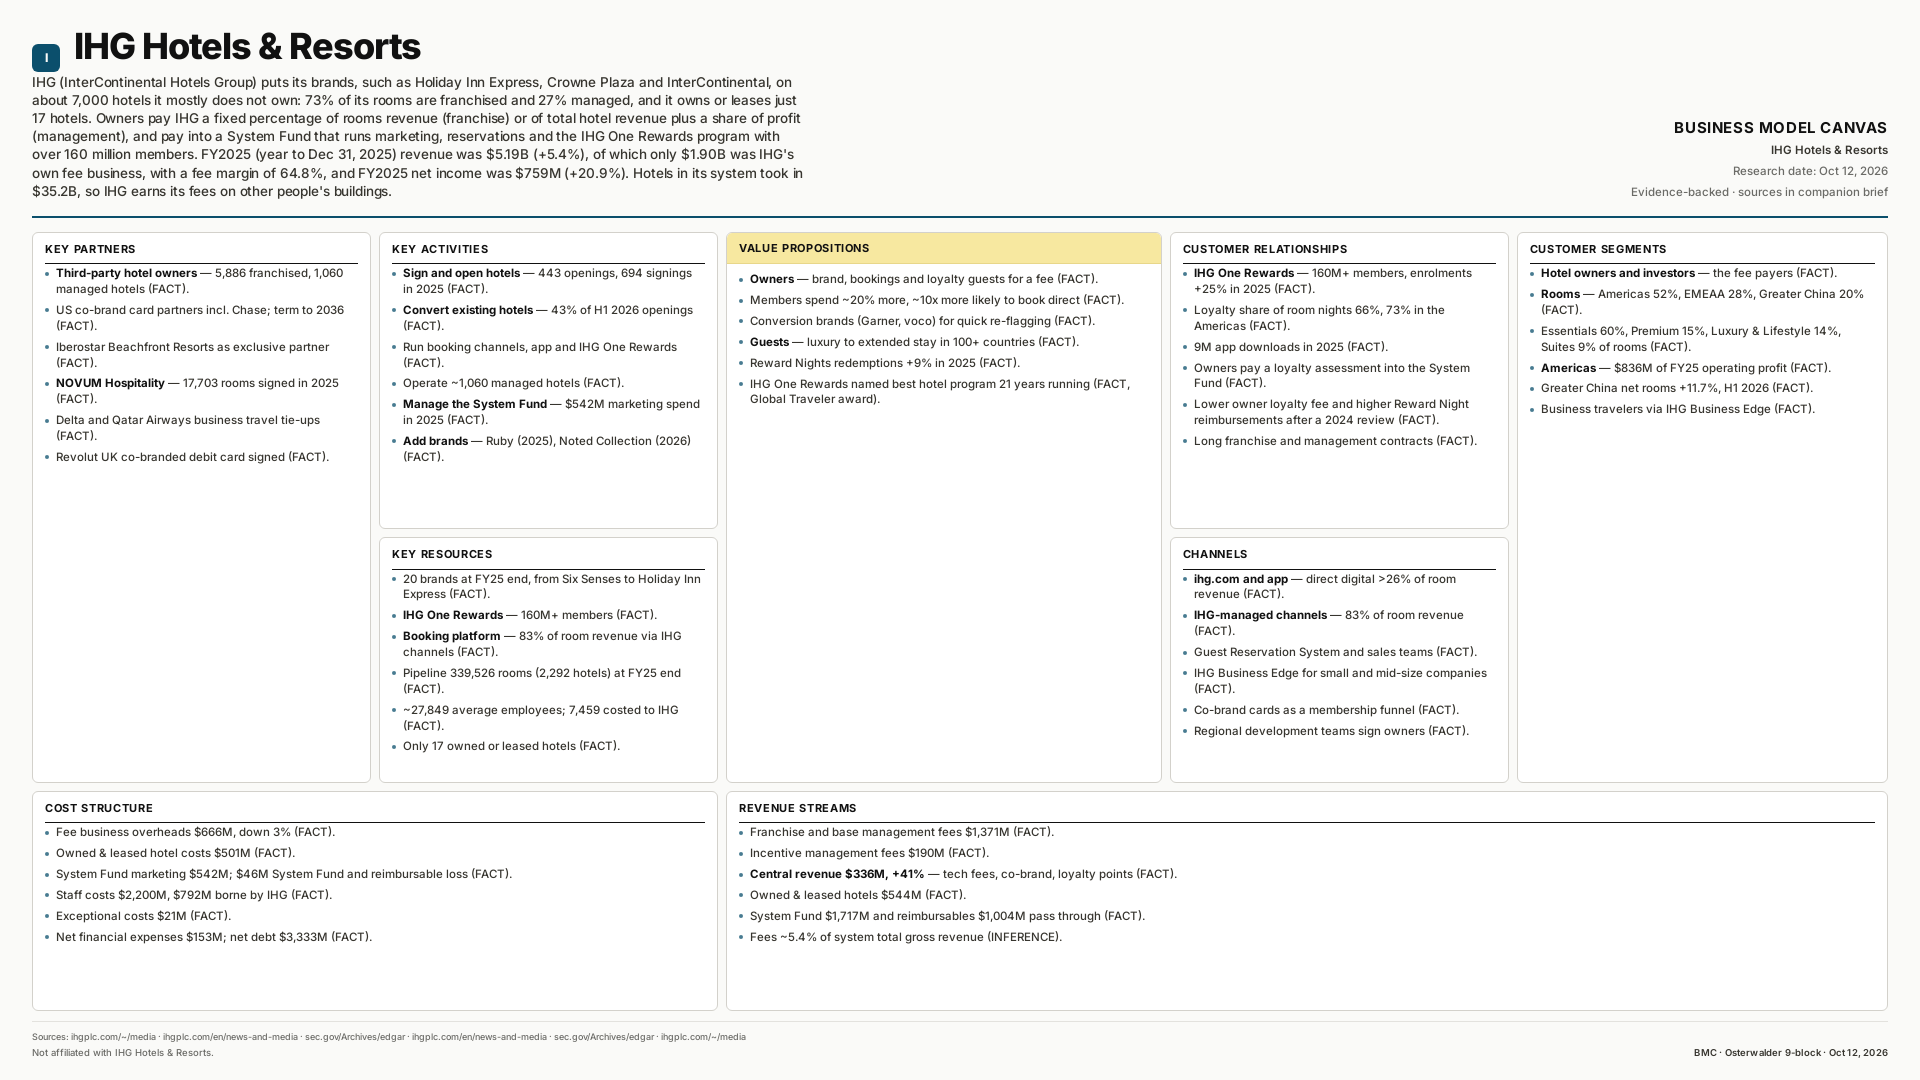

IHG Hotels & Resorts
A hotel brand owner that barely owns hotels: it puts Holiday Inn, Crowne Plaza and 18 other brands on ~7,000 owners' properties for a percentage of their revenue, with IHG One Rewards (160M+ members) as the draw; FY2025 revenue $5.19B (+5.4%), net income $759M.
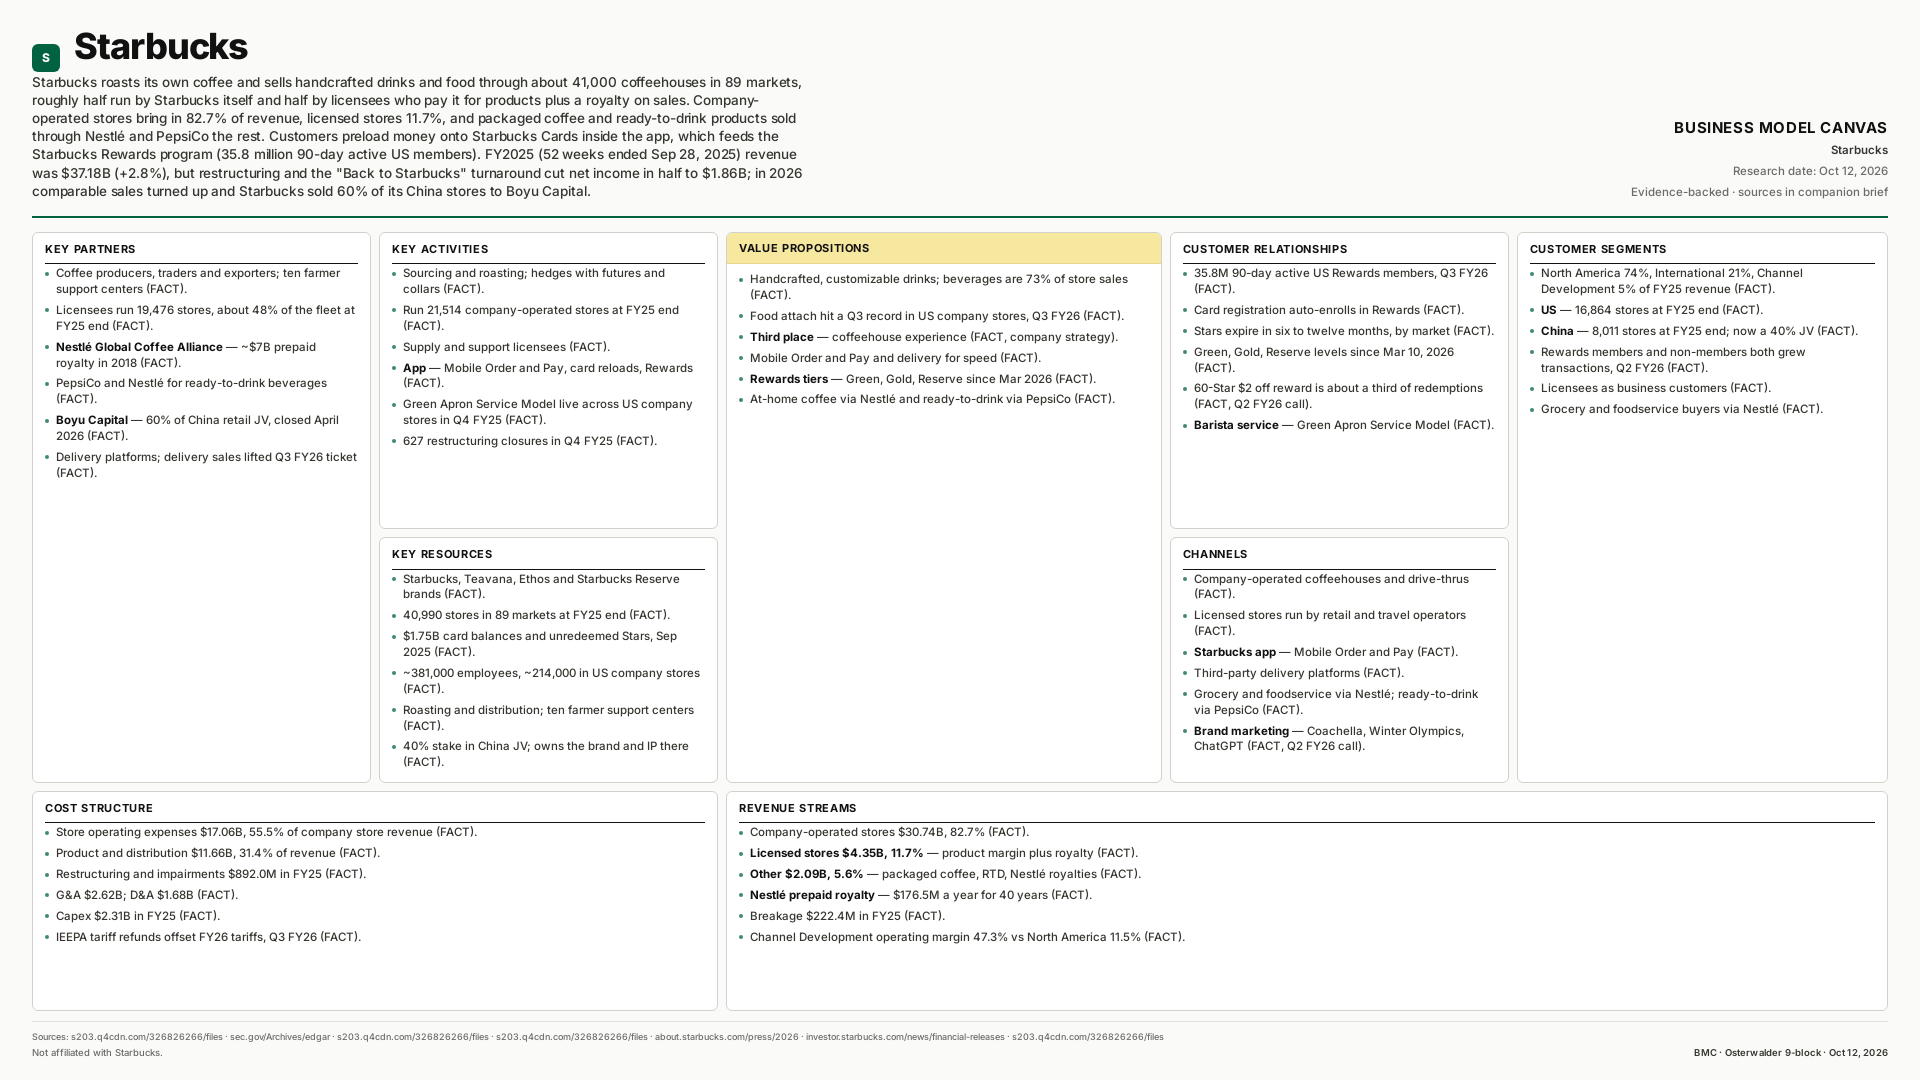

Starbucks
A coffeehouse chain that keeps the full price in its own stores (82.7% of revenue), rents its brand to licensees, Nestlé and a China JV for royalties, and locks in habits with a preloaded card and Rewards app; FY2025 revenue $37.18B (+2.8%), net income $1.86B.
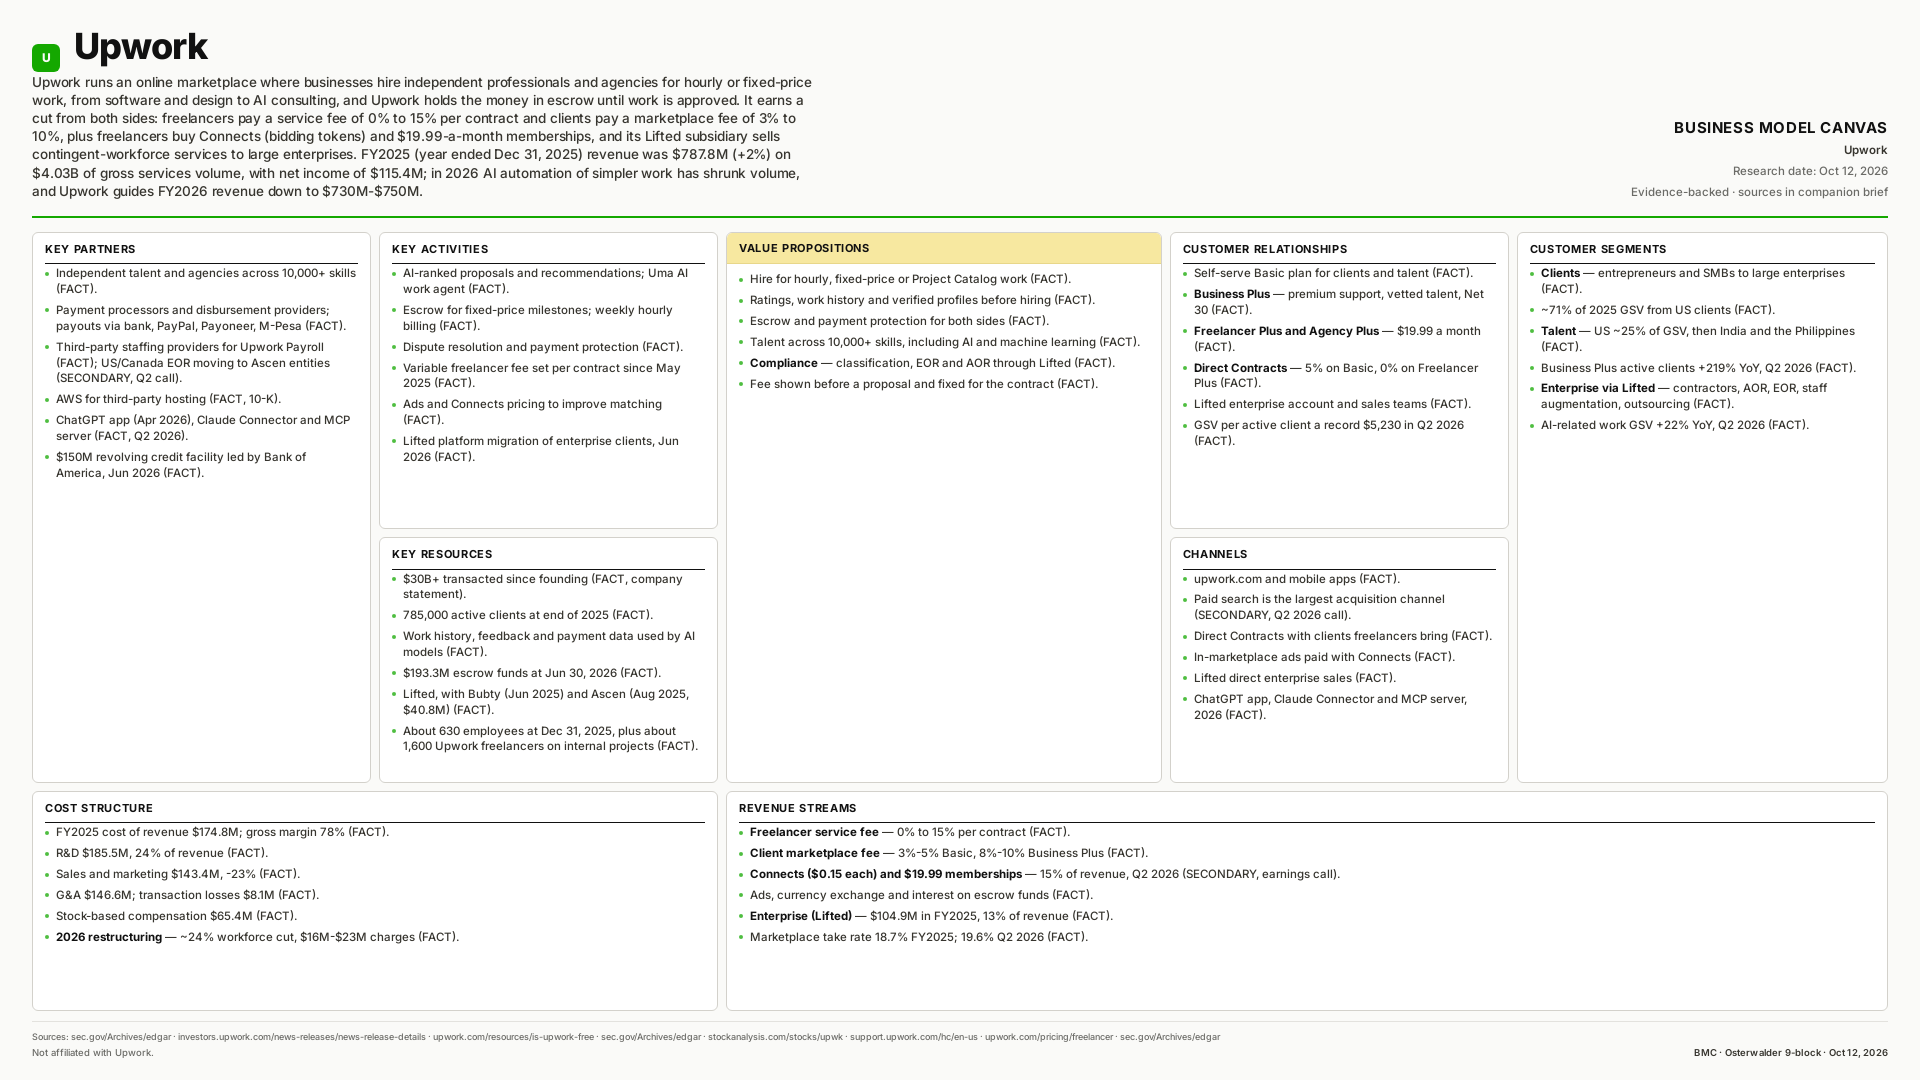

Upwork
A two-sided freelance marketplace that holds client money in escrow and takes 0%-15% from freelancers and 3%-10% from clients on each contract; FY2025 revenue $787.8M (+2%) on $4.03B GSV, net income $115.4M.
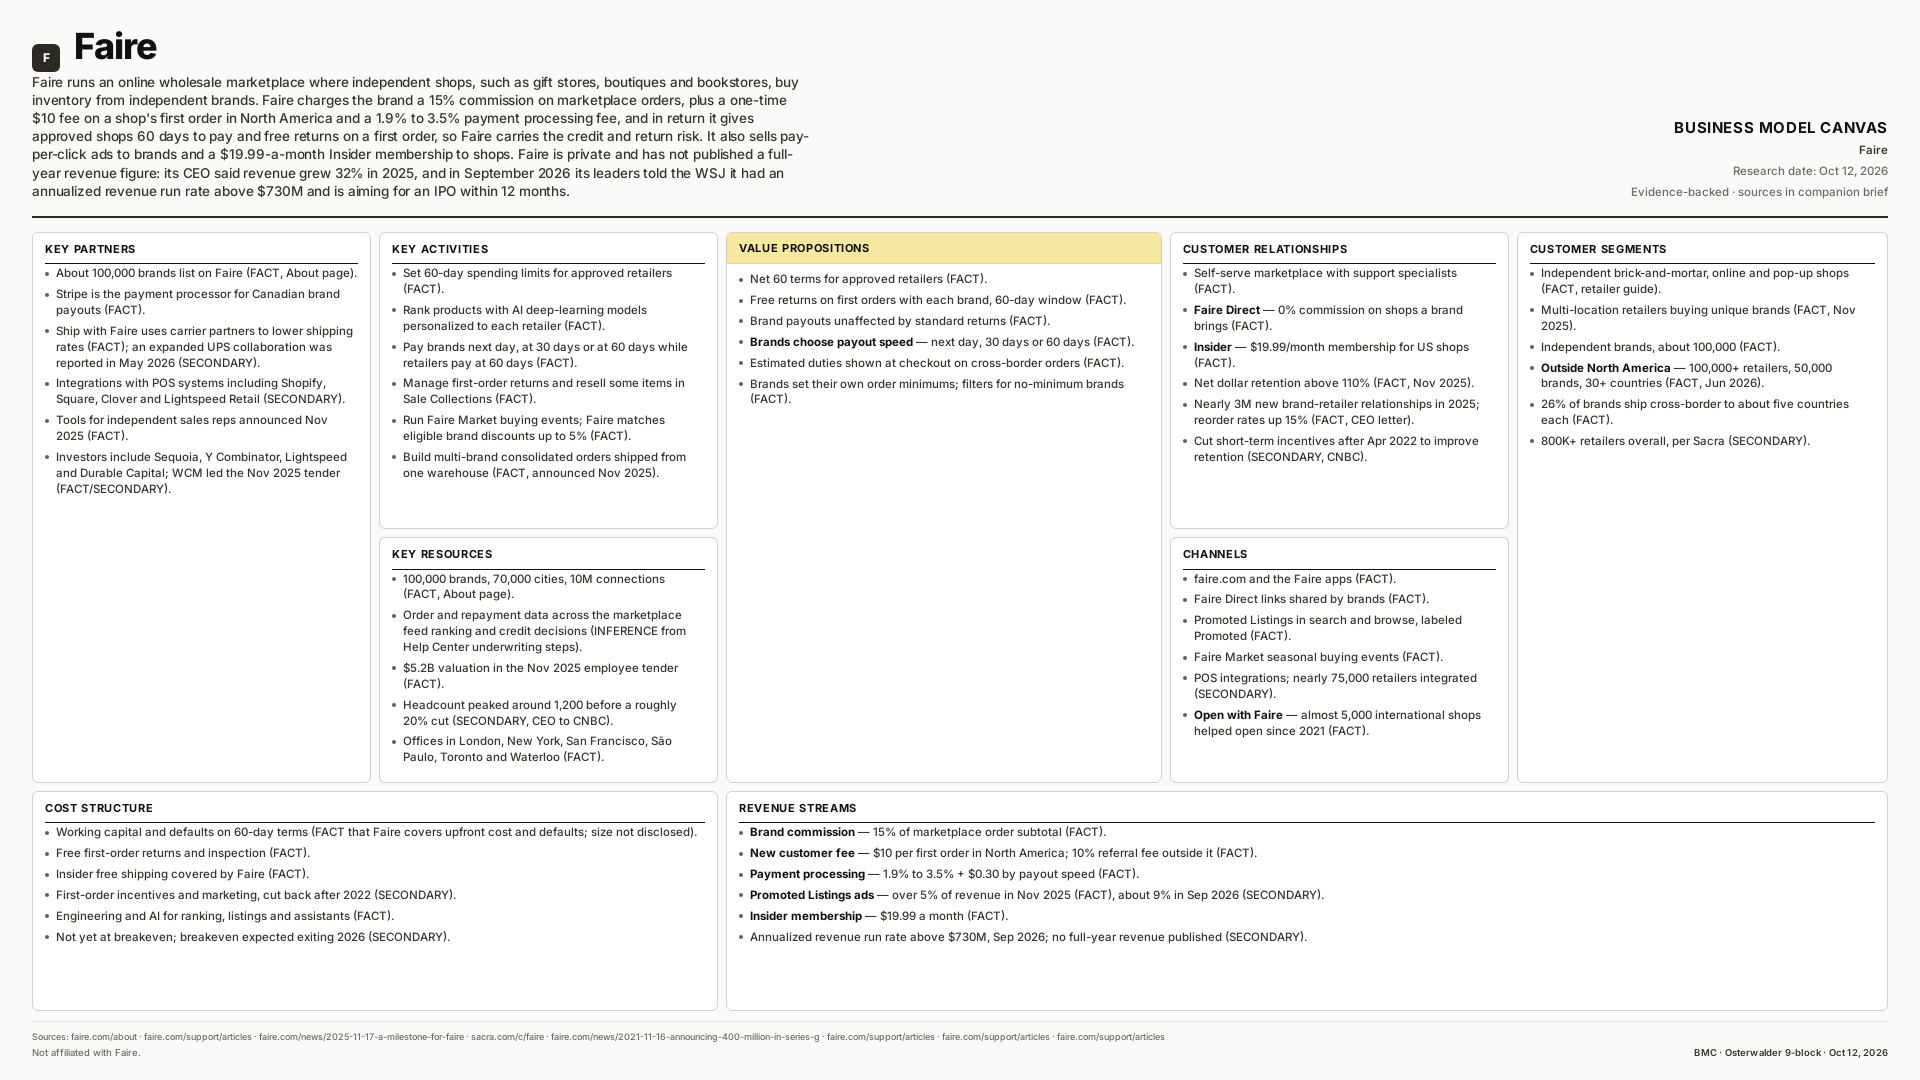

Faire
A wholesale marketplace that pays brands up front, gives independent shops 60 days to pay and free first-order returns, and charges brands a 15% commission; annualized revenue run rate above $730M (Sep 2026), no full-year revenue published.
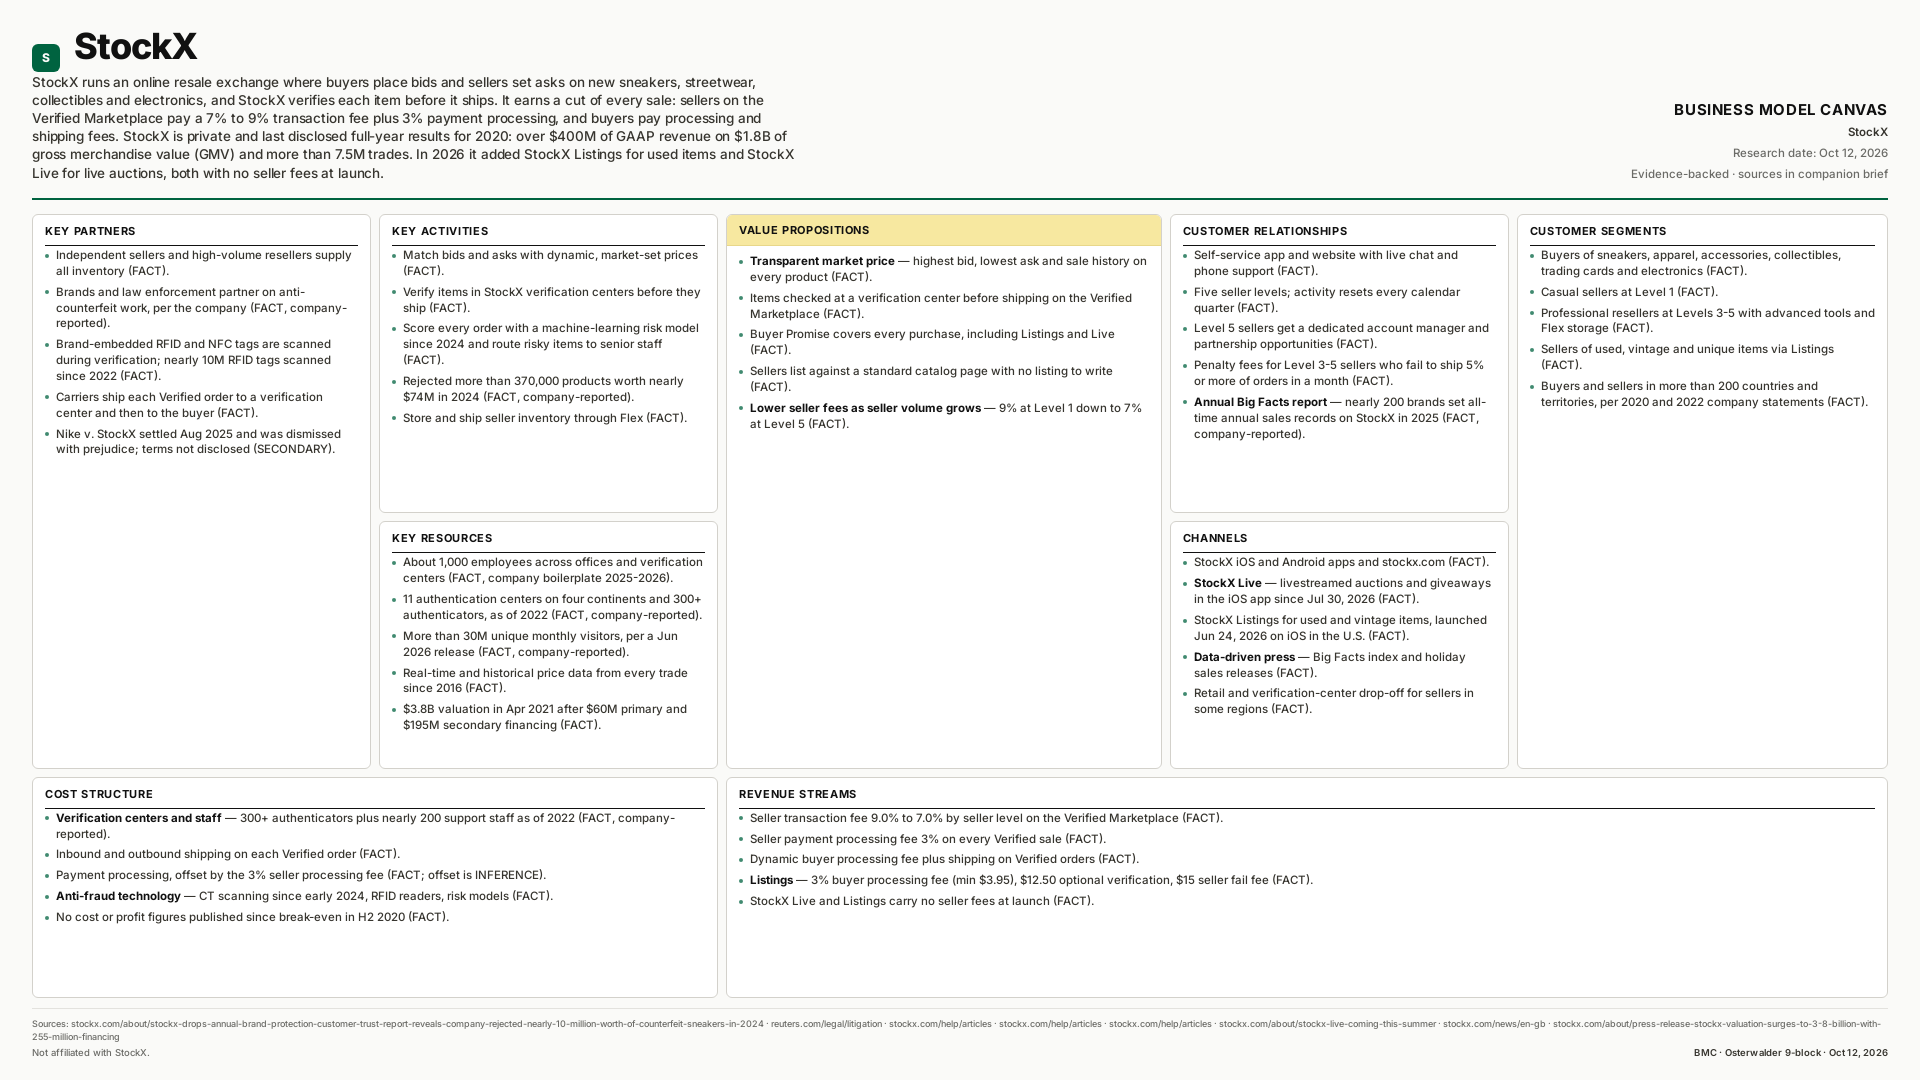

StockX
A bid/ask exchange for sneakers, streetwear and collectibles that verifies items mid-trade and takes a fee from both sides; last disclosed FY2020 revenue over $400M on $1.8B GMV.
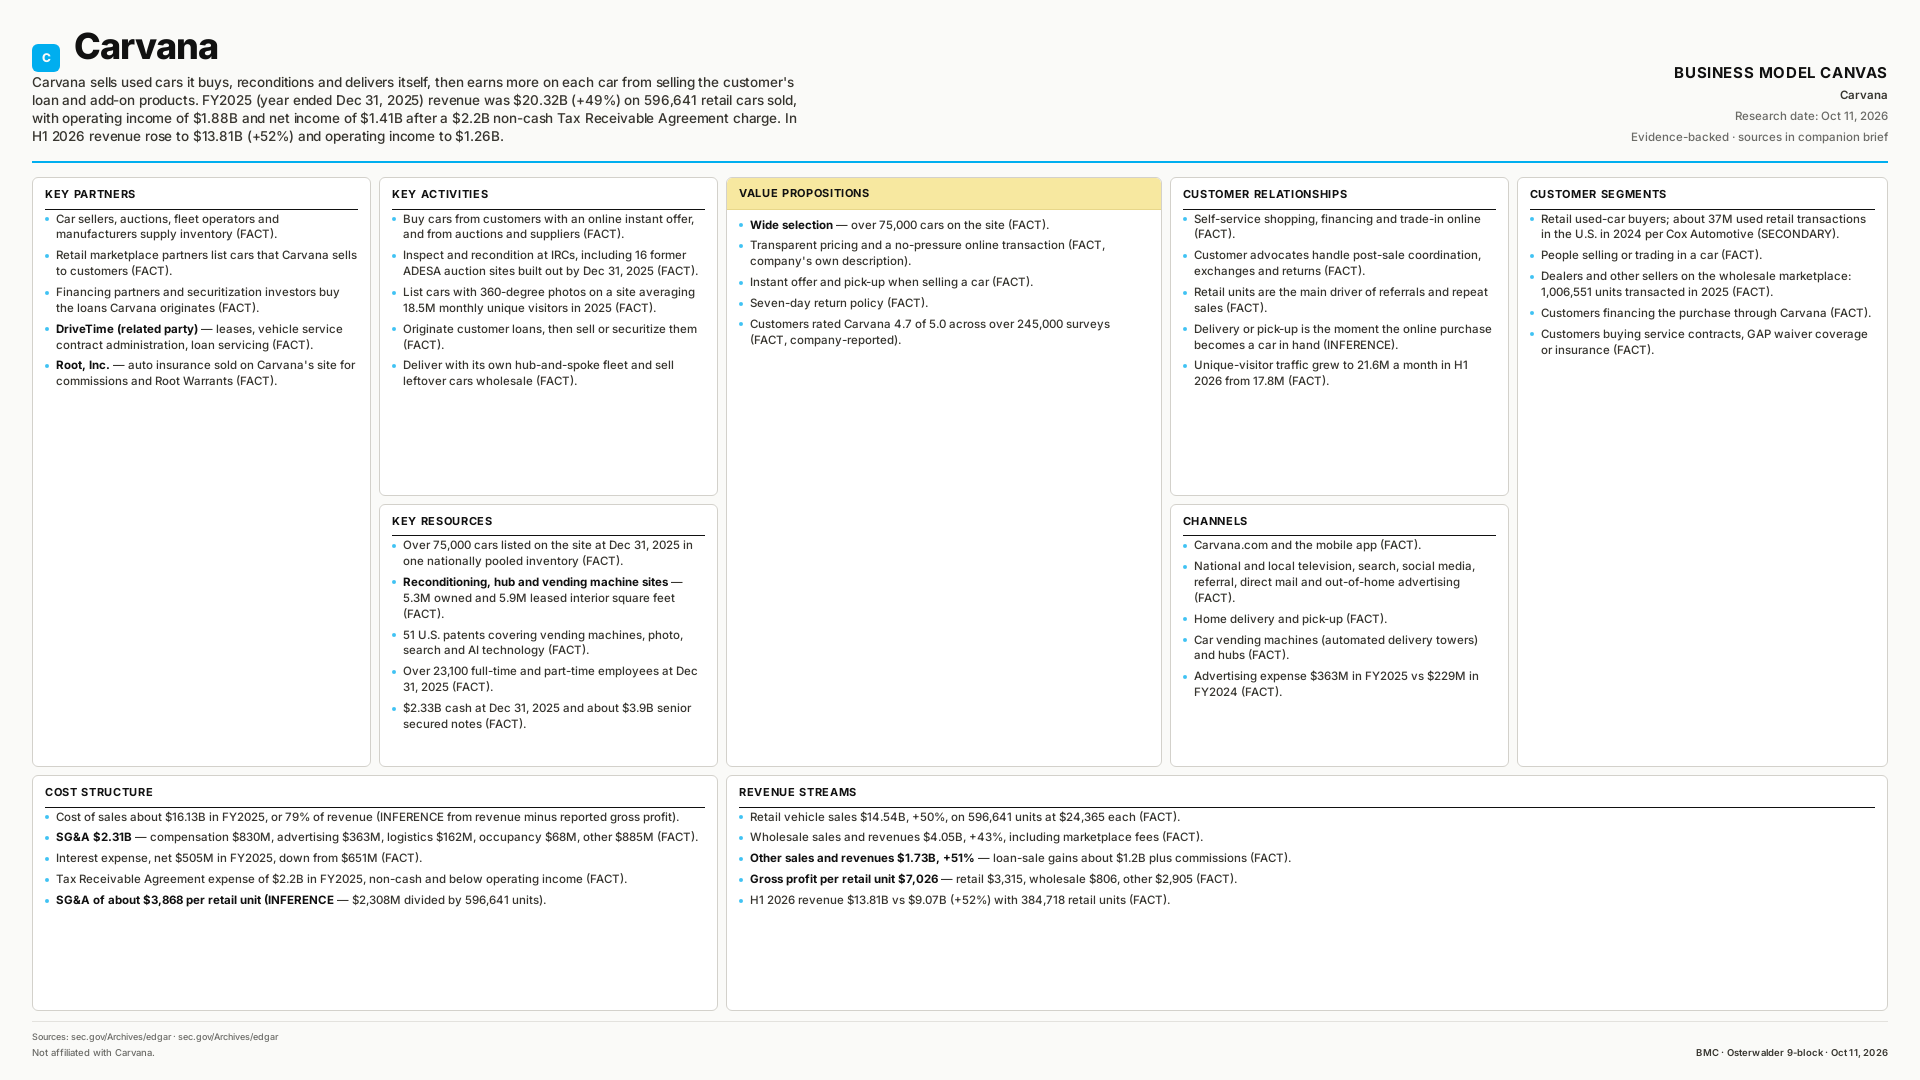

Carvana
Buys, reconditions and delivers used cars itself, then earns more per car on loan sales and add-ons: FY25 revenue $20.32B (+49%), operating income $1.88B.
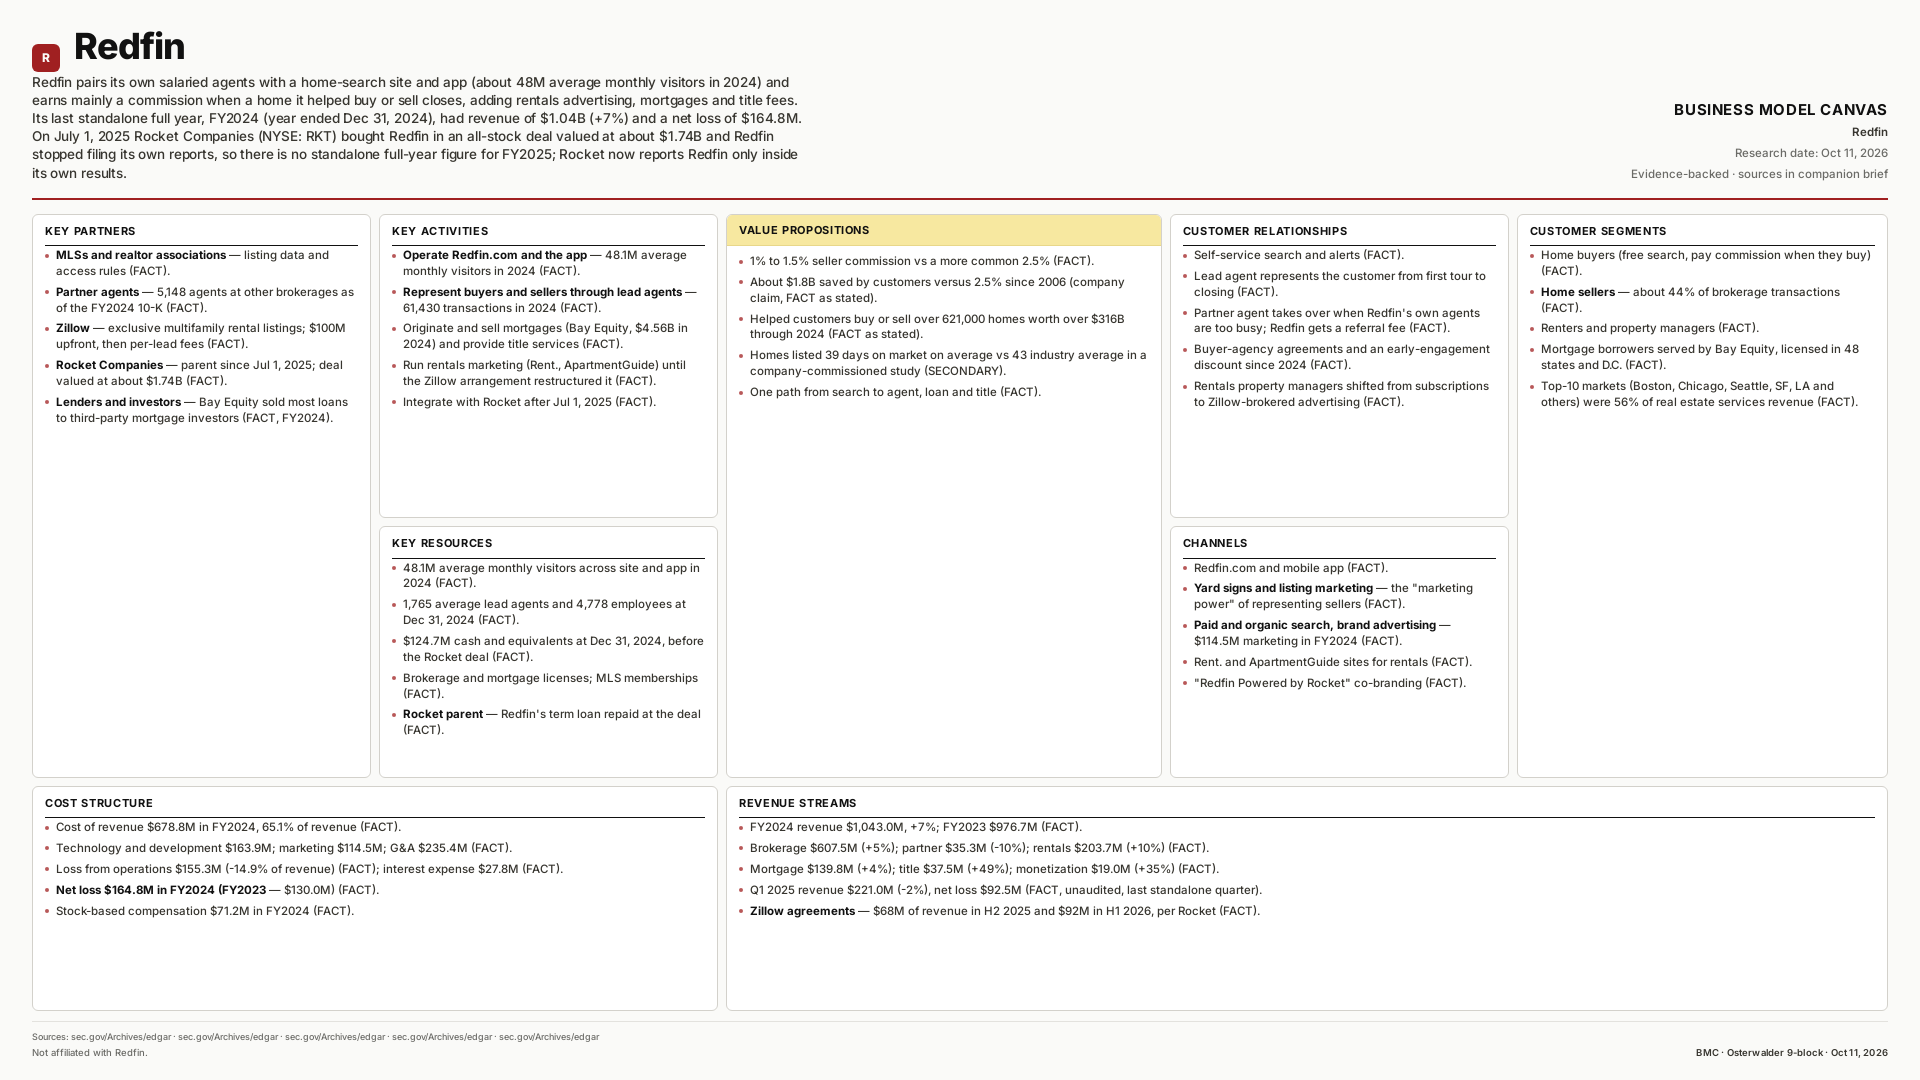

Redfin
Pays its own agents to undercut commissions, and lost money doing it: FY24 revenue $1.04B (+7%), net loss $164.8M, then sold to Rocket Companies in 2025.
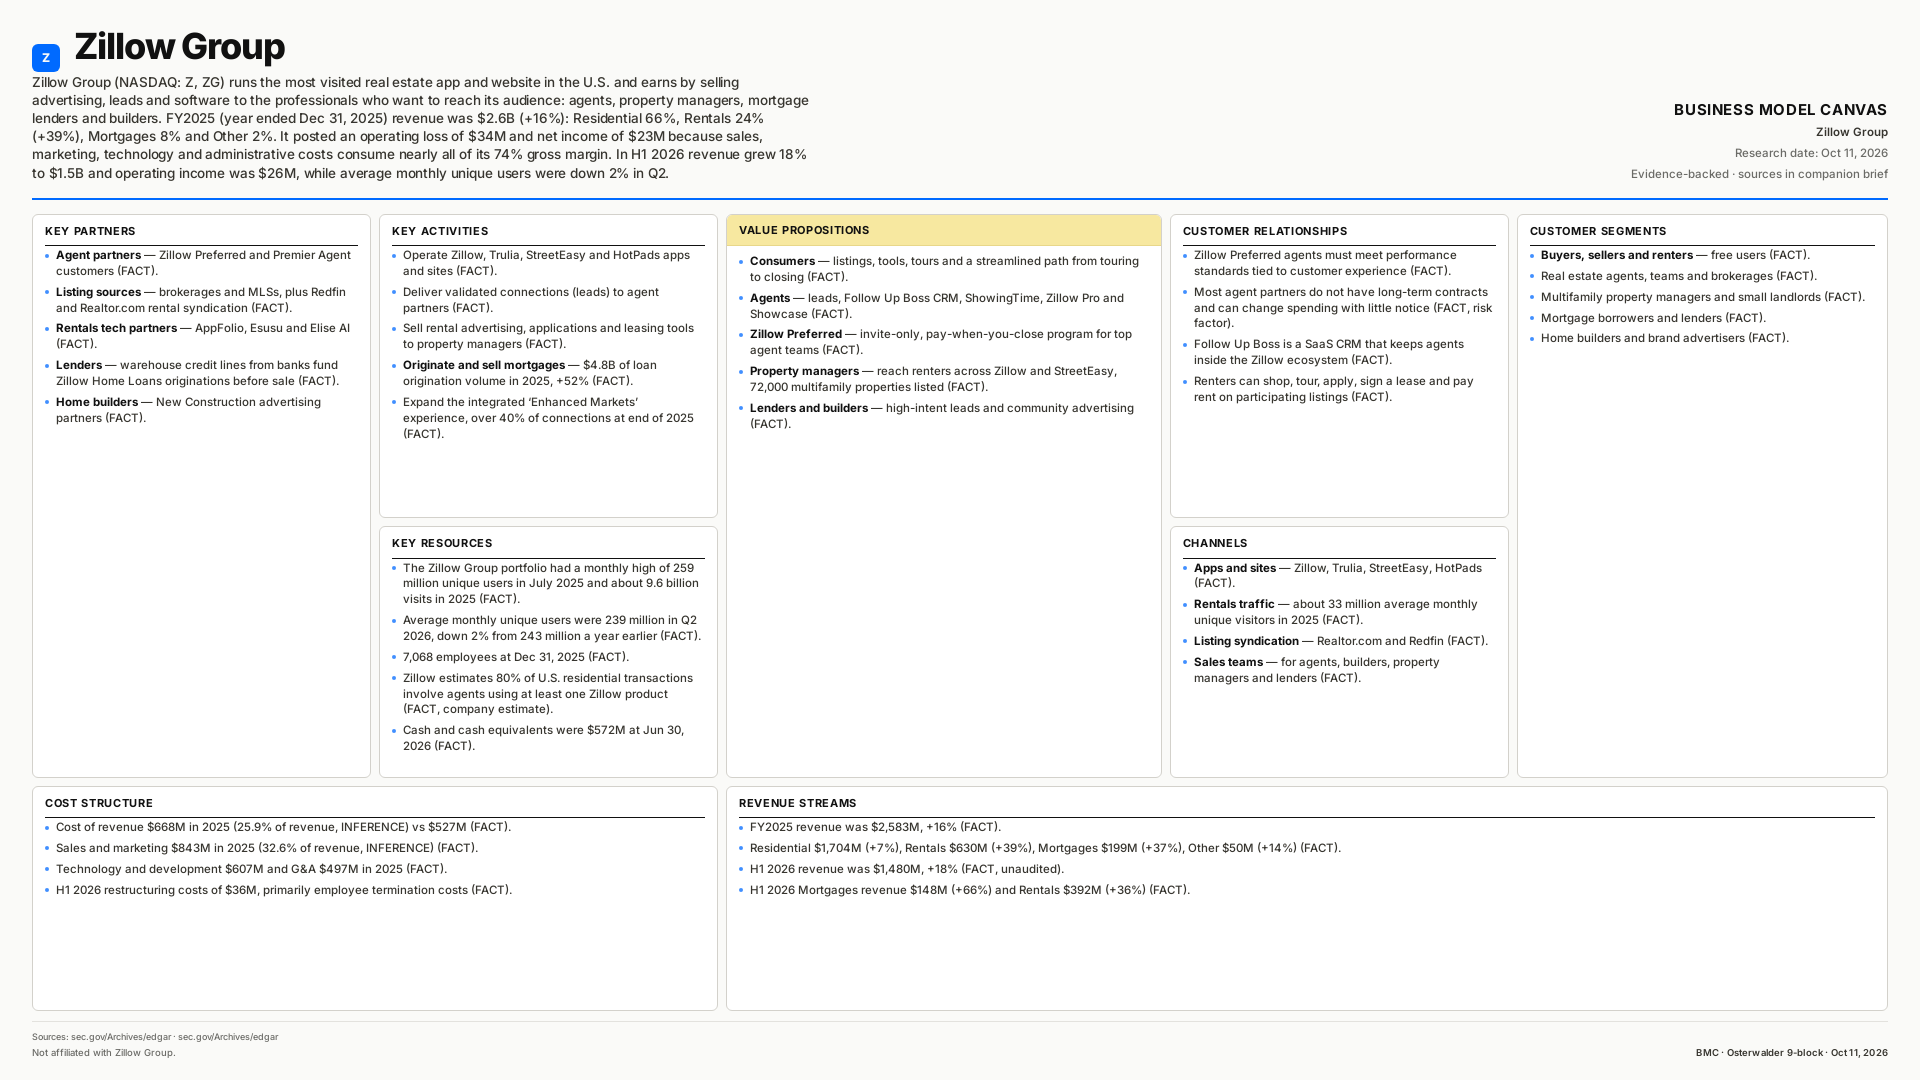

Zillow Group
Wins the home-search audience, then rents it out: sells leads, rental ads and software to agents and landlords, increasingly paid only at close: FY25 revenue $2.6B (+16%), but only $23M net income.
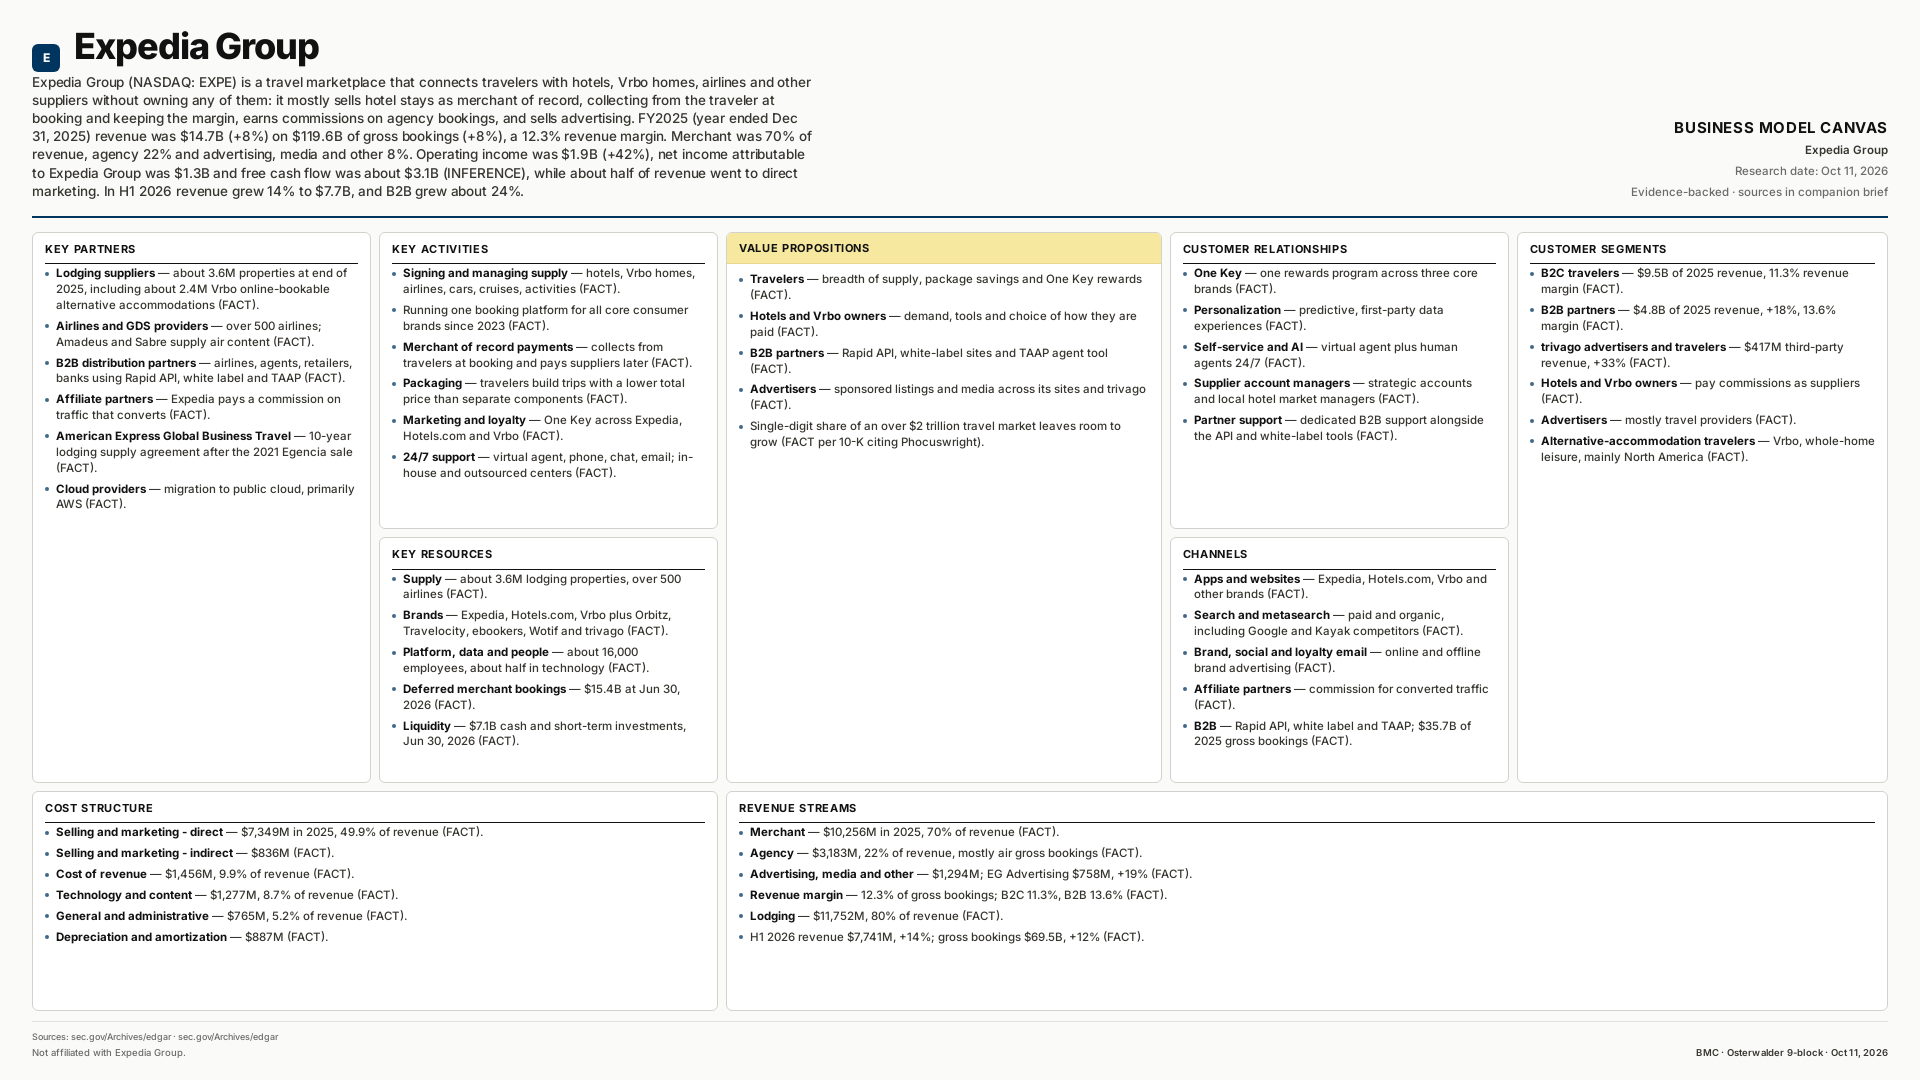

Expedia Group
Owns no rooms or planes: sells hotel stays as merchant of record, keeps about 12 cents of each booked dollar, and spends about half of revenue on traffic and partner commissions: FY25 revenue $14.7B (+8%).
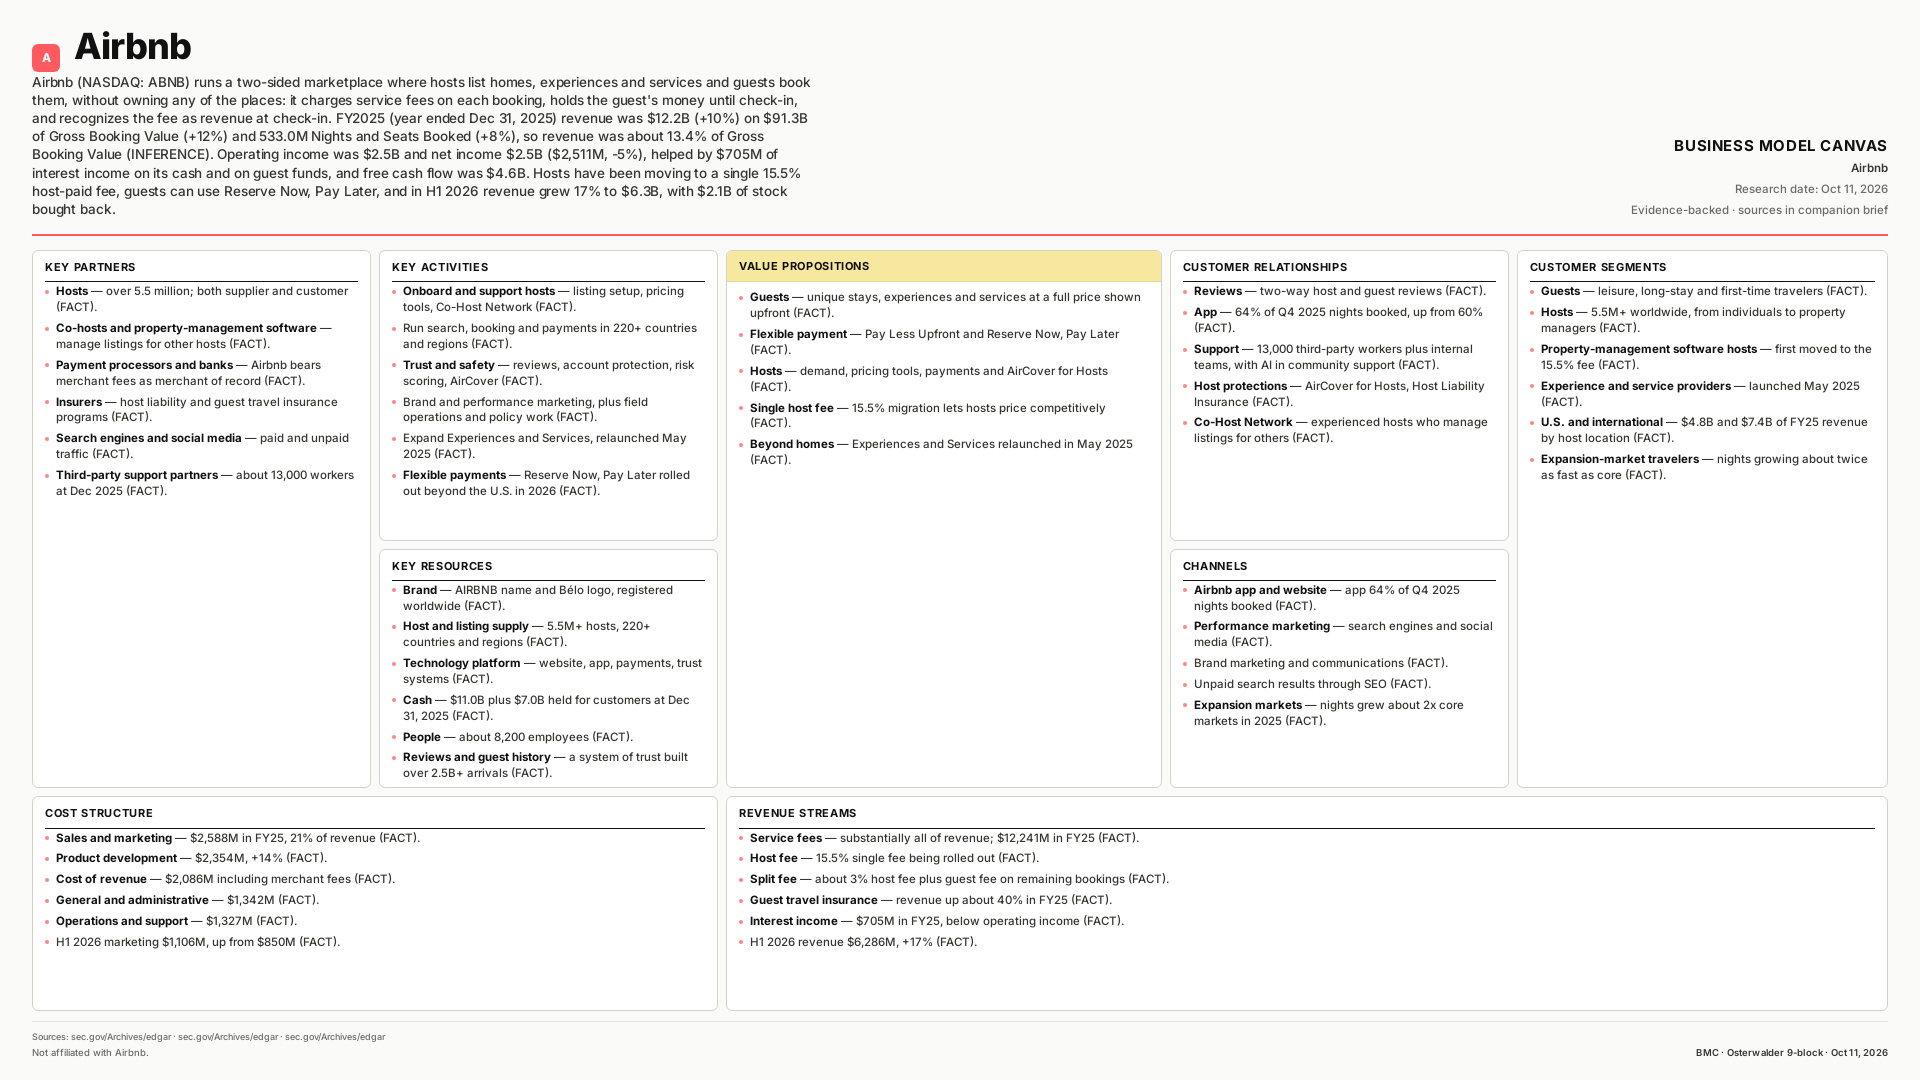

Airbnb
Owns no property: hosts list homes, experiences and services, Airbnb holds the guest's money until check-in and takes a service fee, now mostly a 15.5% host-paid fee, about 13% of booked value: FY25 revenue $12.2B (+10%).
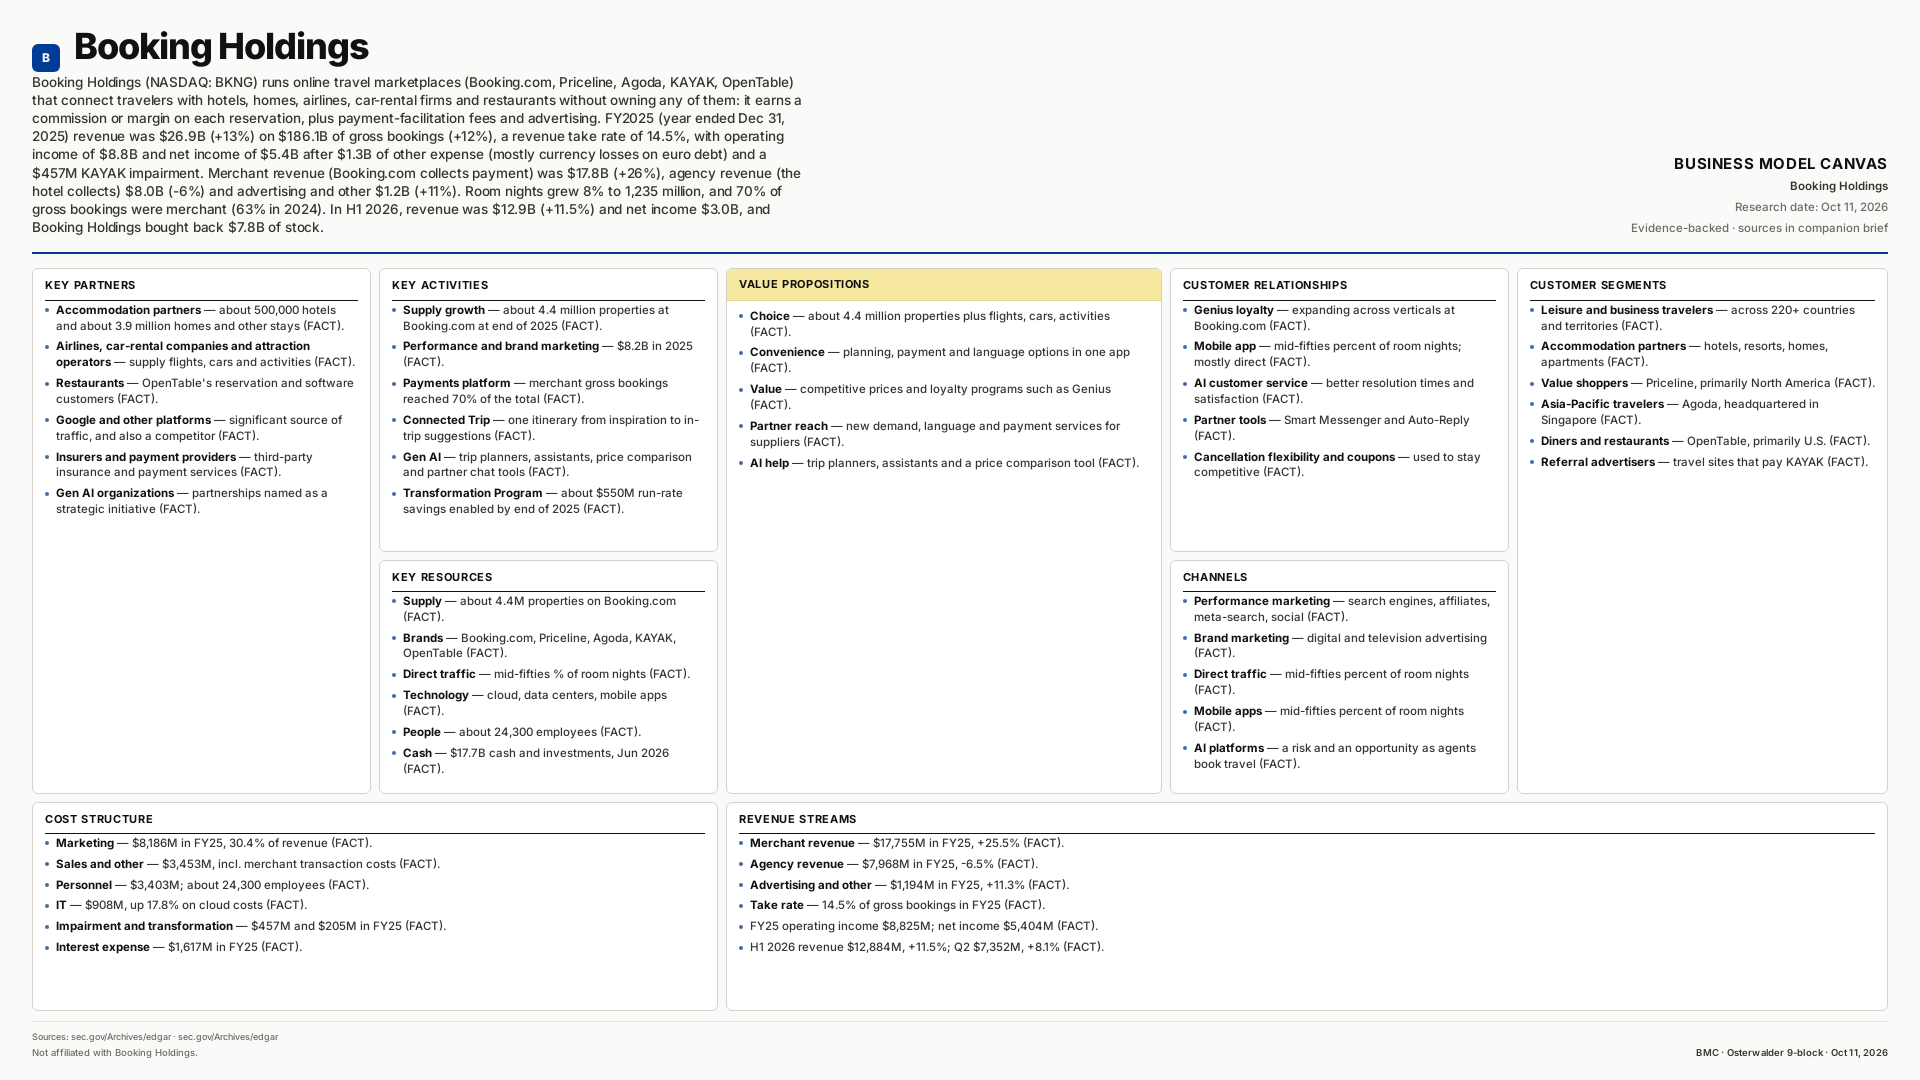

Booking Holdings
Owns no rooms: lists millions of properties, takes about 14.5% of every booked dollar as commission, margin and payment fees, and earns more as bookings shift to Booking-collects payments: FY25 revenue $26.9B (+13%).
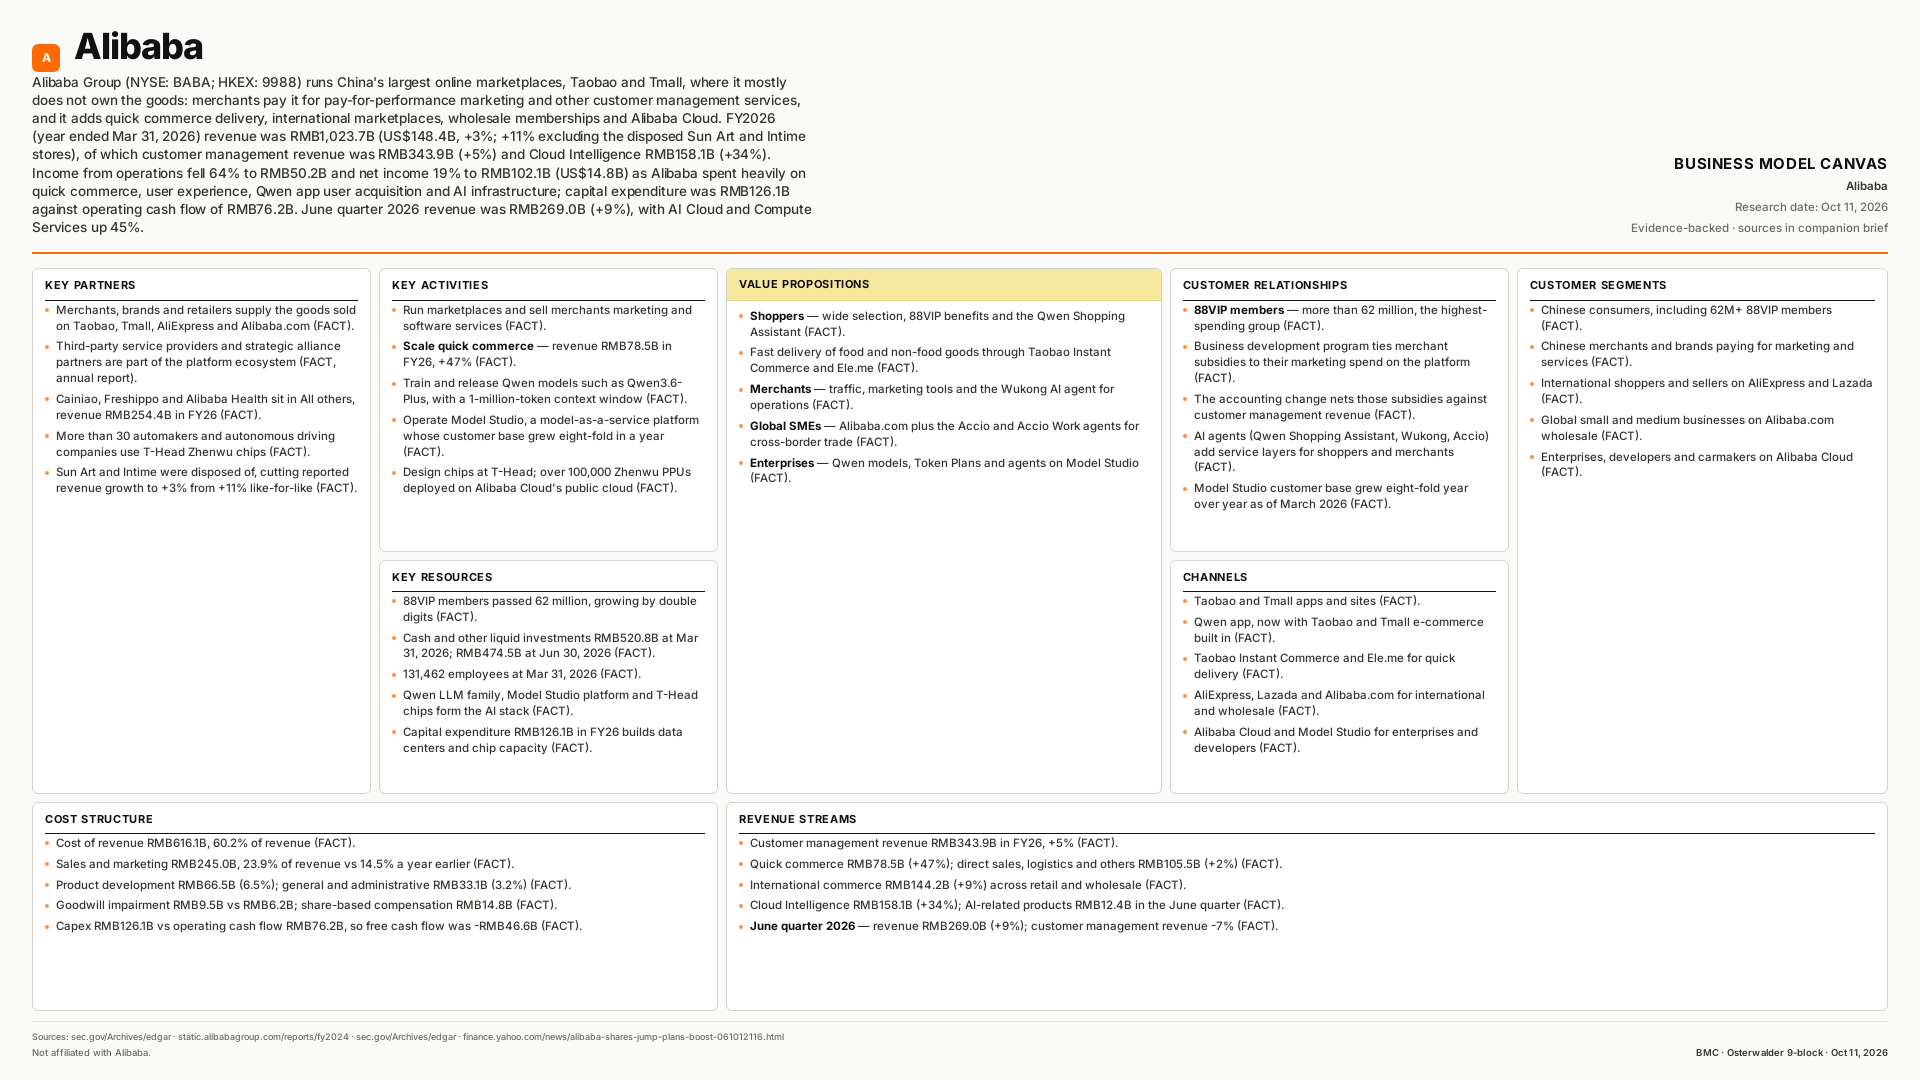

Alibaba
Runs China's biggest marketplaces and earns mainly from merchant marketing (customer management revenue RMB343.9B), then spends on quick commerce and AI: FY26 revenue RMB1,023.7B (+3%).
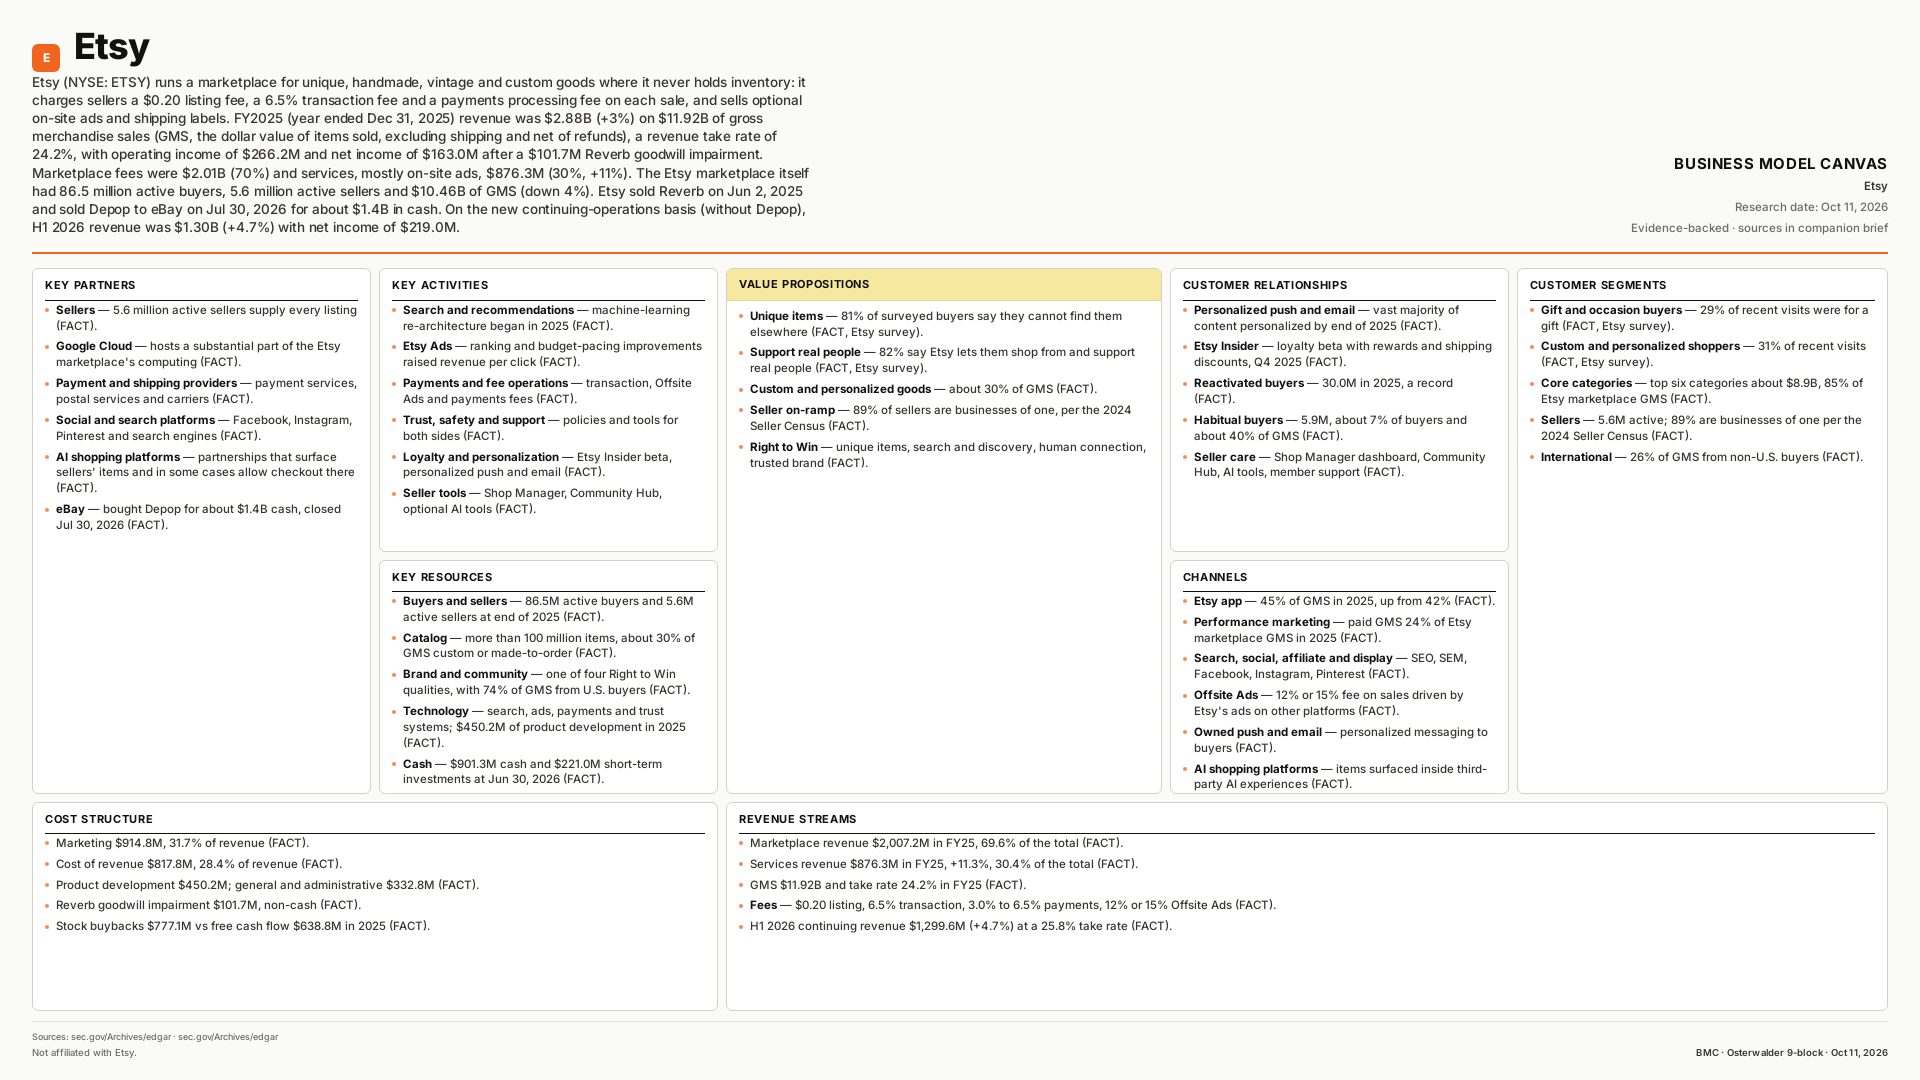

Etsy
Hosts independent sellers of handmade and unique goods without owning inventory, and earns a 24.2% take rate through listing, transaction, payments and ad fees: FY25 revenue $2.88B (+3%).
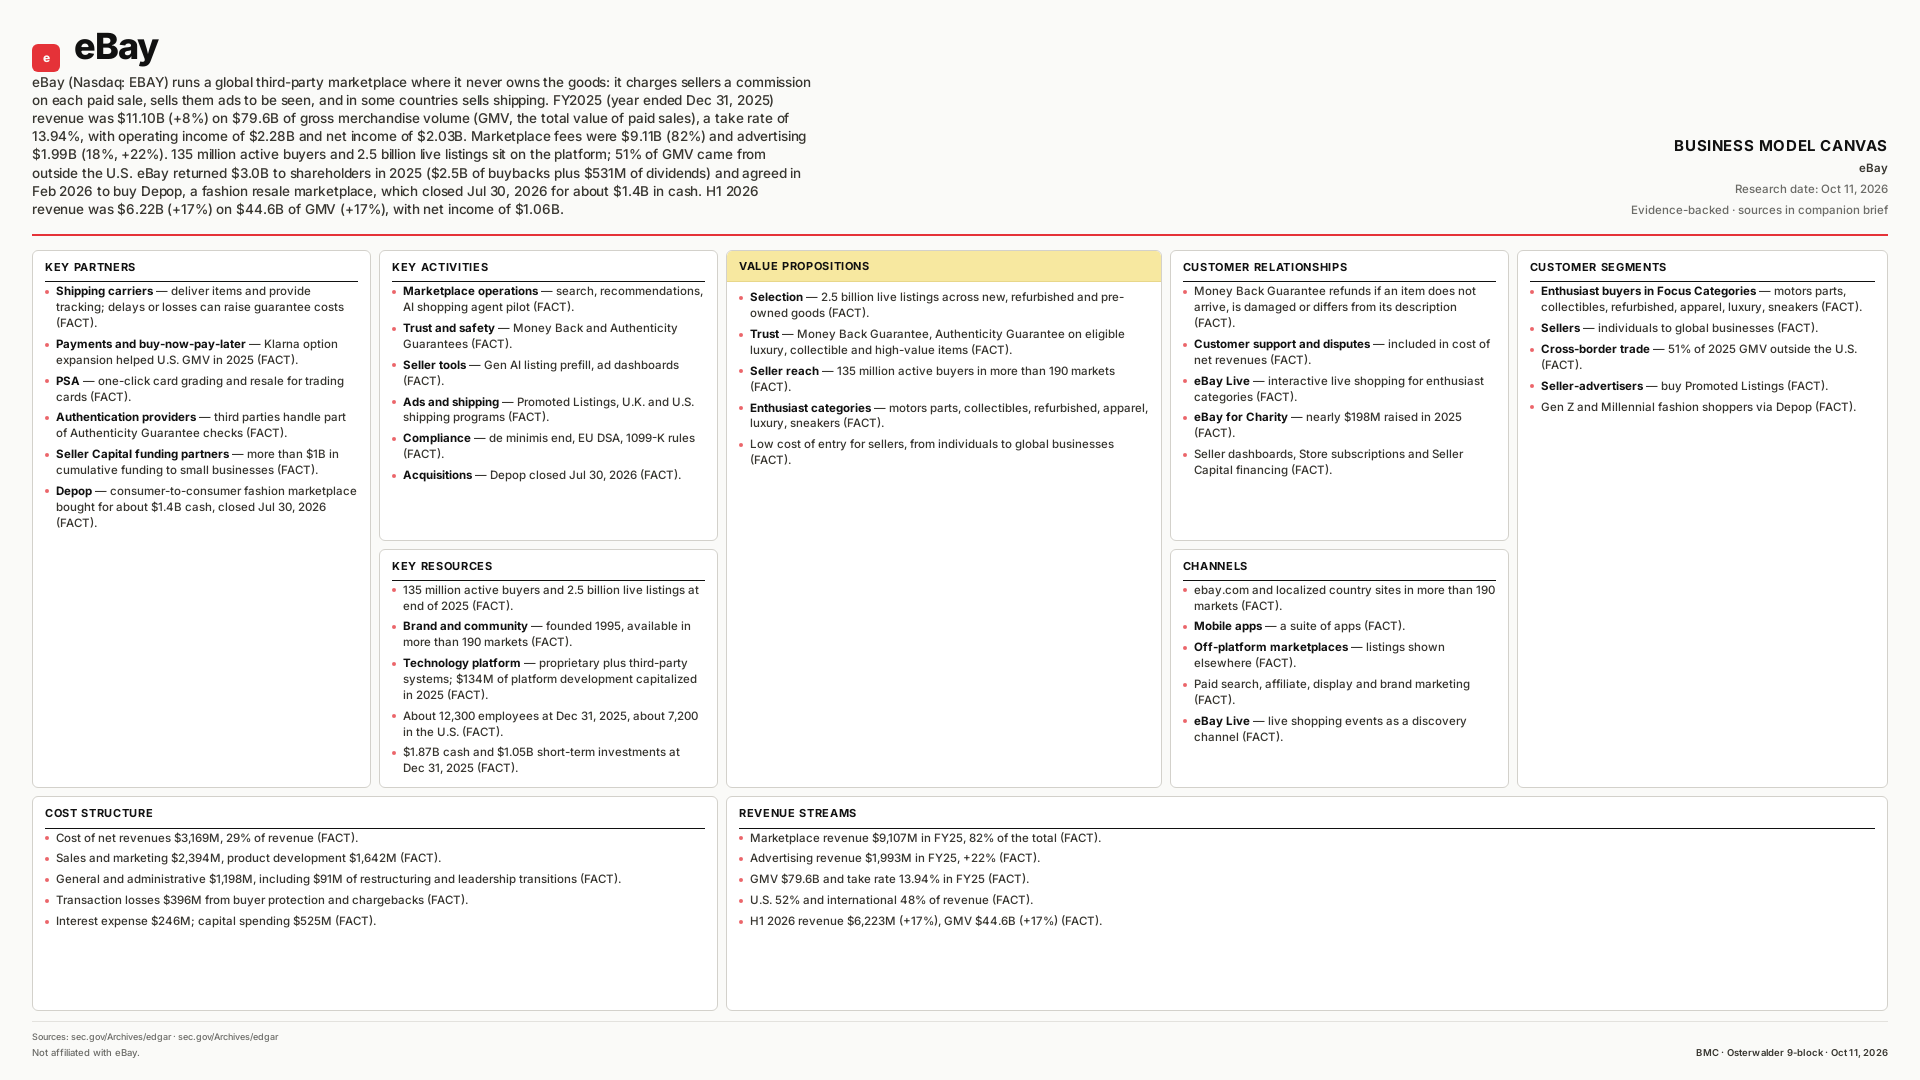

eBay
Hosts buyers and sellers without owning the goods, takes about 14 cents of every sales dollar as fees plus Promoted Listings ads: FY25 revenue $11.10B (+8%).
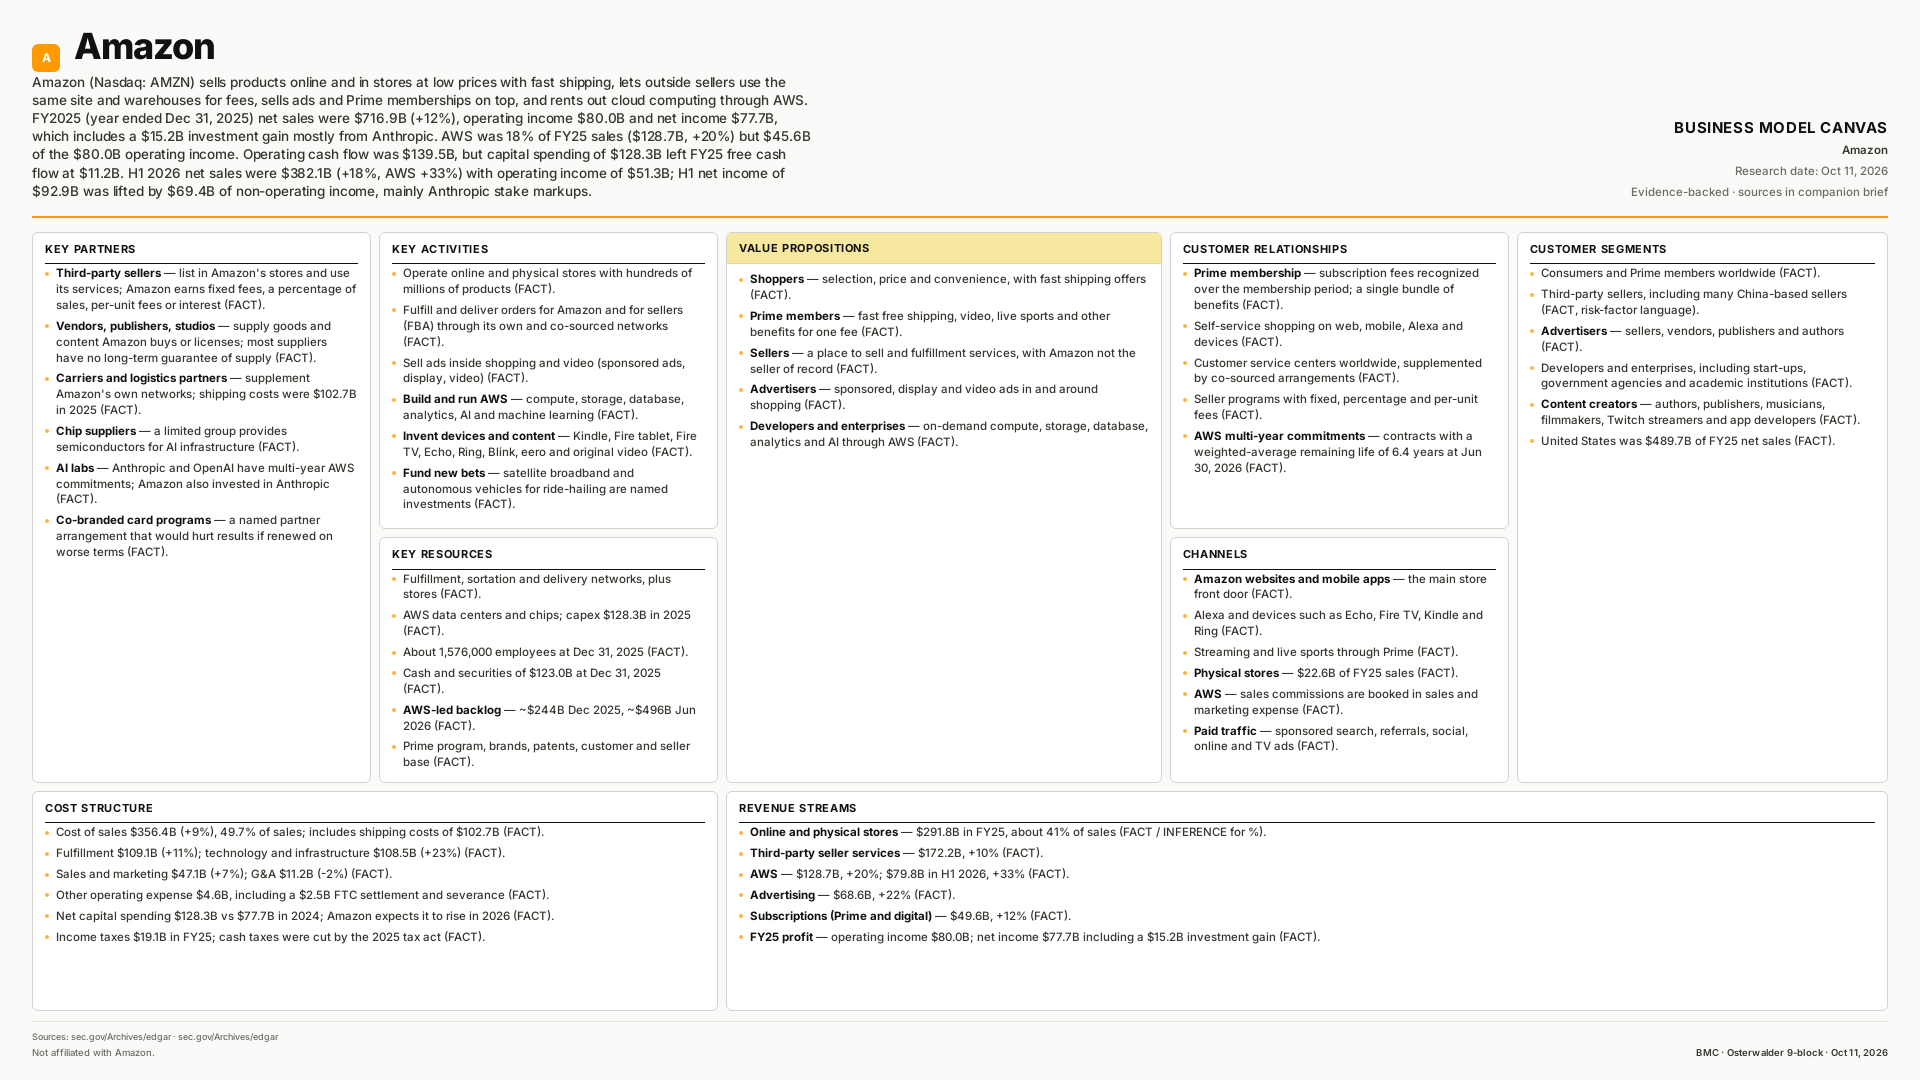

Amazon
Sells goods at low prices with fast shipping, charges outside sellers and advertisers to use the same shelves, and rents out AWS cloud, which earns most of the profit: FY25 net sales $716.9B (+12%).
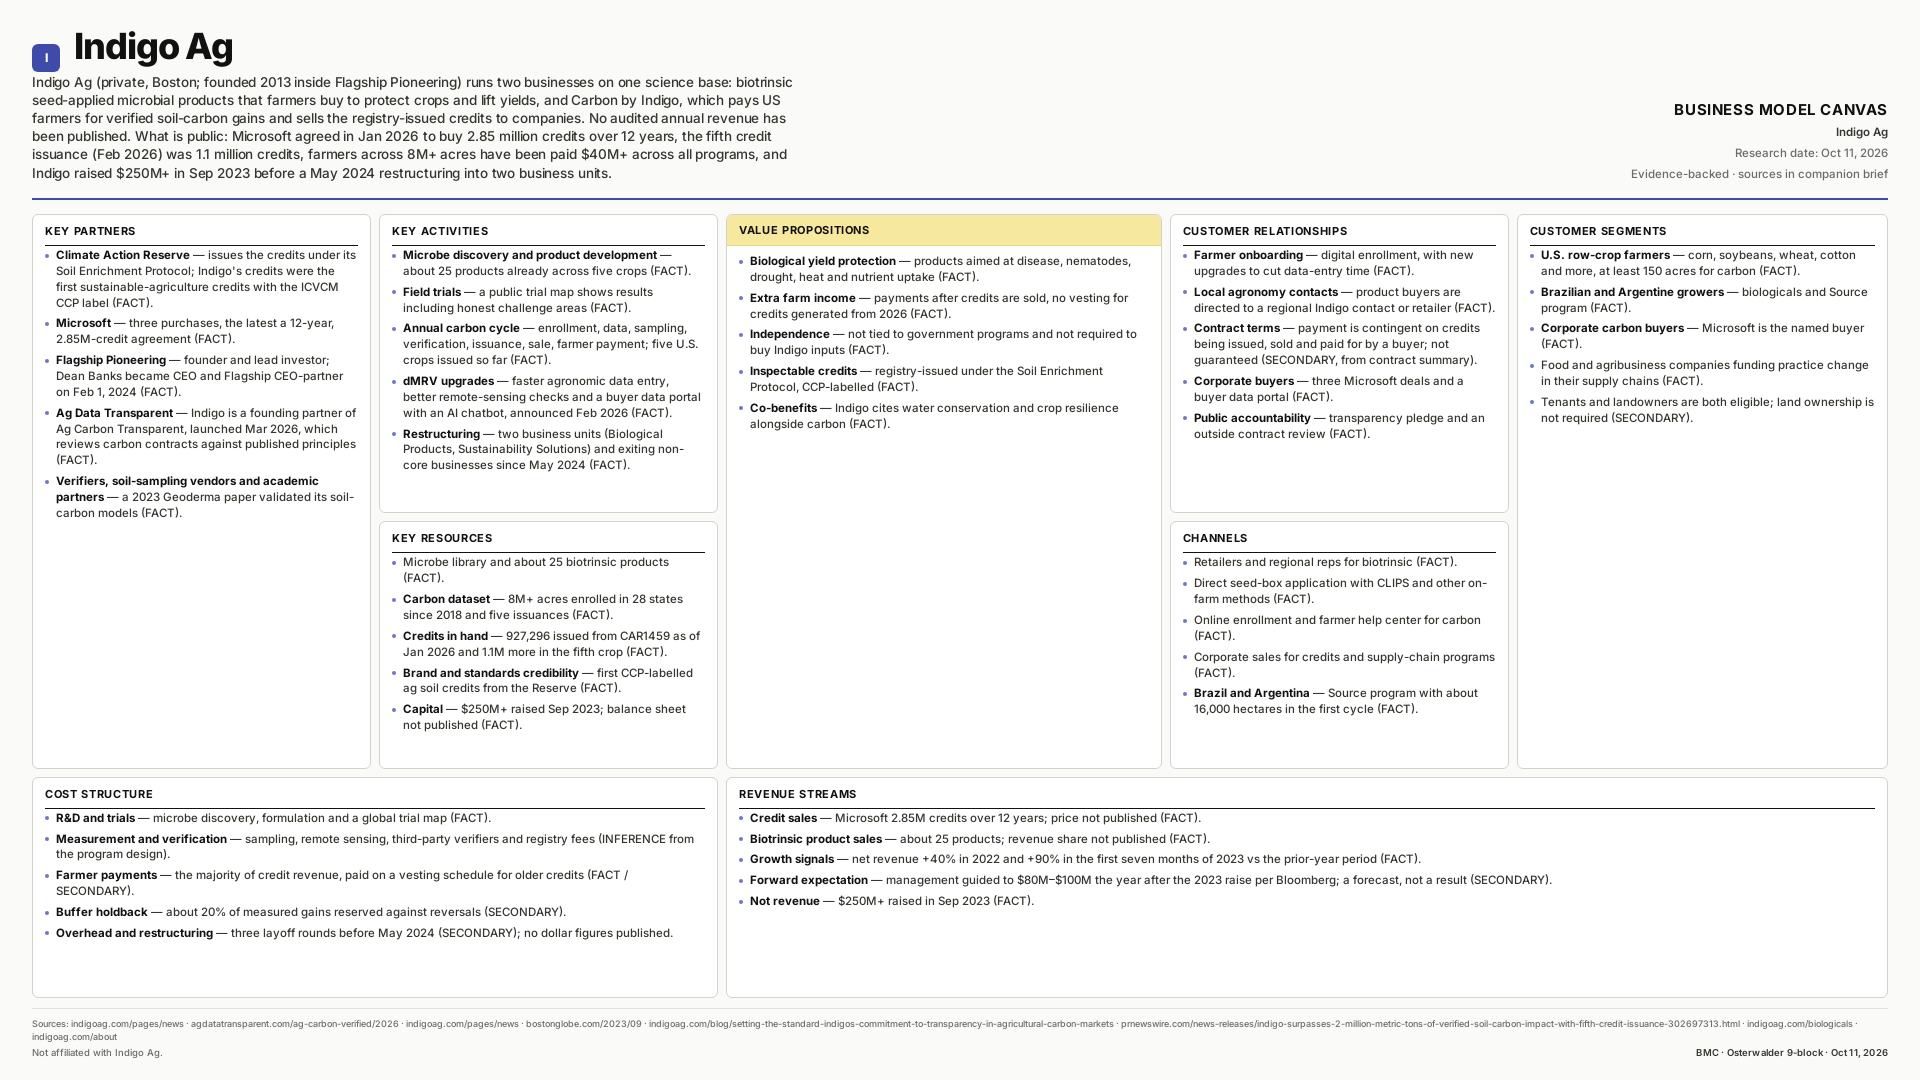

Indigo Ag
Sells crop-protecting microbes to farmers and pays farmers for verified soil-carbon gains, then sells the registry-issued credits to companies like Microsoft (2.85M credits over 12 years); no audited annual revenue is published.
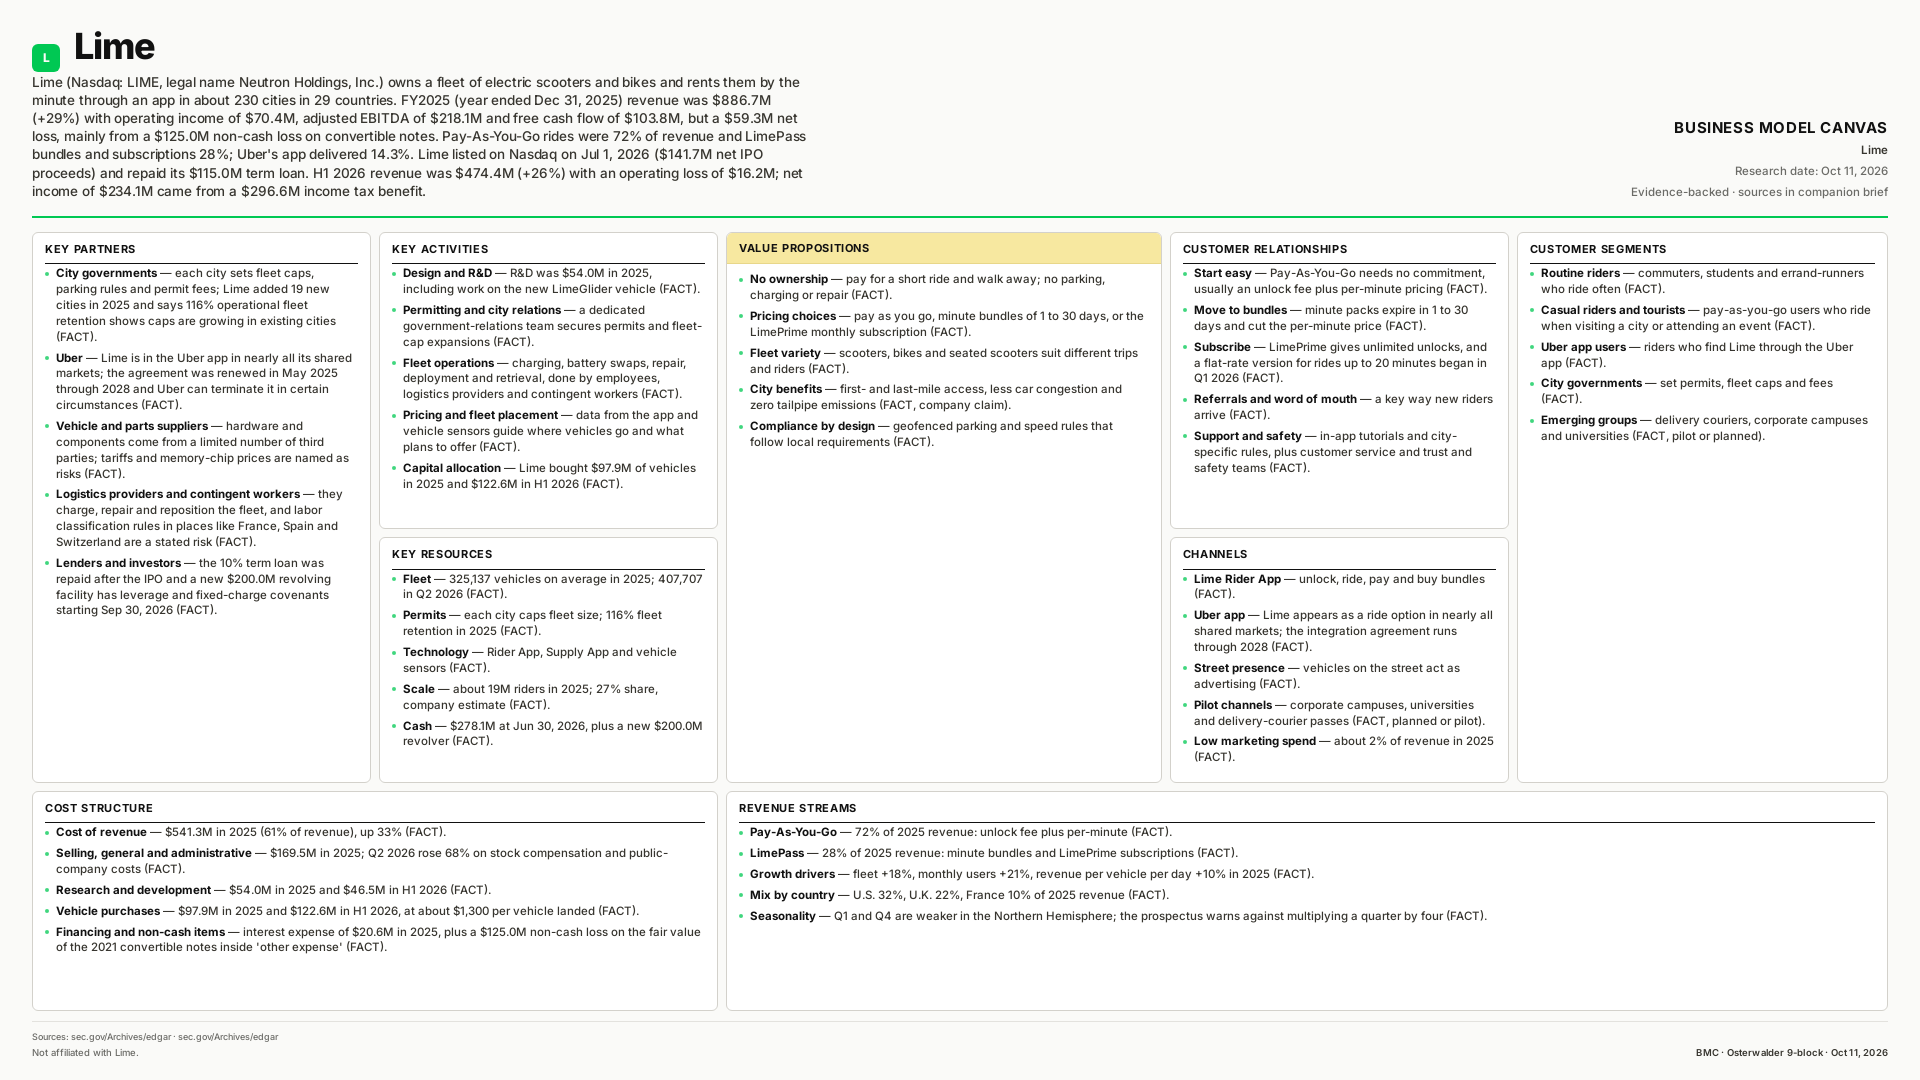

Lime
Rents electric scooters and bikes by the minute in about 230 cities, adds bundles, a subscription and the Uber app as channels, and earned $70.4M operating income on $886.7M FY2025 revenue before convertible-note losses took it to a $59.3M net loss.
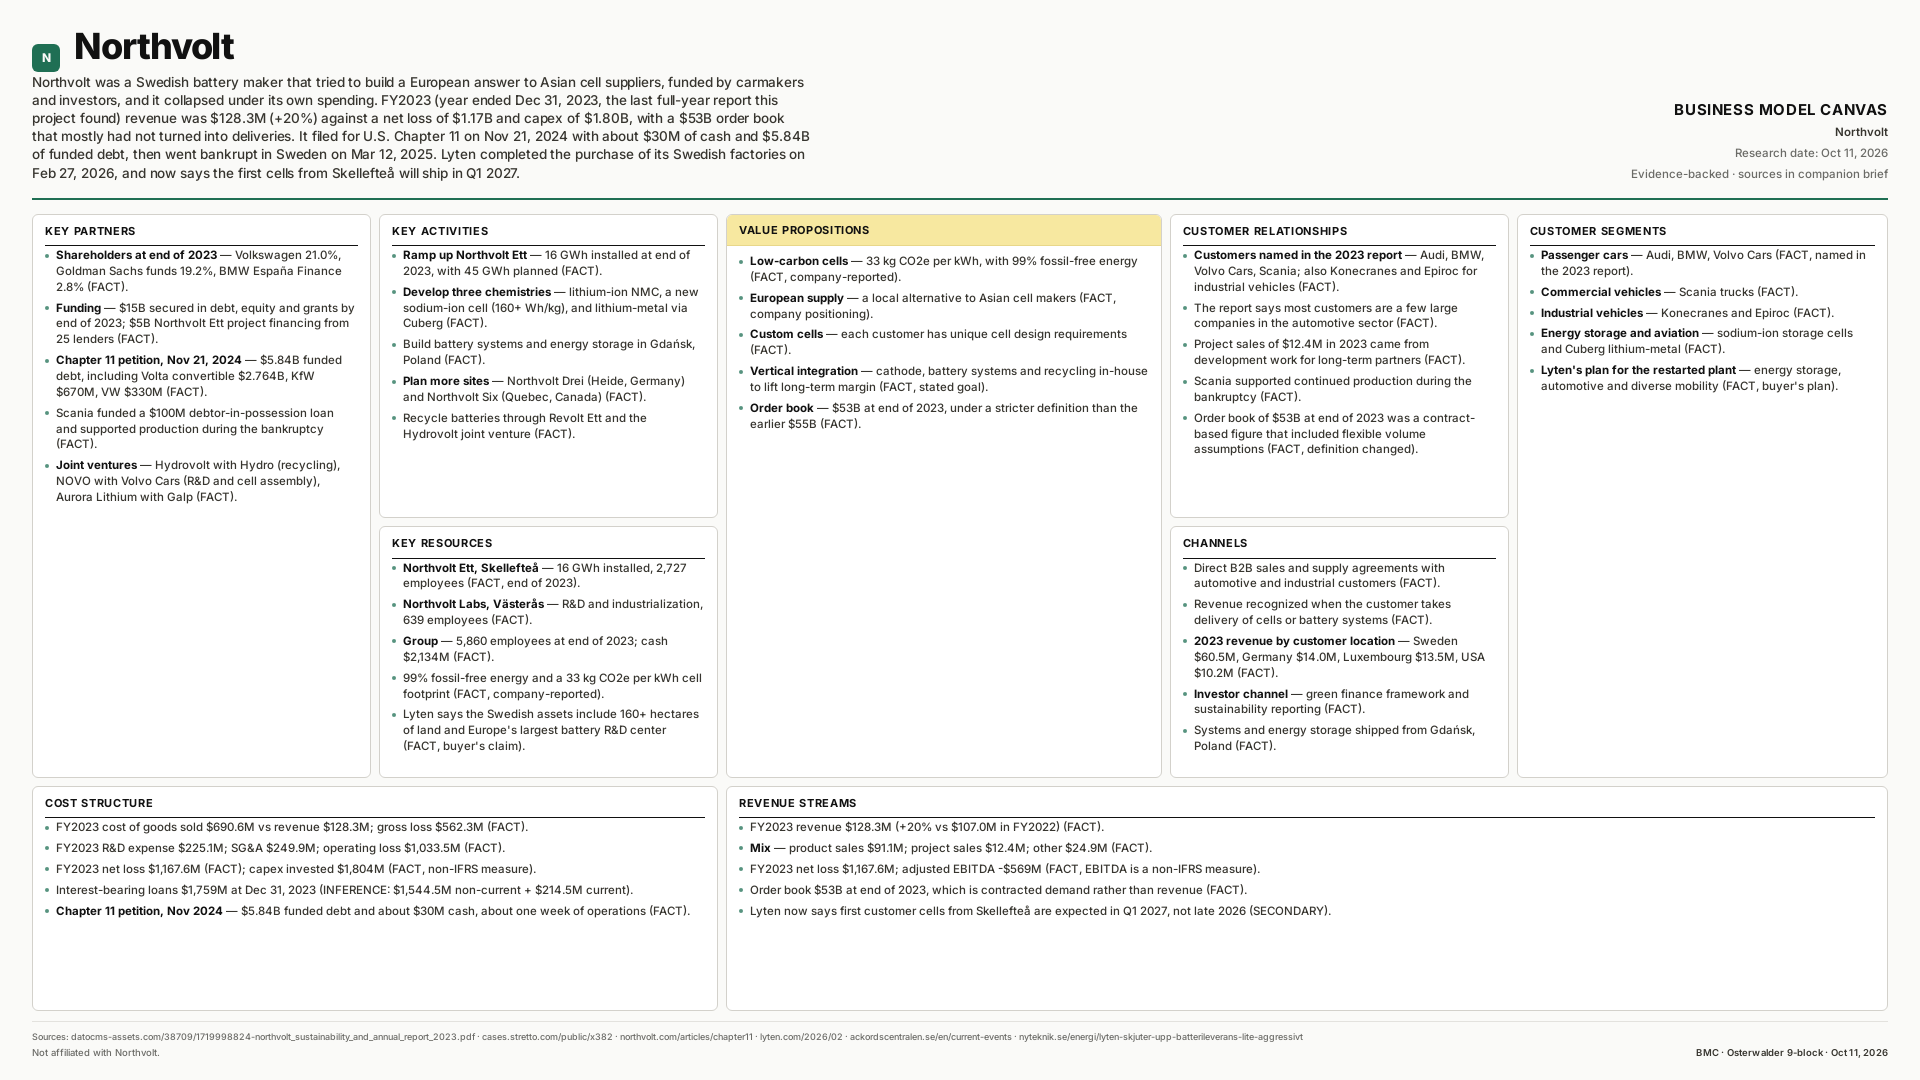

Northvolt
Promised Europe a local low-carbon battery and funded giant factories with carmaker and investor money, but FY2023 revenue was $128.3M against a $1.17B net loss; Chapter 11 in Nov 2024, Swedish bankruptcy in Mar 2025, then a sale to Lyten.
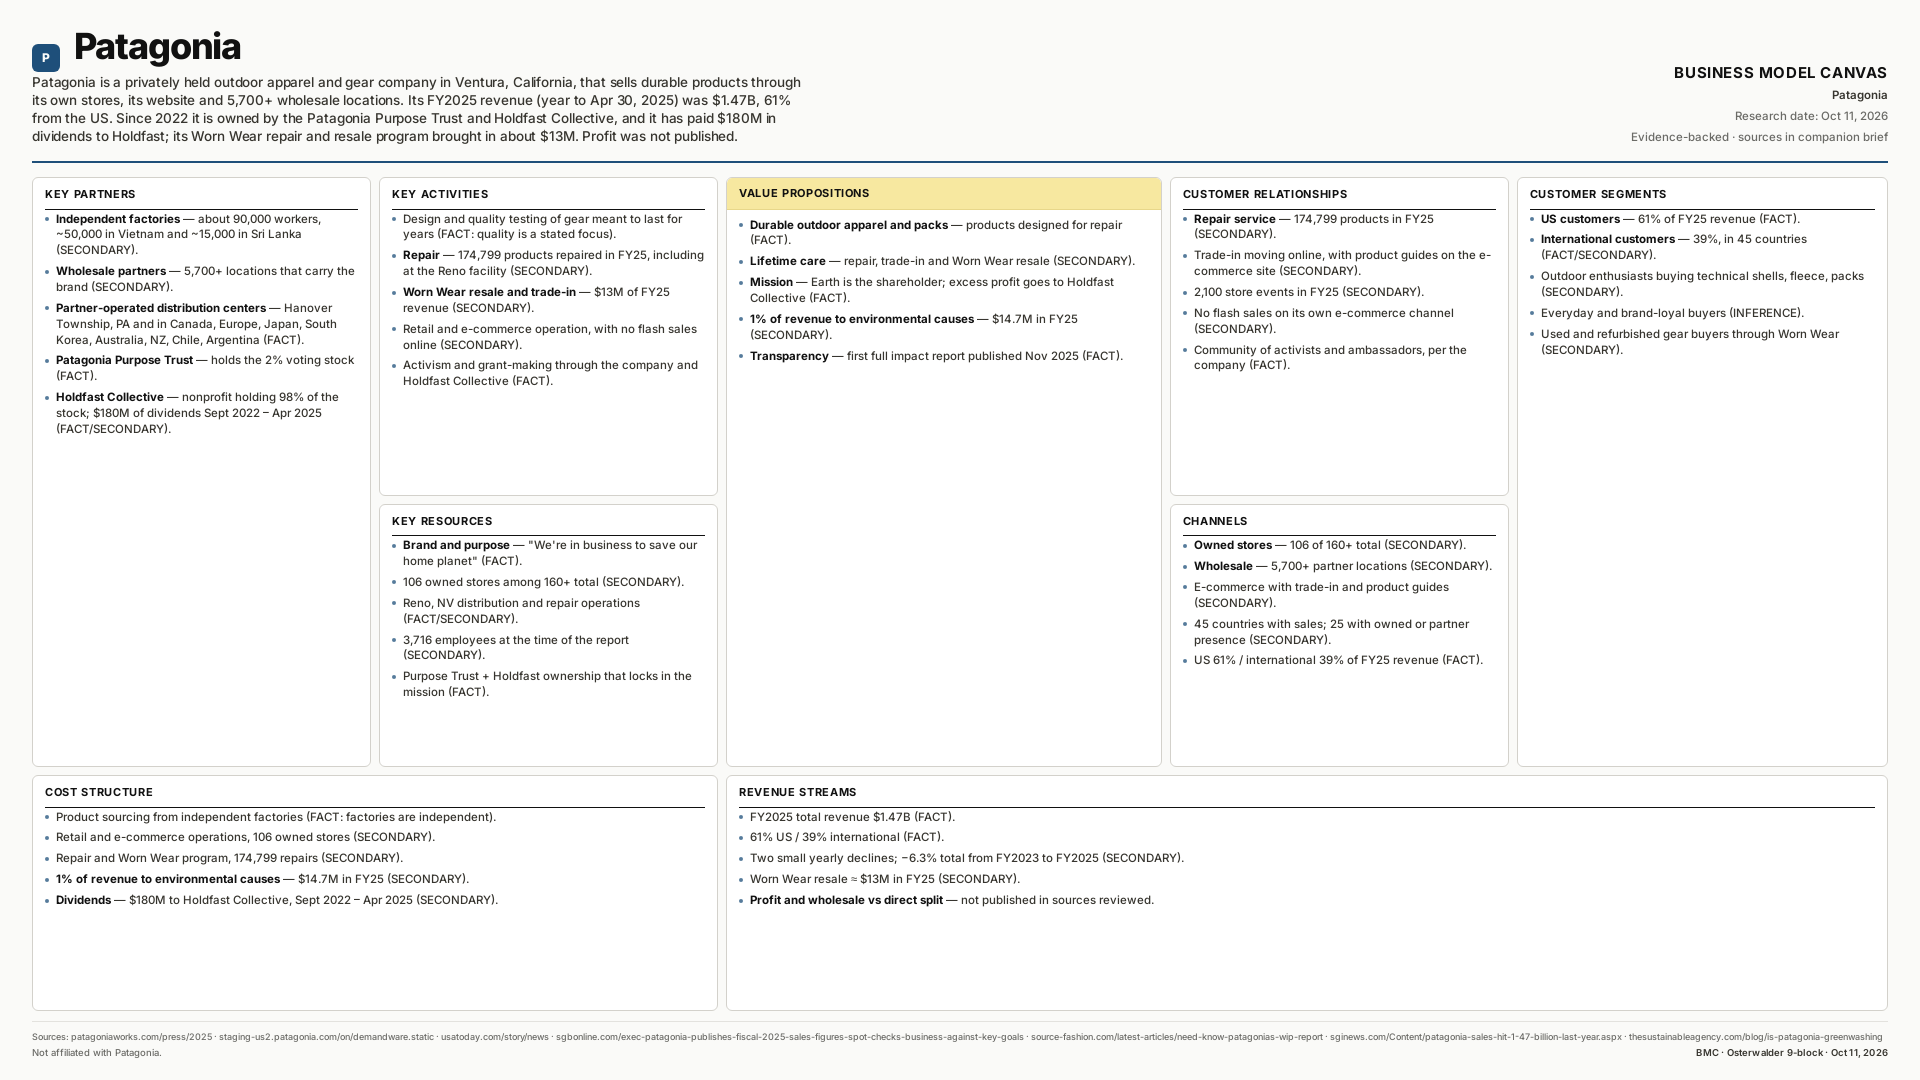

Patagonia
durable outdoor gear sold through its own stores, web and 5,700+ dealers, with FY25 revenue of $1.47B and profit not reinvested paid to nonprofit owners.
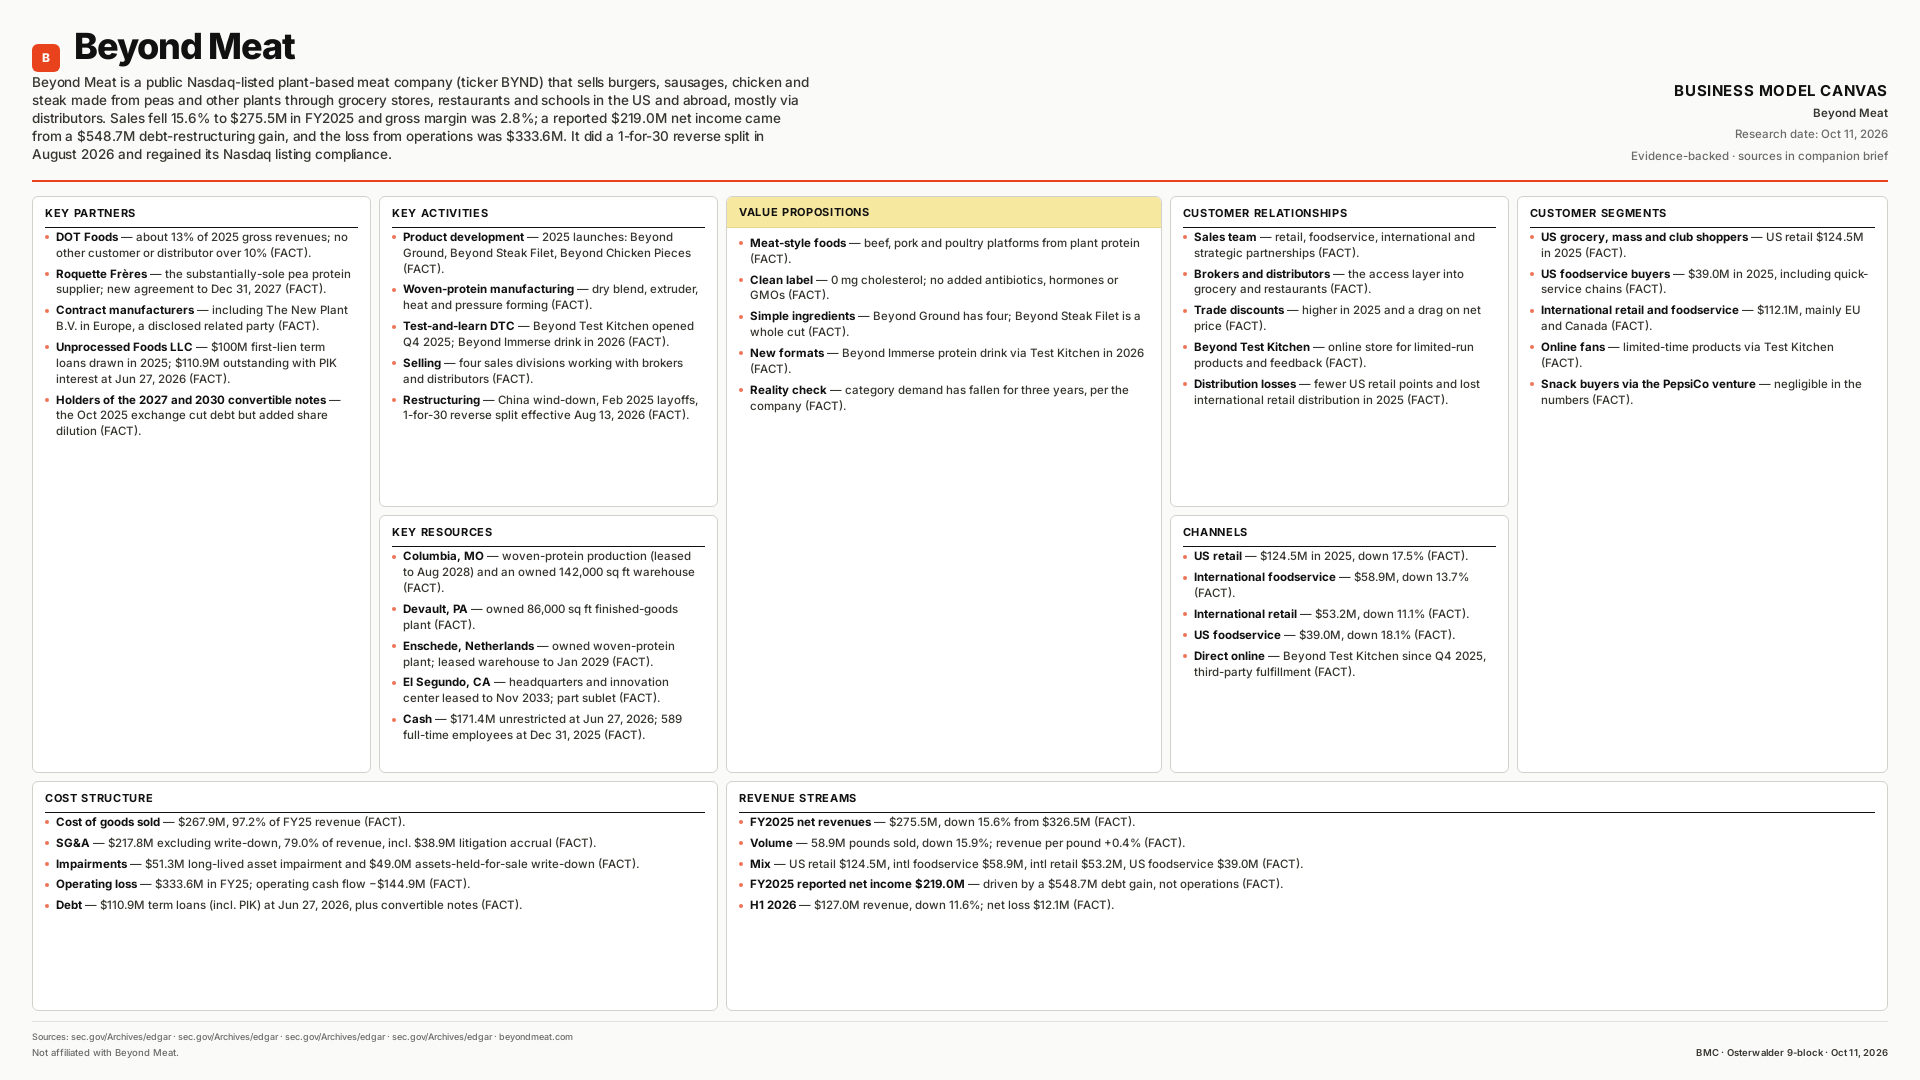

Beyond Meat
plant-based meat sold by the pound through grocery, club and restaurant channels, with sales down 15.6% and a debt gain masking a $333.6M operating loss.
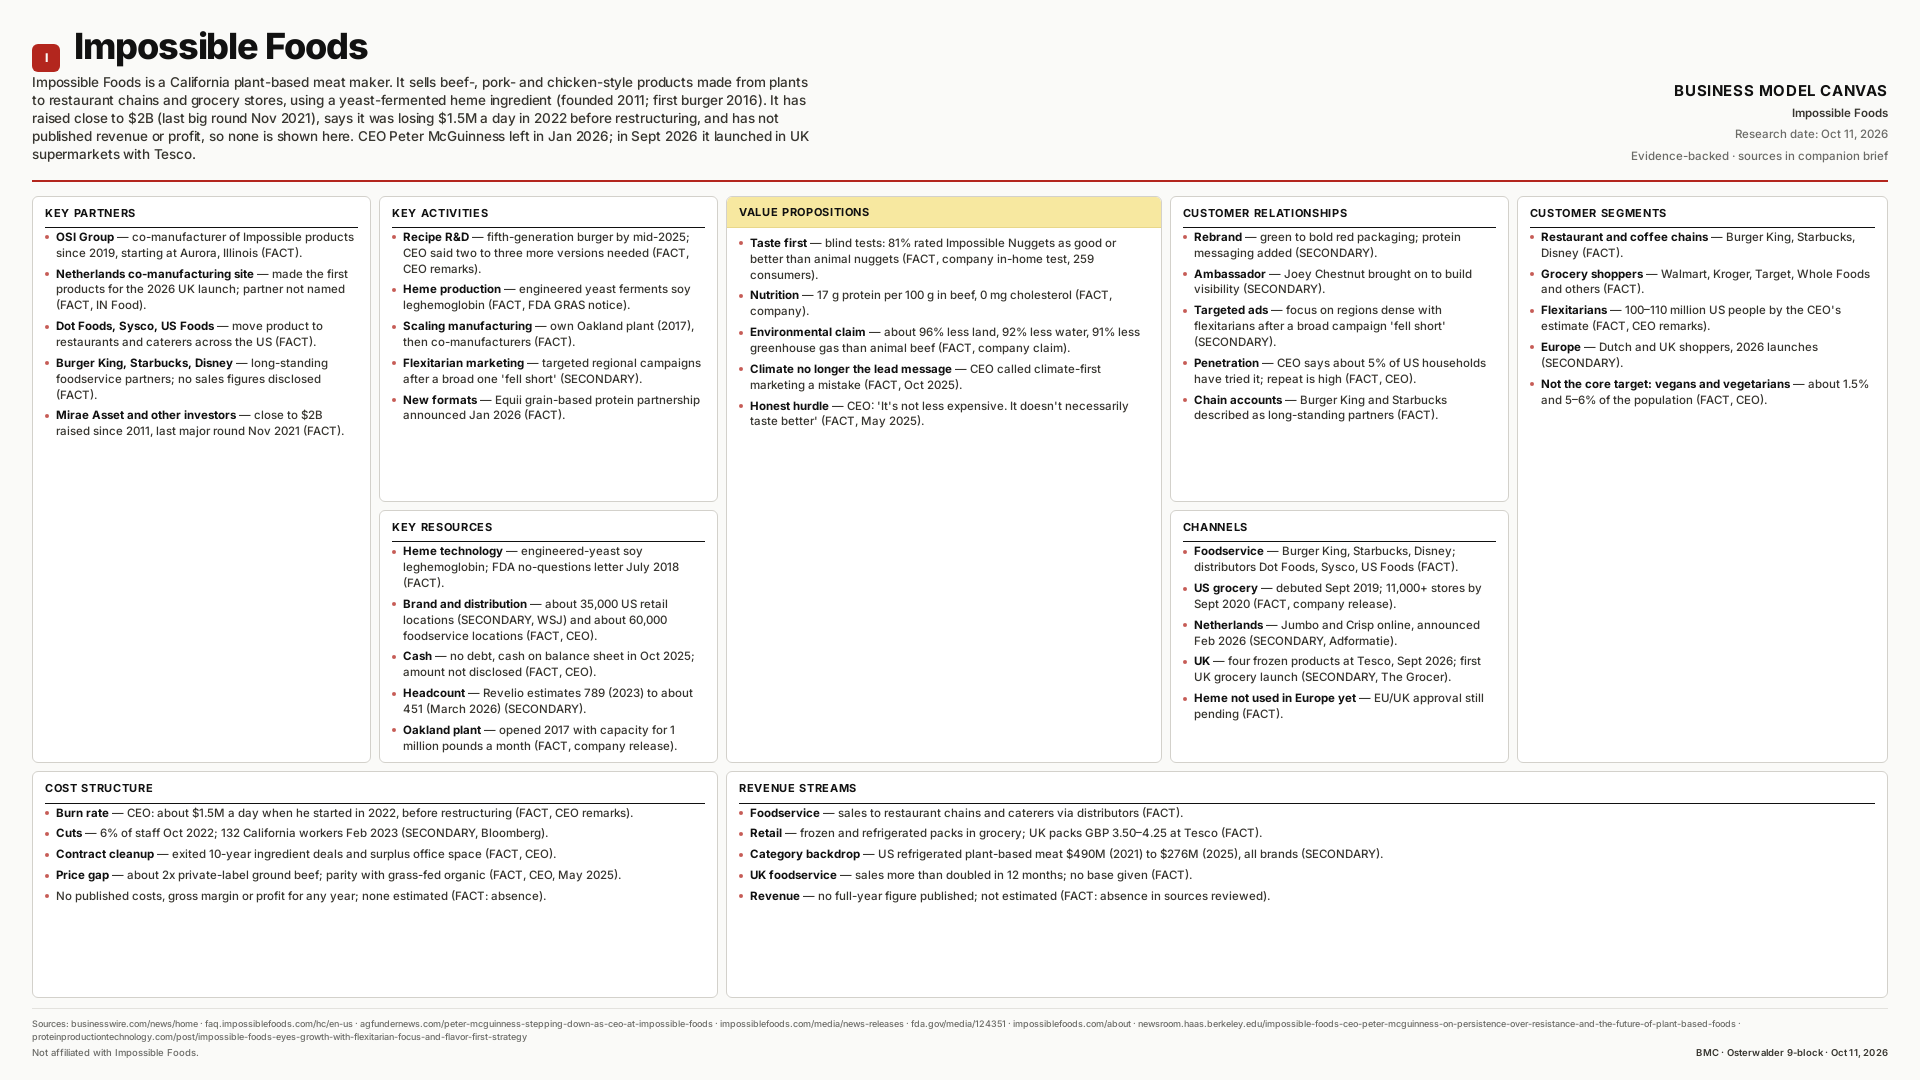

Impossible Foods
Sells meat-taste plant-based products to restaurant chains and grocers, funded by about $2B of venture money: a reported $1.5M-a-day burn in 2022 before restructuring, first UK supermarket launch (Tesco) in Sept 2026, and no published revenue.
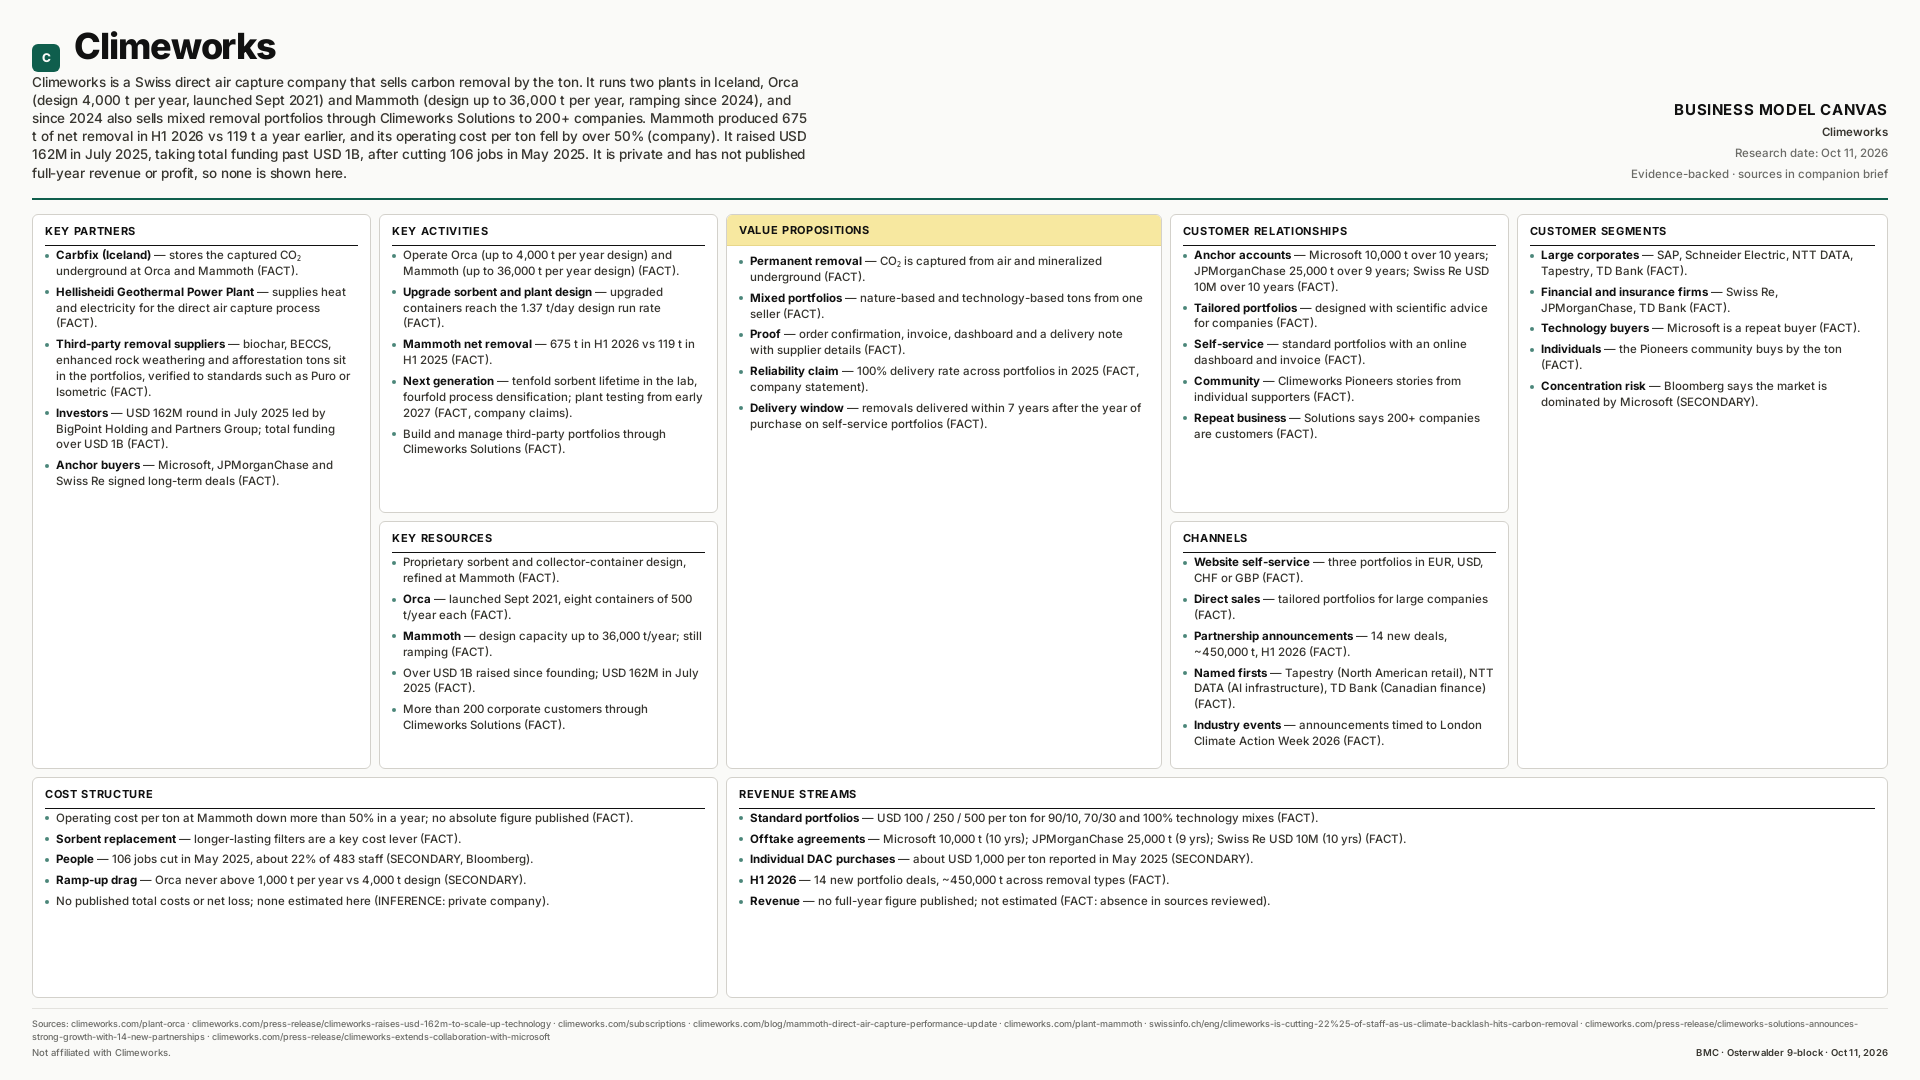

Climeworks
Captures CO₂ from air in Iceland and sells removal by the ton, from its own plants and in mixed portfolios priced at $100-$500 per ton: 675 t removed at Mammoth in H1 2026, over $1B raised, and no published revenue.
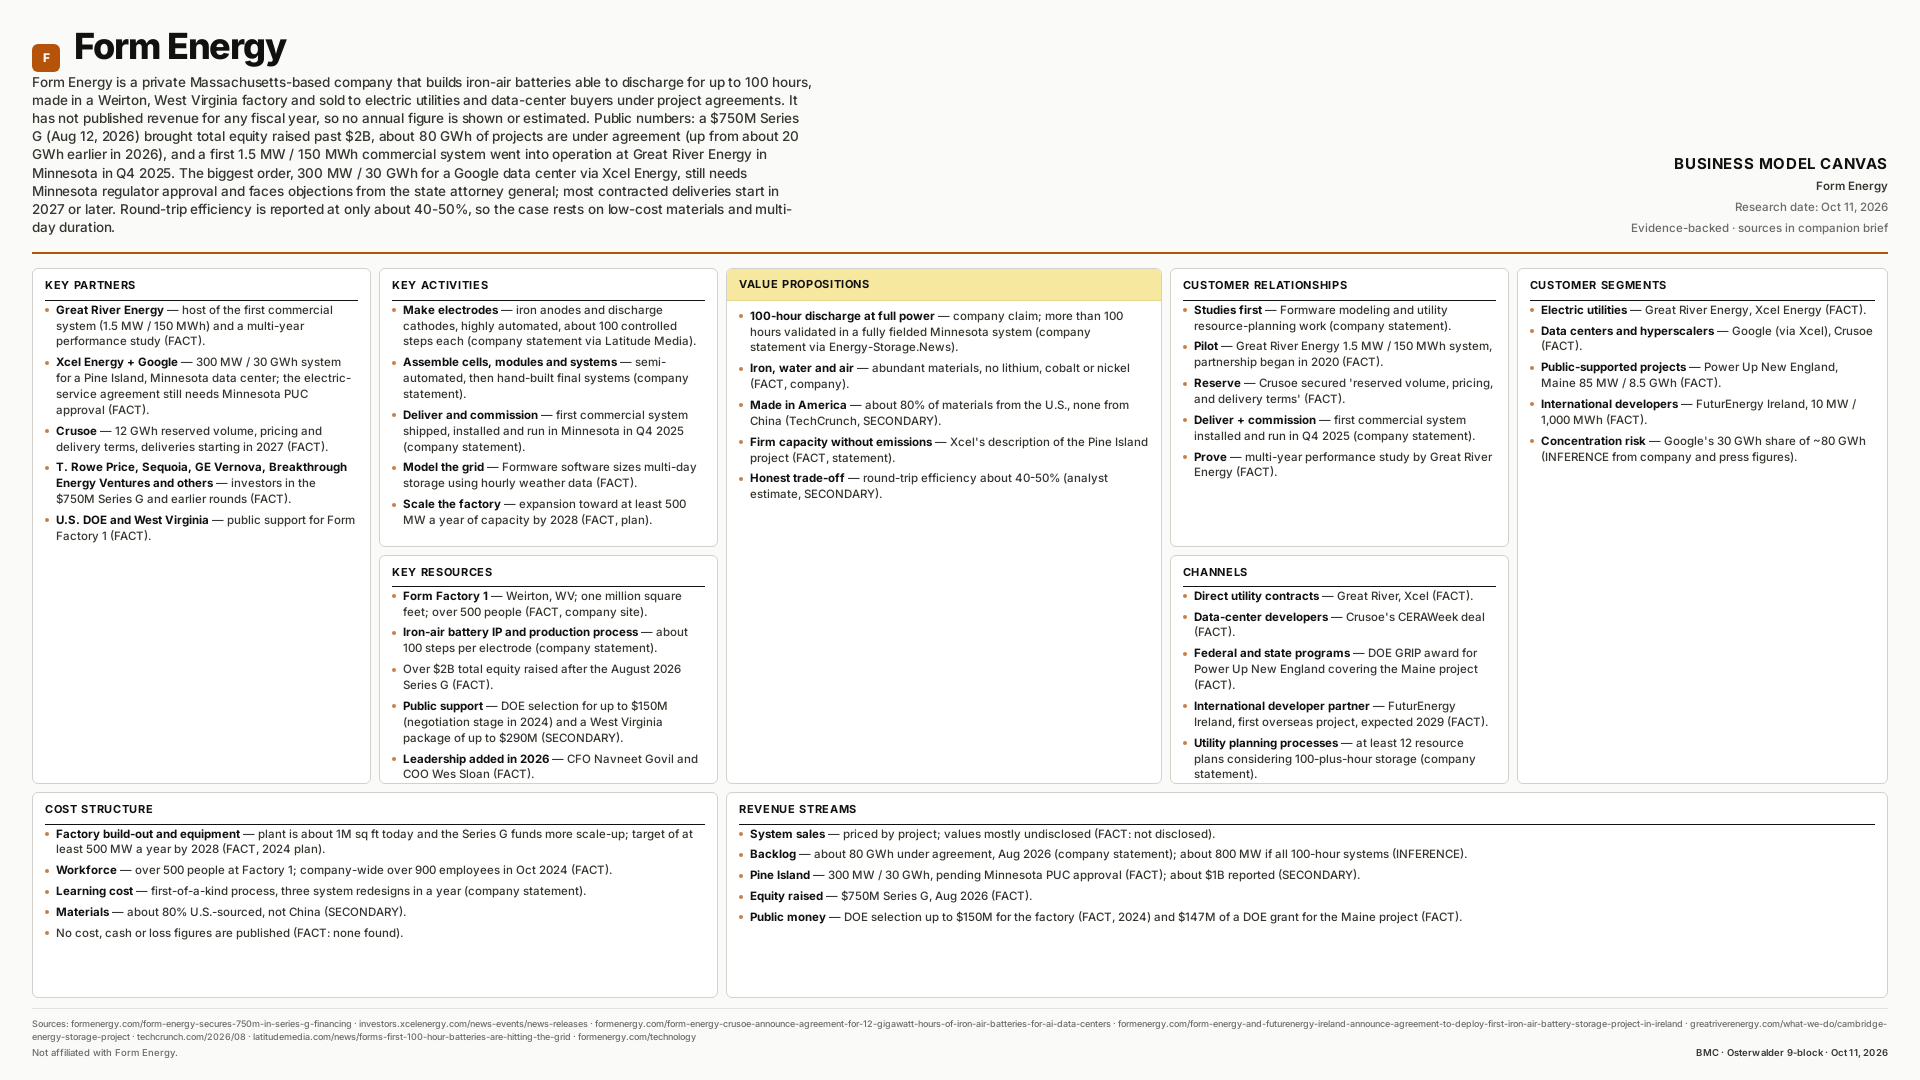

Form Energy
Builds iron-air batteries that can discharge for up to 100 hours and sells them to utilities and data centers by the project: about 80 GWh under agreement, a $750M Series G, and no published revenue yet.
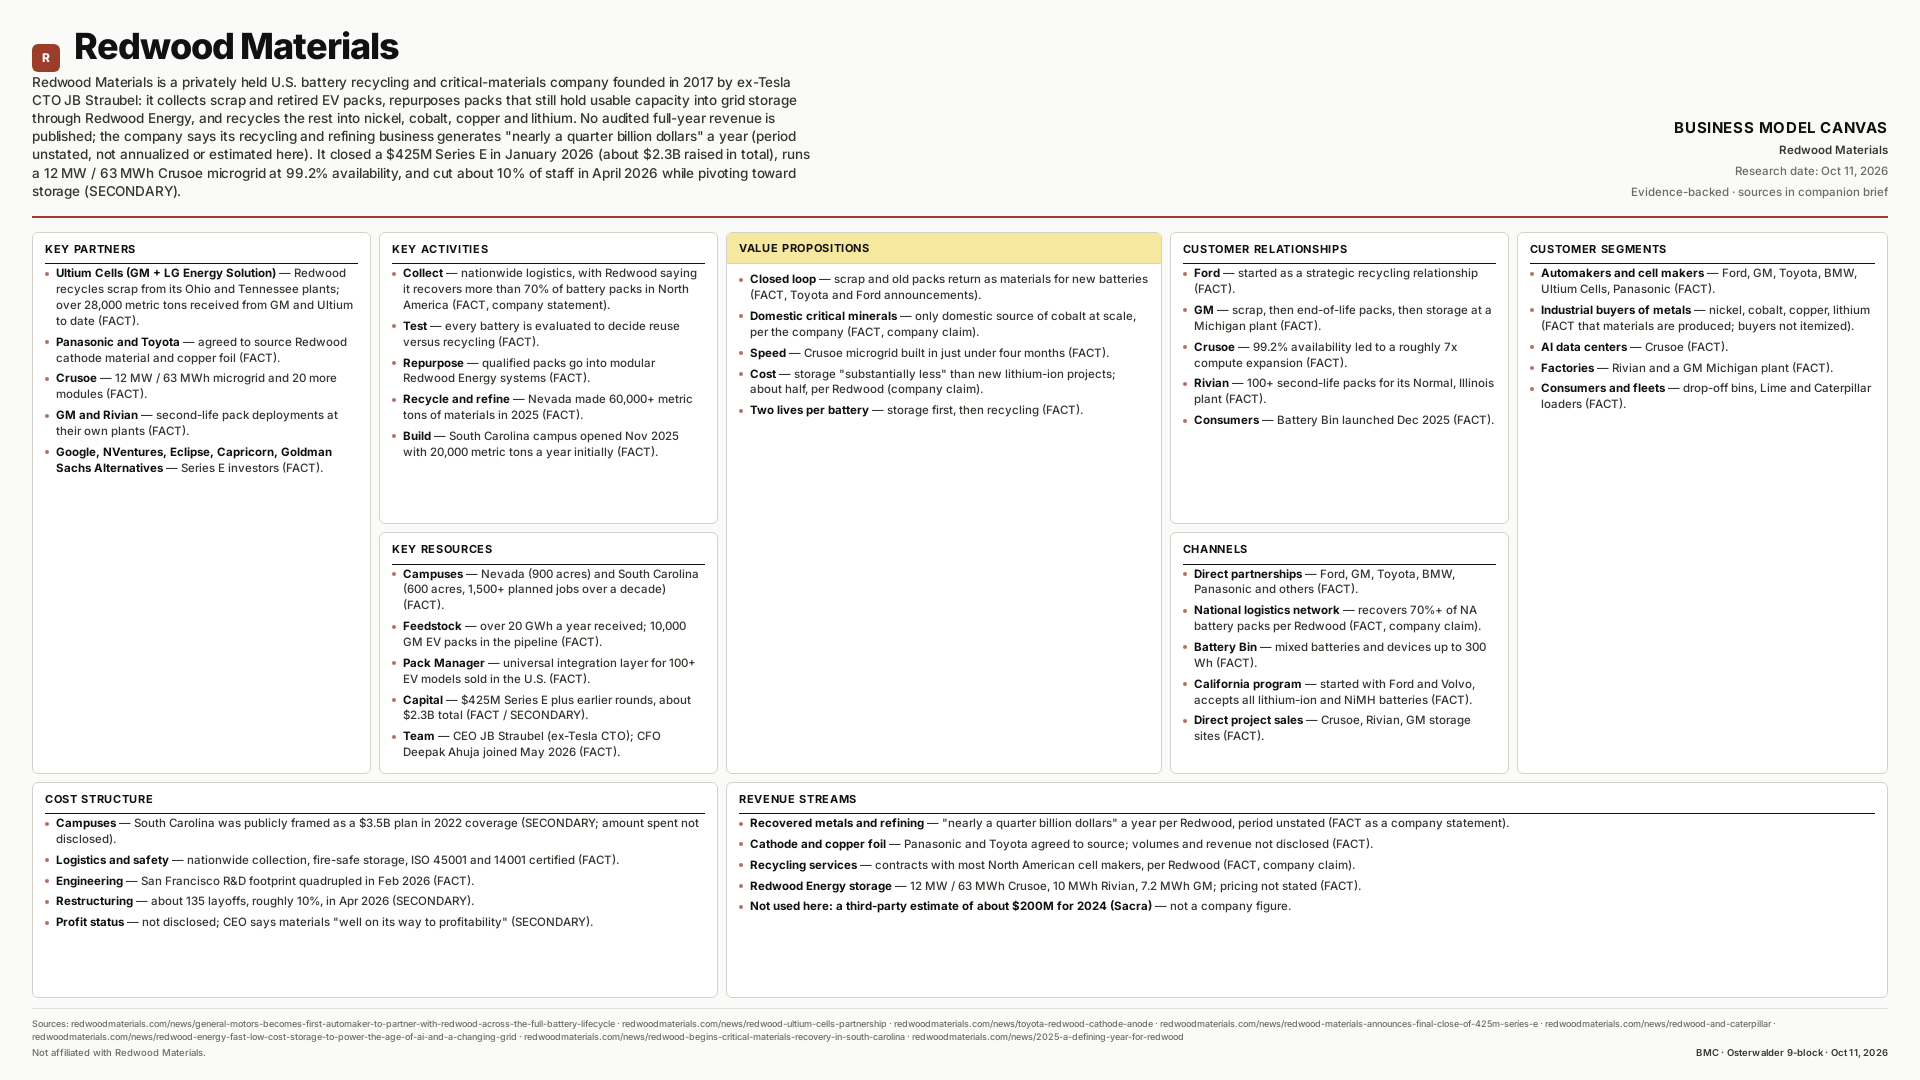

Redwood Materials
A private battery recycler that turns scrap and retired EV packs into recovered metals and second-life grid storage: no audited full-year revenue is public, a $425M Series E (Jan 2026), and a 12 MW / 63 MWh Crusoe microgrid at 99.2% availability.
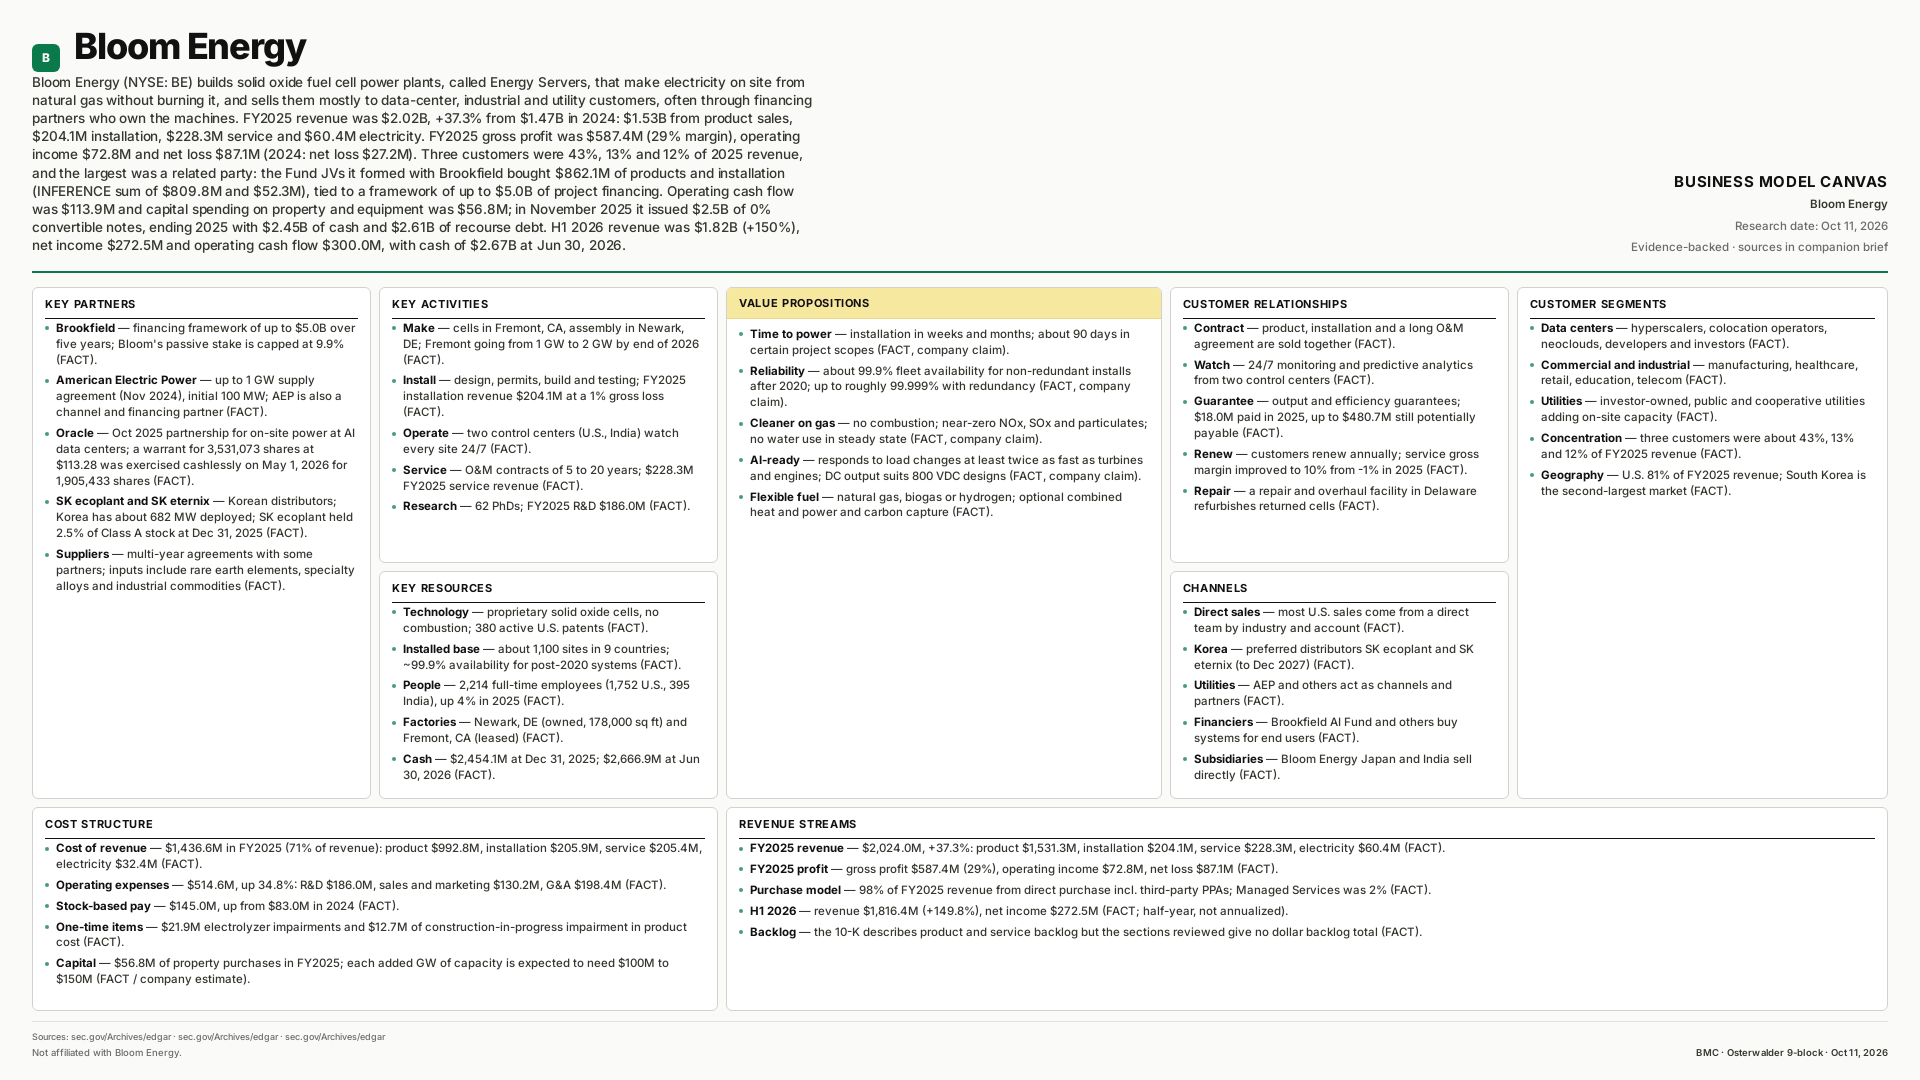

Bloom Energy
Builds fuel cell power plants that make electricity on site without burning gas and sells them to data centers, industry and utilities, often via financing partners: $2.02B FY2025 revenue (+37%), net loss $87.1M, then H1 2026 revenue $1.82B (+150%) and net income $272.5M.
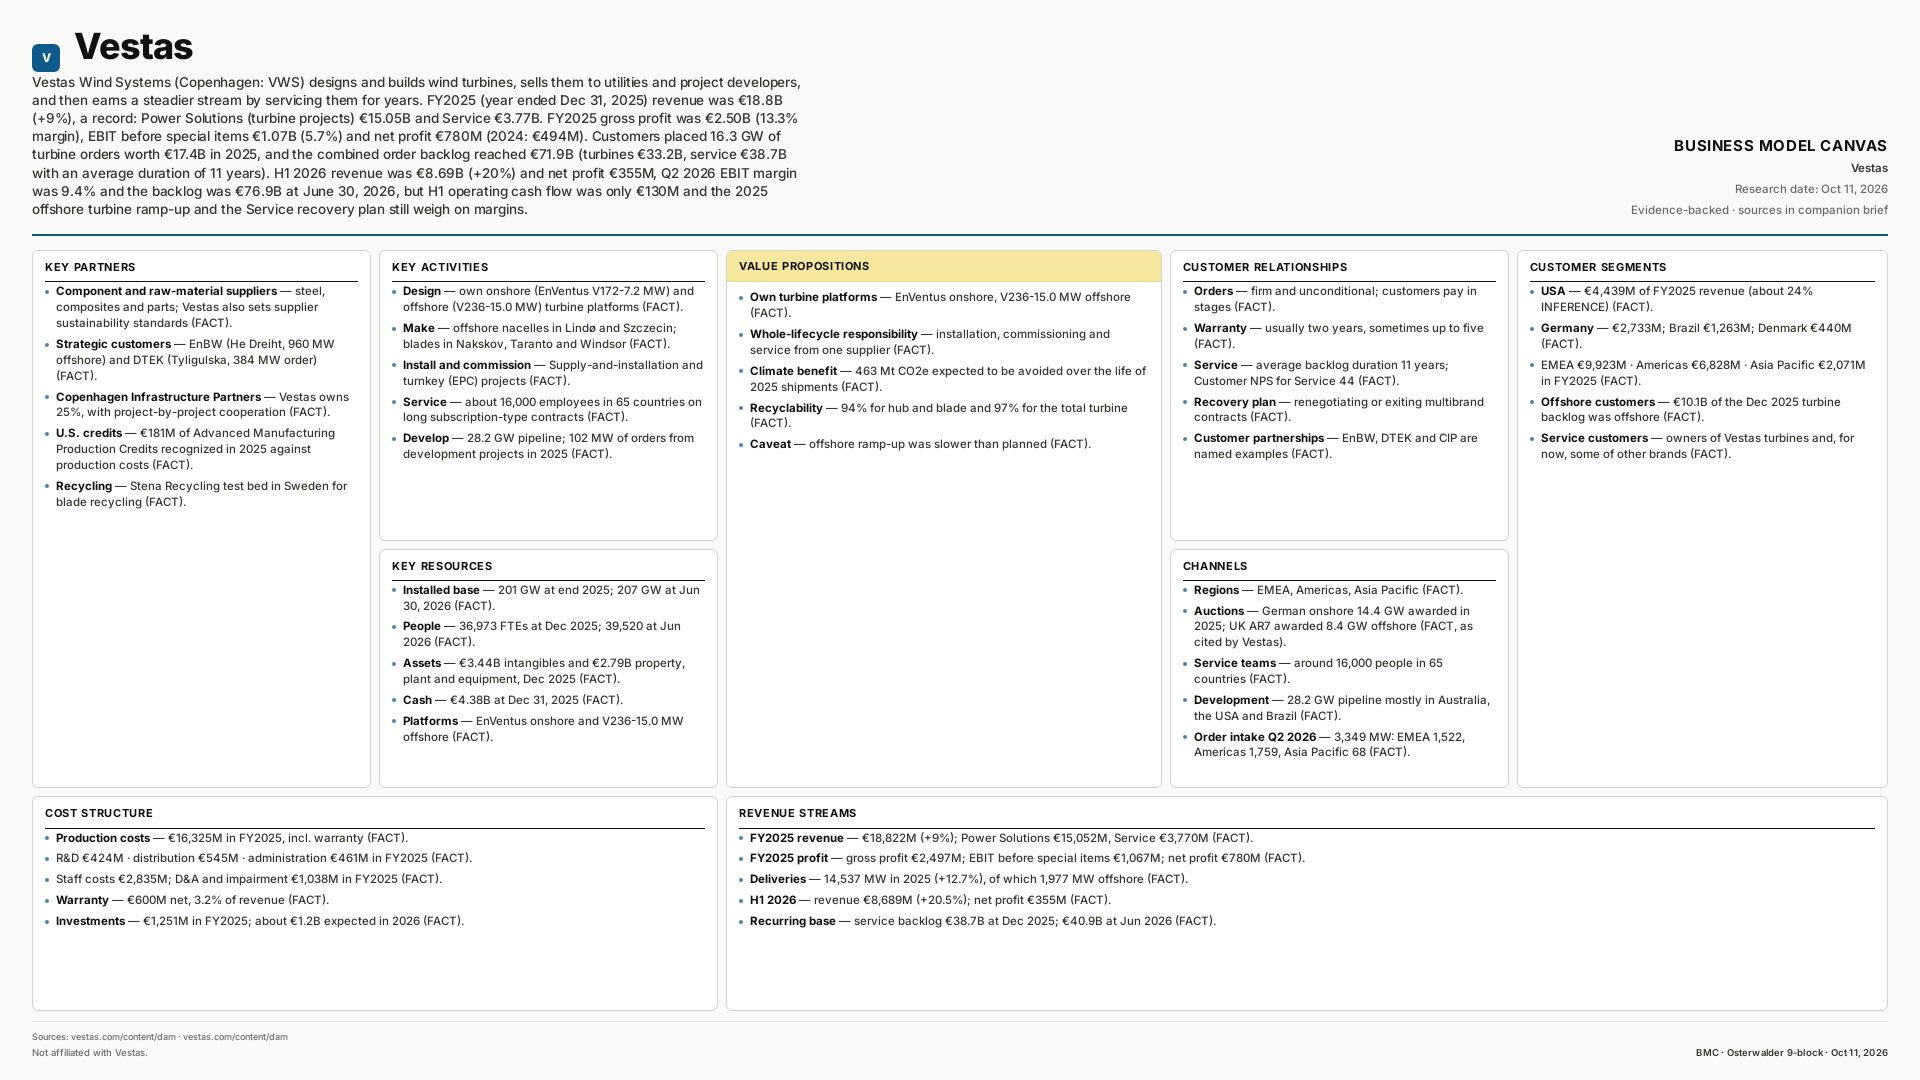

Vestas
Designs and builds wind turbines, sells them to wind-farm owners and then services them for years: €18.8B FY2025 revenue (+9%), net profit €780M, €71.9B combined order backlog, then H1 2026 revenue +20% with a raised margin outlook.
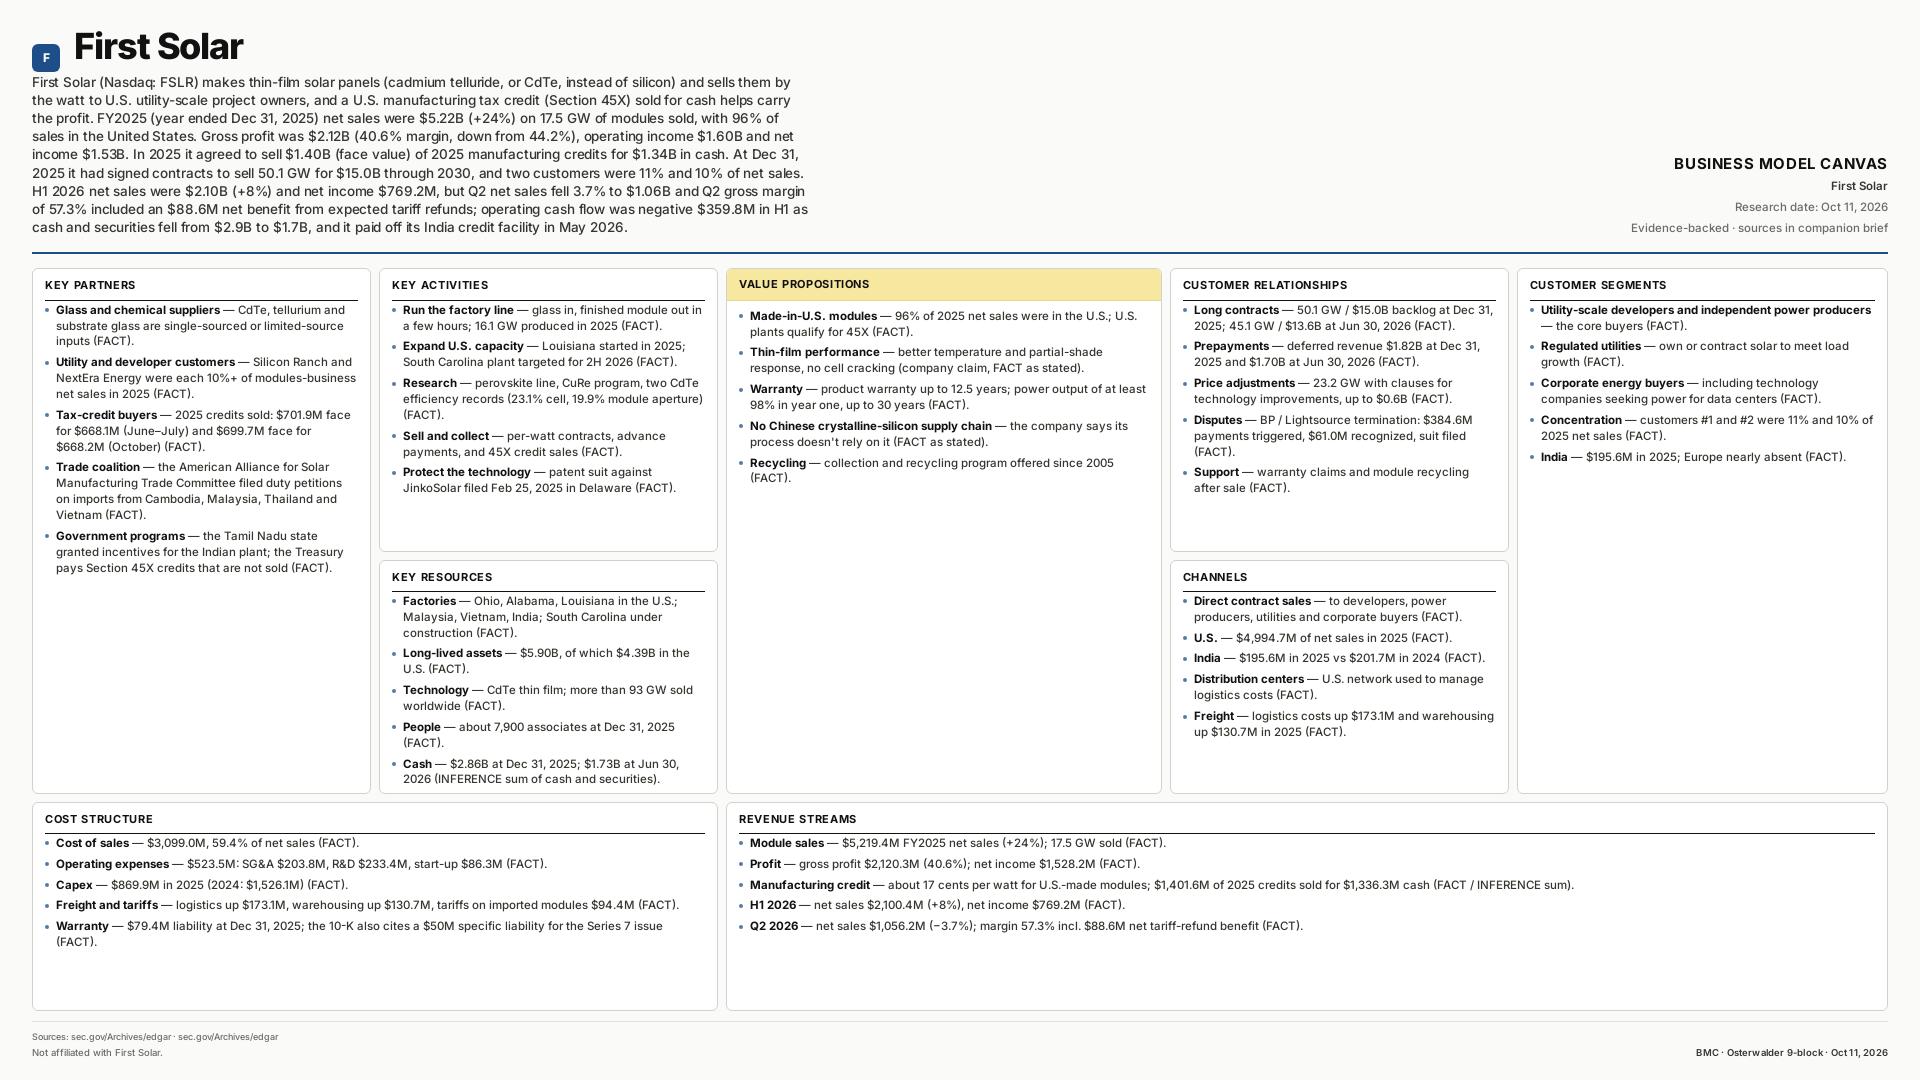

First Solar
Makes thin-film solar panels in U.S. factories and sells them by the watt to utility-scale buyers, helped by a manufacturing tax credit sold for cash: $5.22B FY2025 net sales (+24%), net income $1.53B, $15.0B contracted backlog, then H1 2026 net sales +8% with negative operating cash flow.
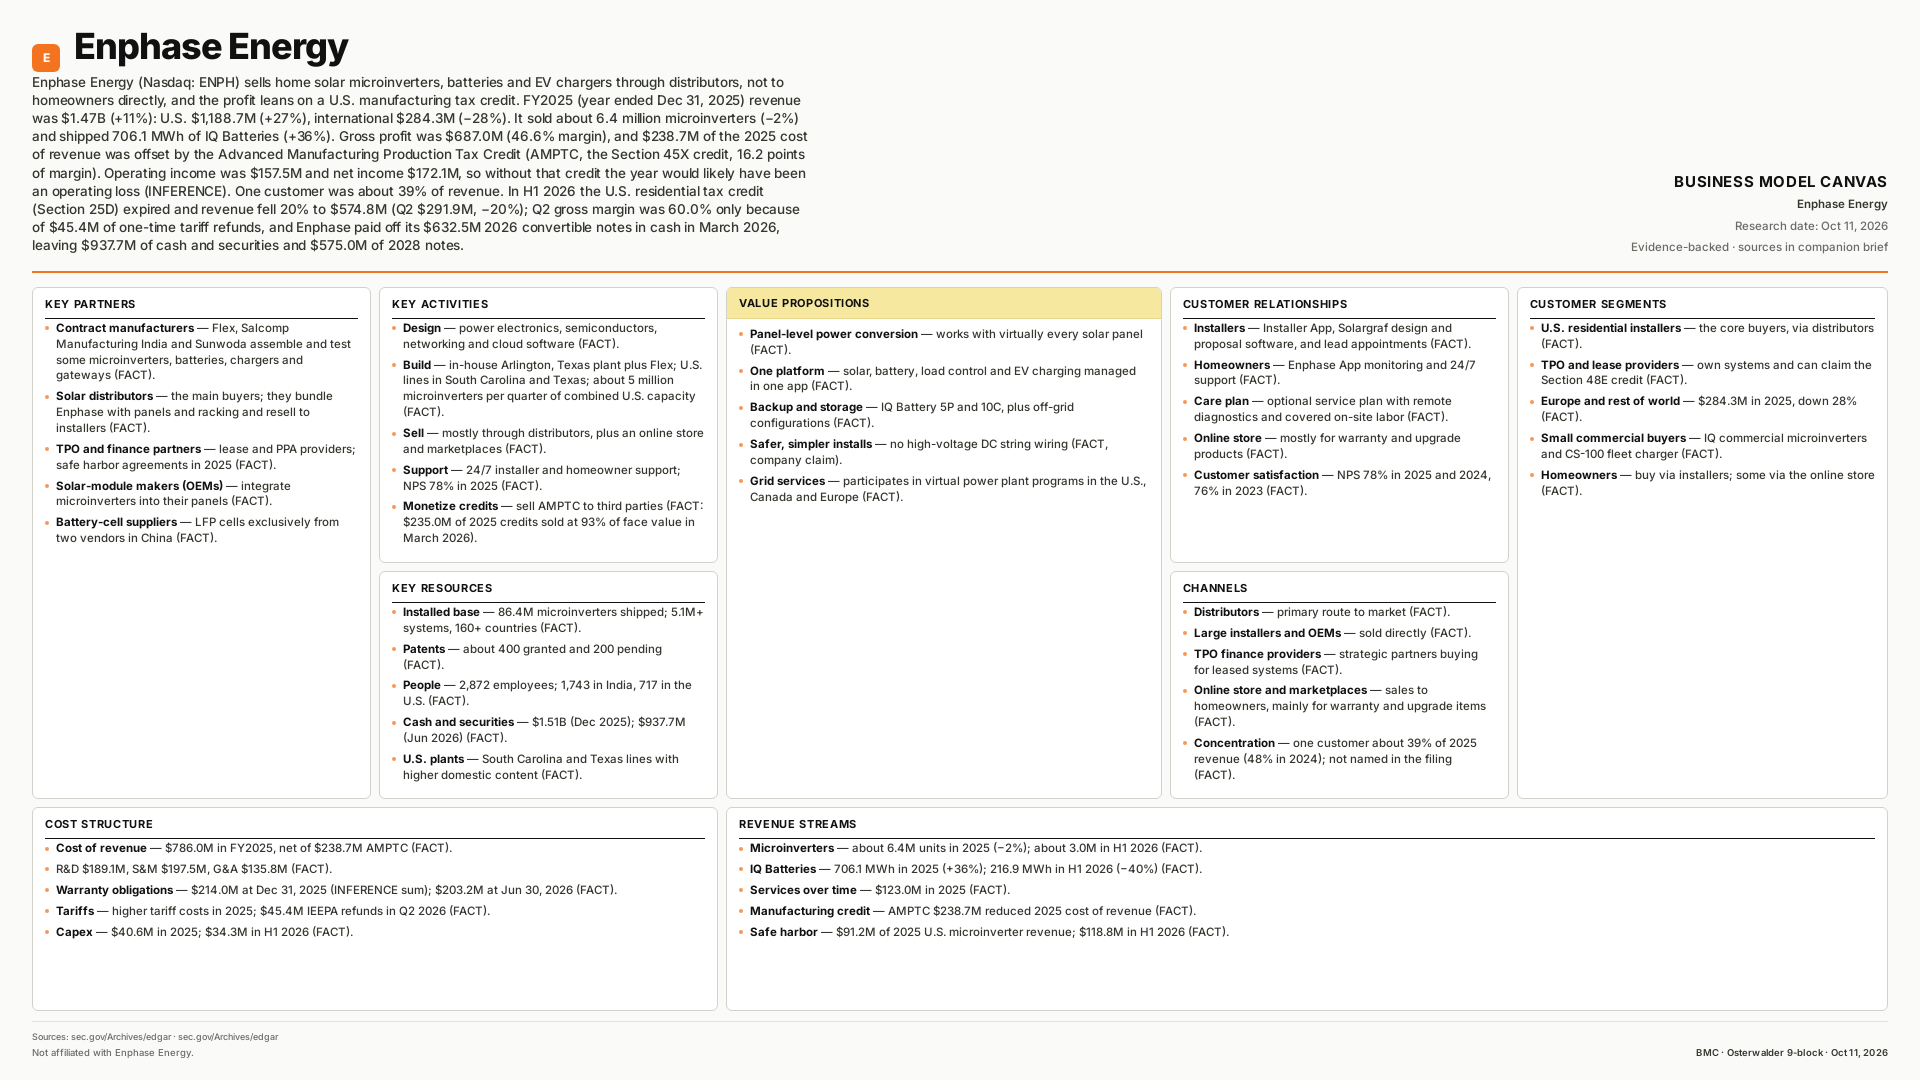

Enphase Energy
Sells solar microinverters, batteries and EV chargers through distributors, and a $238.7M U.S. manufacturing tax credit carries the profit: $1.47B FY2025 revenue (+11%), net income $172.1M, then H1 2026 revenue −20% after the home solar credit ended.
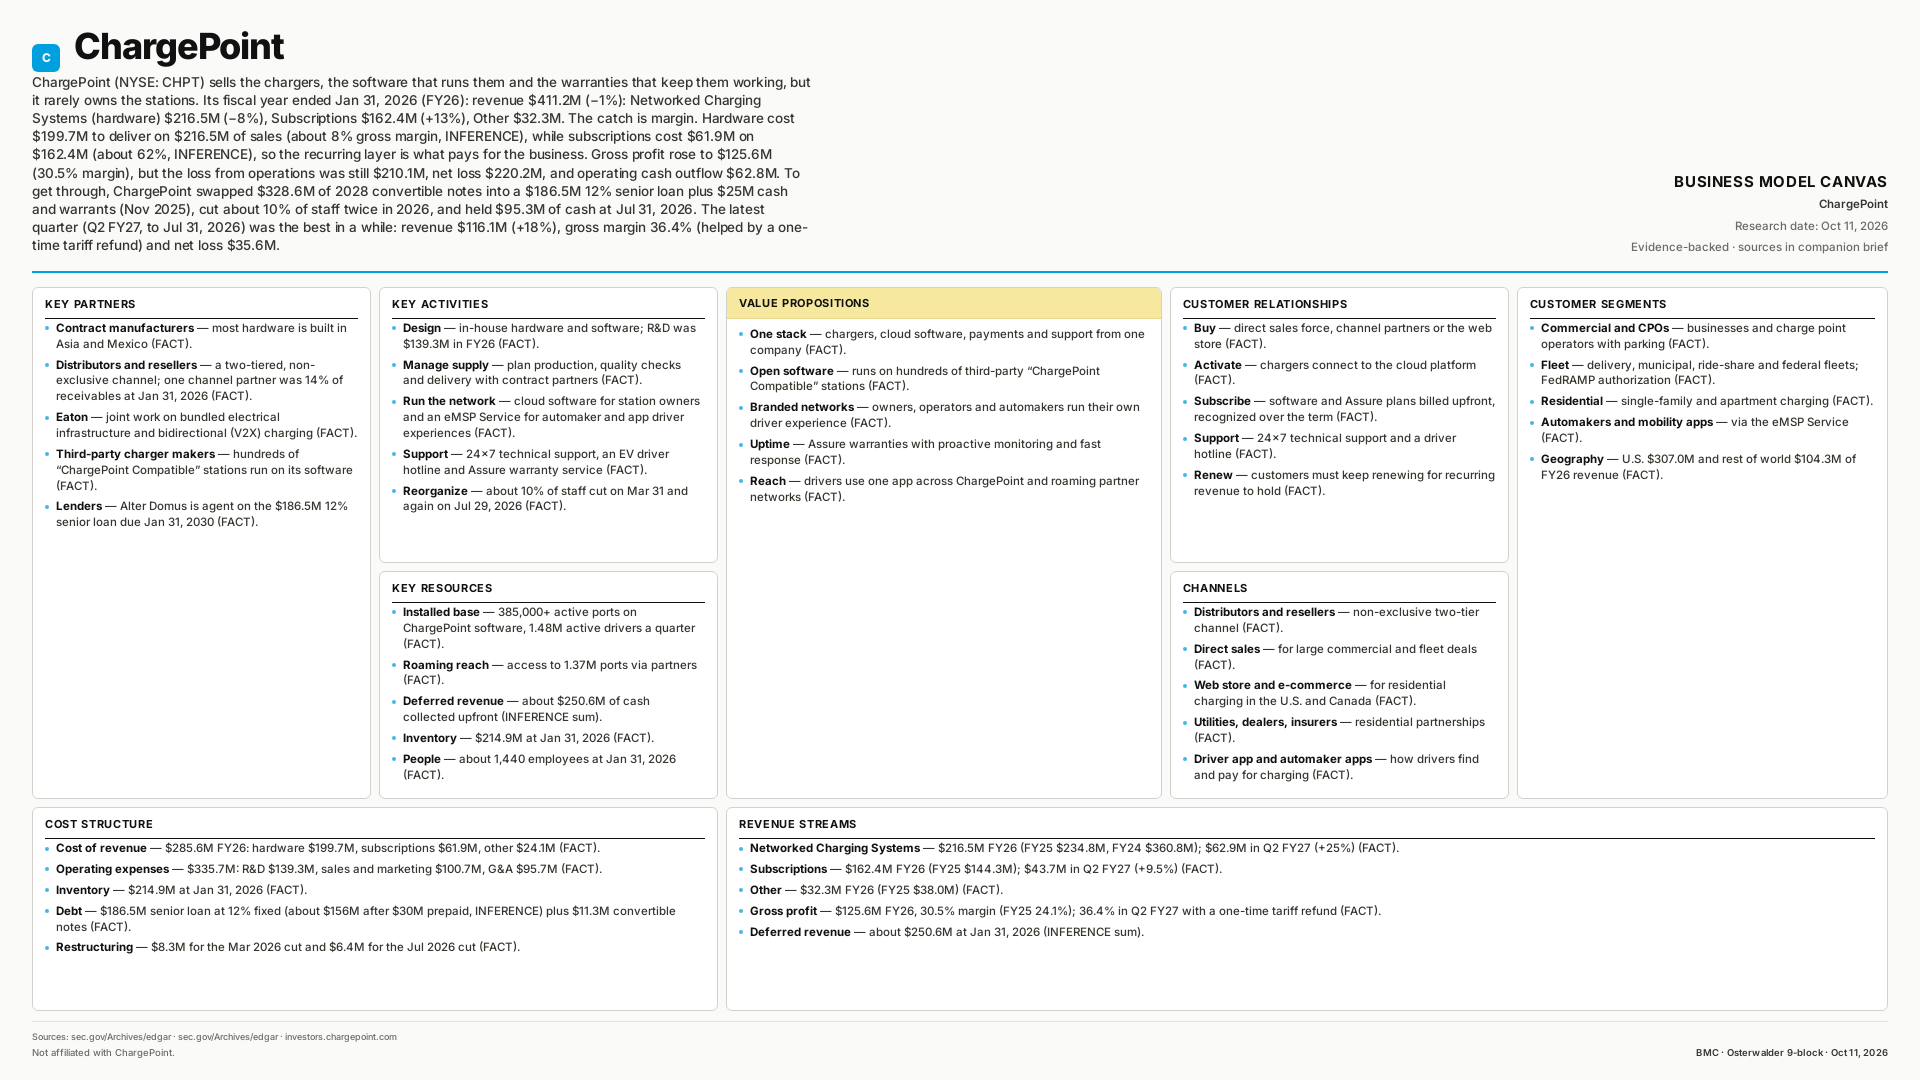

ChargePoint
Sells EV chargers near cost and earns the profit on software and warranty subscriptions: $411.2M FY26 revenue (−1%), subscriptions $162.4M at ~62% gross margin vs hardware ~8%, net loss $220.2M, and a 2025 debt exchange.
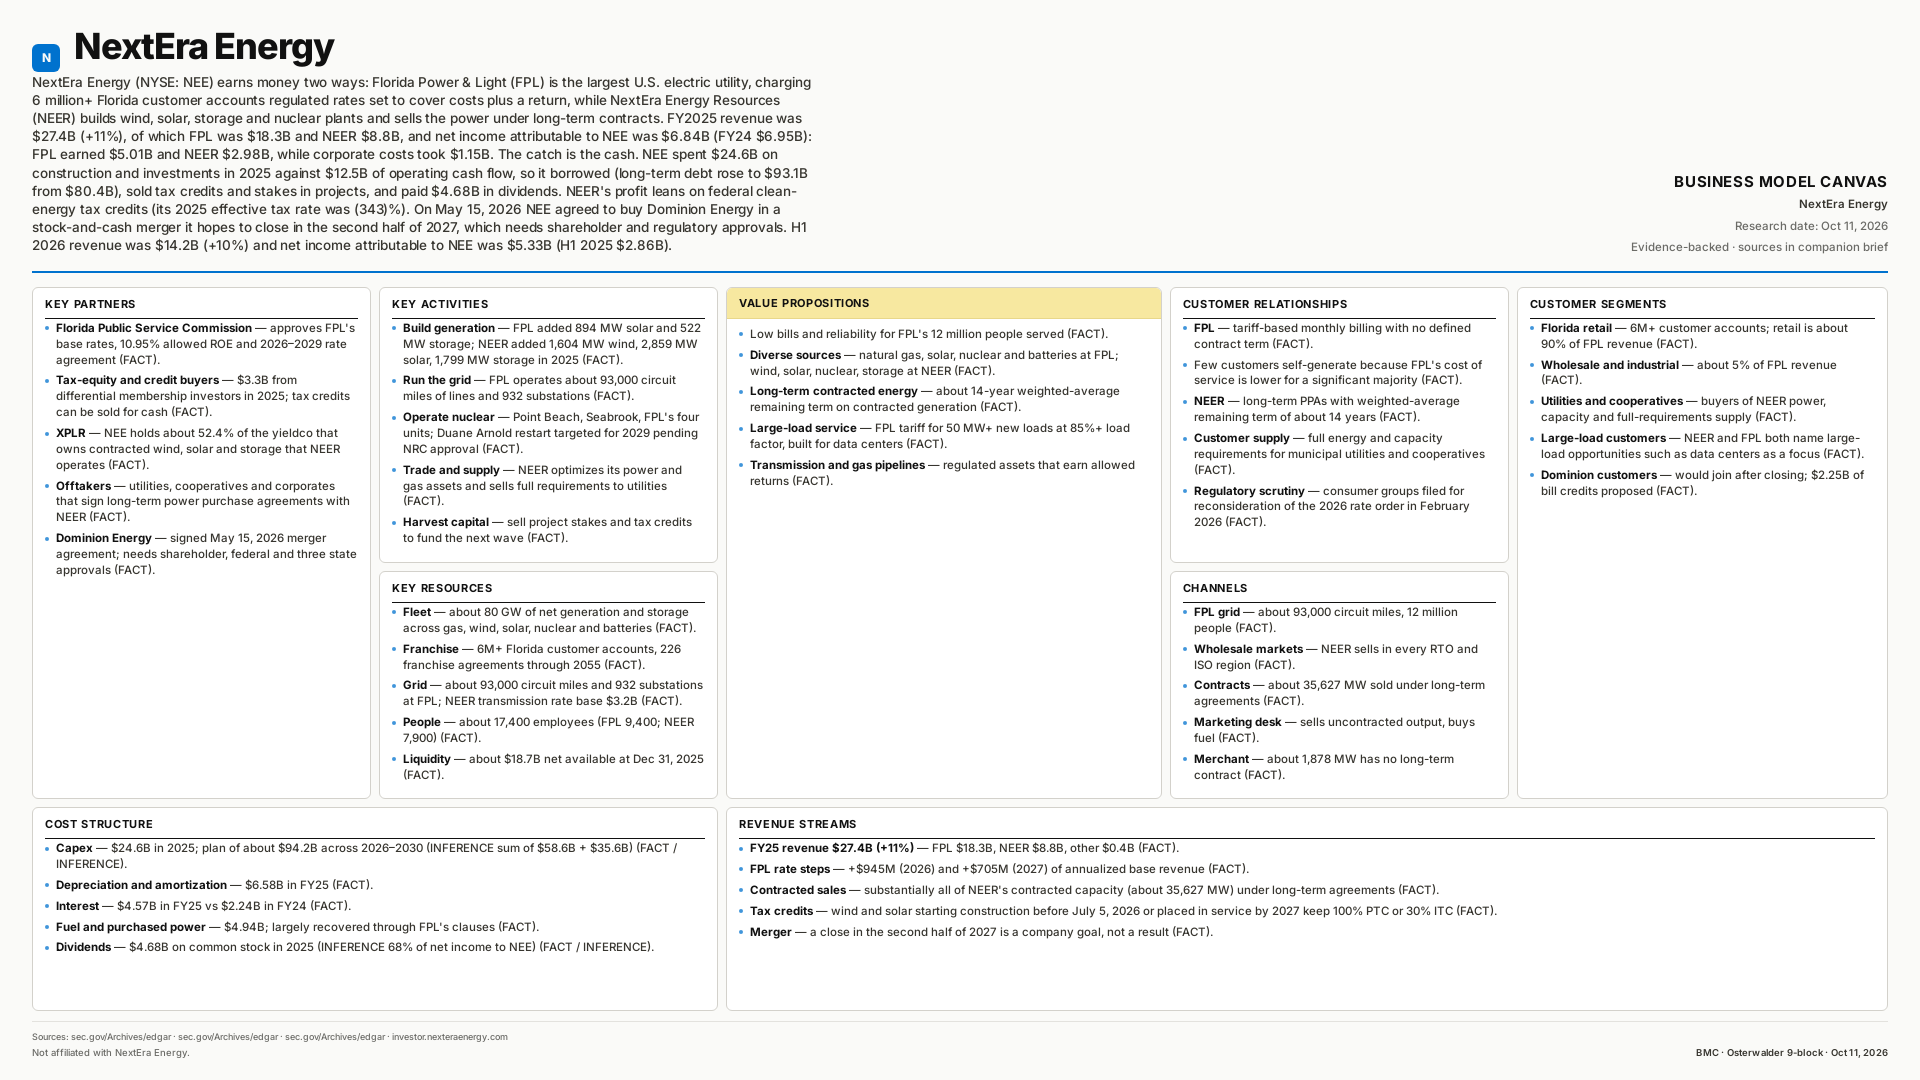

NextEra Energy
A regulated Florida utility plus a contracted renewables builder, funded by debt and tax credits: $27.4B FY25 revenue (+11%), $6.84B net income, $24.6B invested vs $12.5B operating cash flow, and a pending Dominion merger.
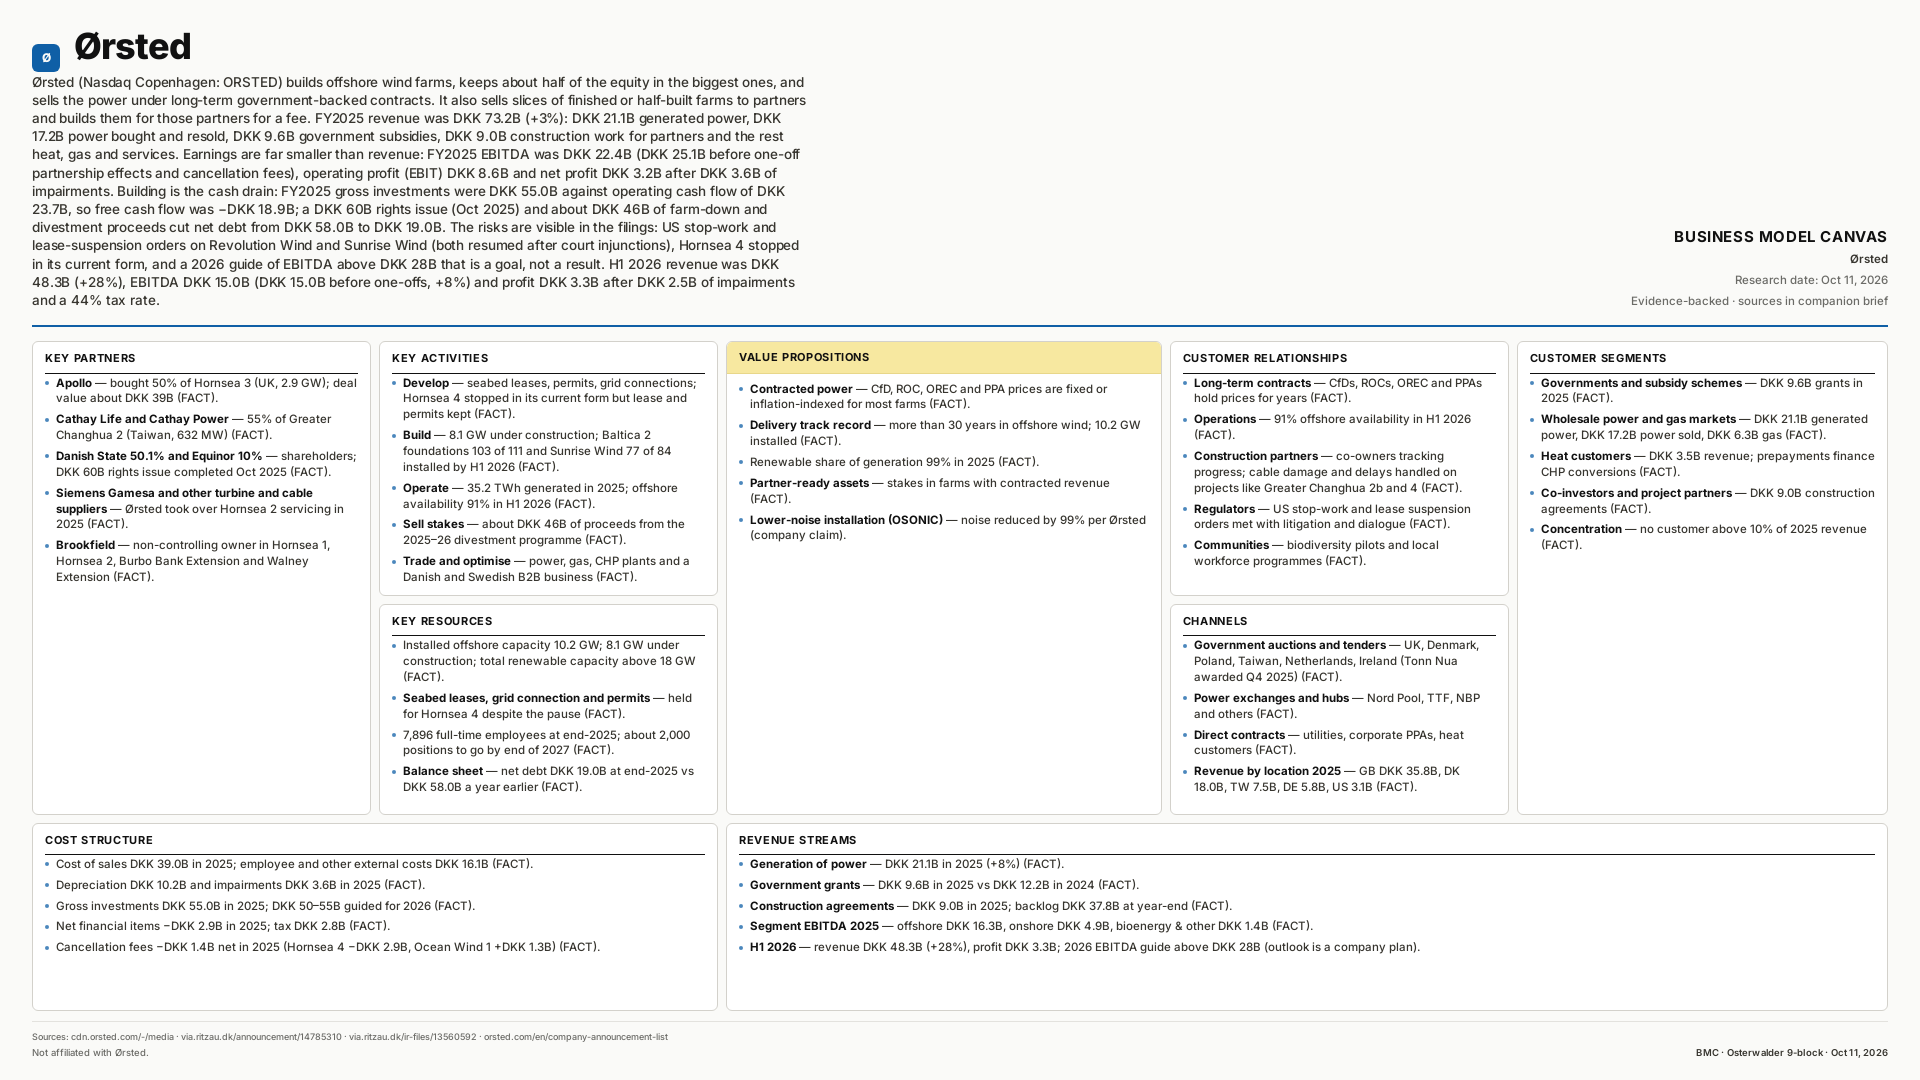

Ørsted
Offshore wind built with partners and paid for by long-term contract prices: DKK 73.2B FY25 revenue (+3%) = generated power DKK 21.1B + resold power DKK 17.2B + subsidies DKK 9.6B + construction for partners DKK 9.0B + heat, gas and services → EBITDA DKK 22.4B, net profit DKK 3.2B, free cash flow −DKK 18.9B → DKK 60B rights issue and ~DKK 46B of farm-downs cut net debt to DKK 19.0B; H1 2026 revenue DKK 48.3B (+28%), 2026 EBITDA guide above DKK 28B.
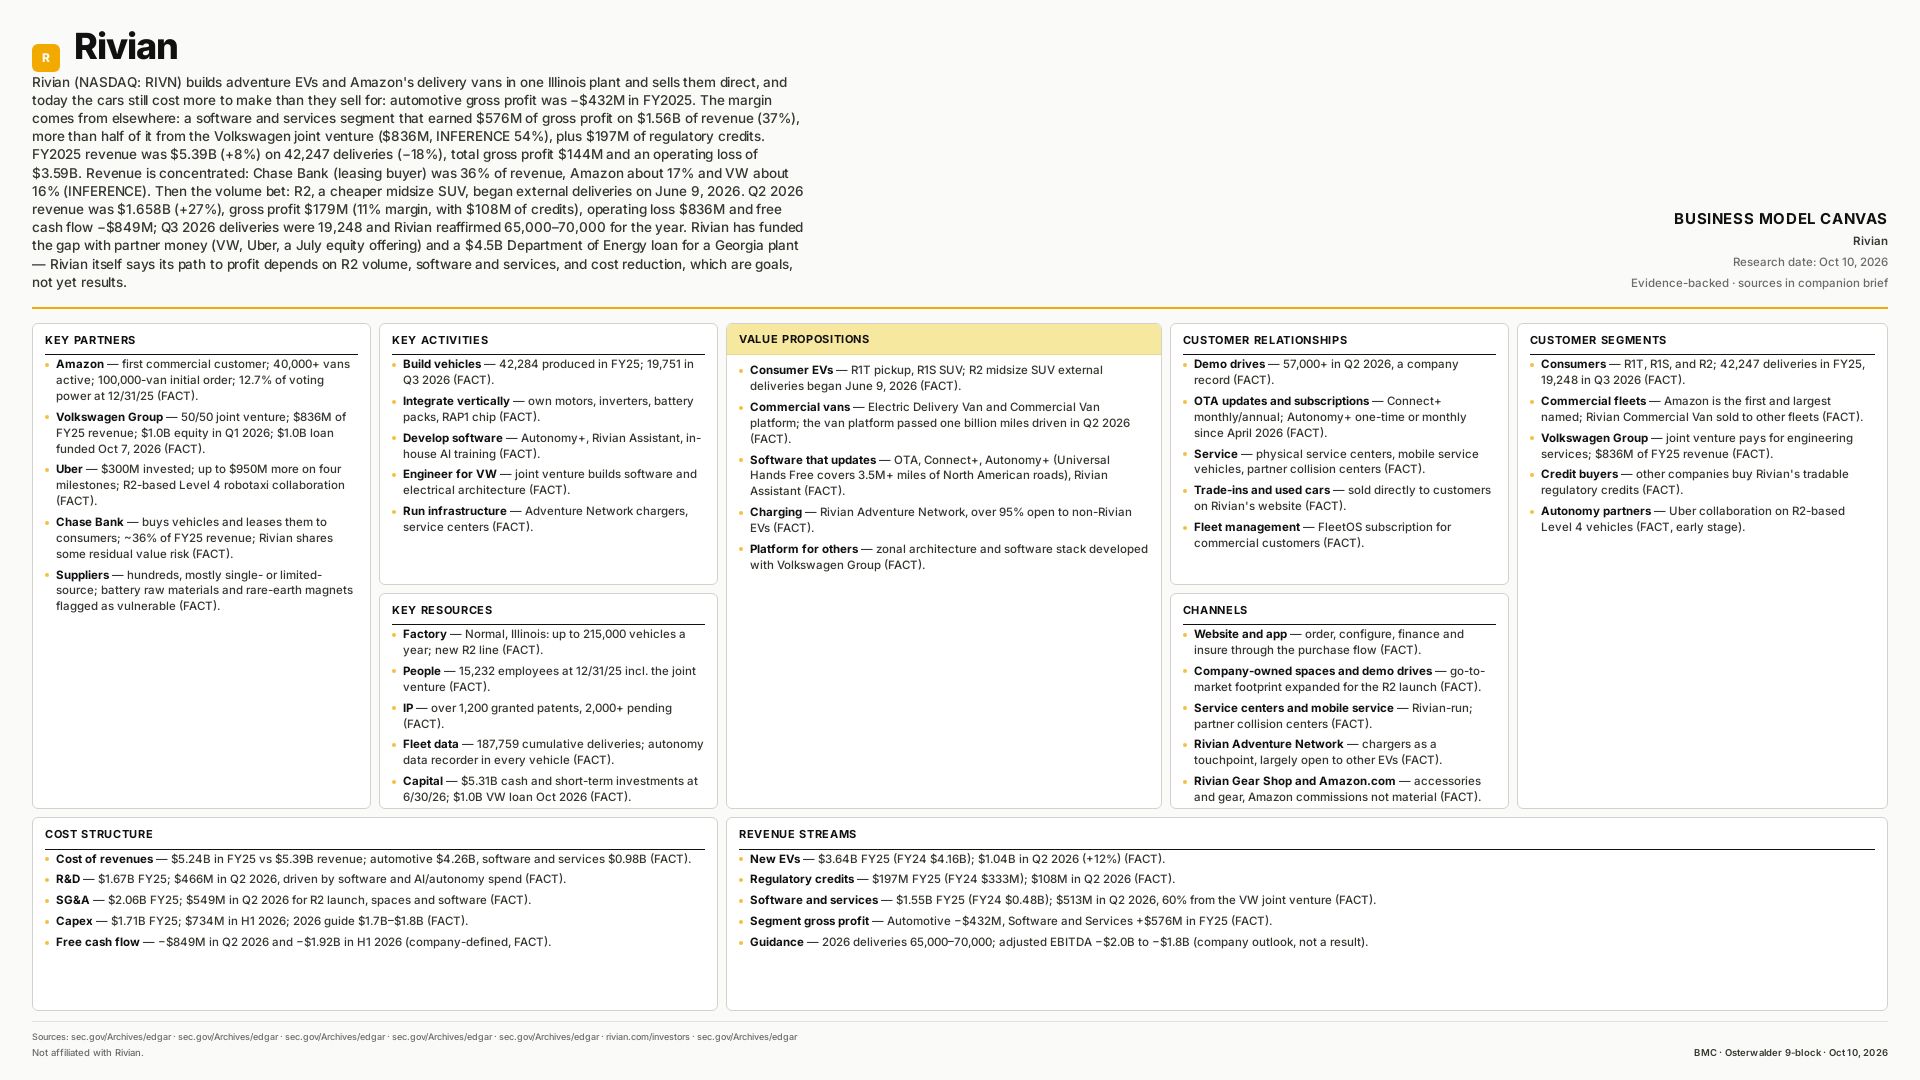

Rivian
Adventure EVs and Amazon vans sold direct at a gross loss, with a Volkswagen software joint venture and regulatory credits supplying the margin: $5.39B FY25 revenue (+8%) = new EVs $3.64B + credits $197M + software and services $1.55B → automotive gross loss $432M vs software and services gross profit $576M, $3.59B operating loss → R2 deliveries began June 2026: Q2 revenue $1.66B (+27%), 11% gross margin, free cash flow −$849M.
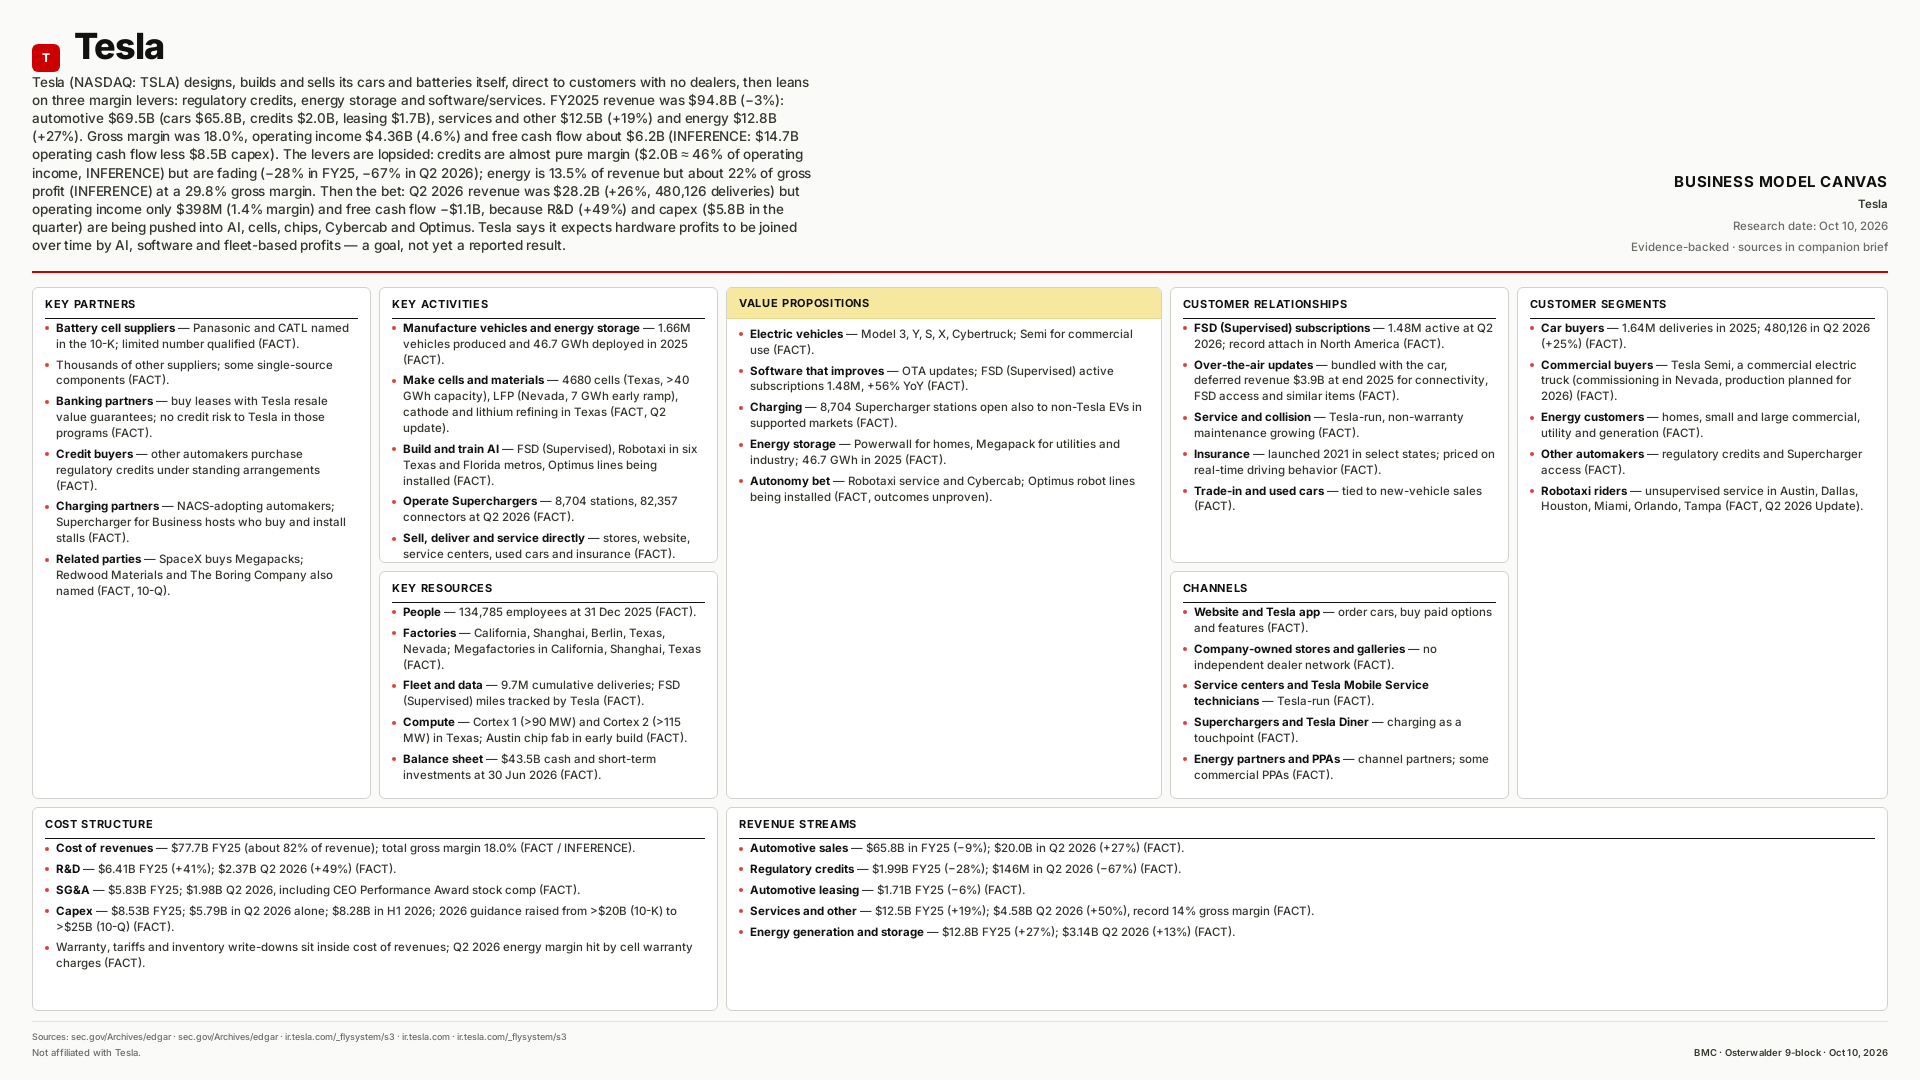

Tesla
Vertically integrated EV + energy hardware sold direct, with credits, storage and software as margin levers: $94.8B FY25 revenue (−3%) = cars $65.8B + credits $2.0B + leasing $1.7B + services $12.5B (+19%) + energy $12.8B (+27%) → 18.0% gross margin, $4.36B operating income, credits ≈ 46% of it, energy 29.8% GM → R&D +49% and $5.8B capex in Q2 2026 → revenue $28.2B (+26%) but operating margin 1.4%, free cash flow −$1.1B.
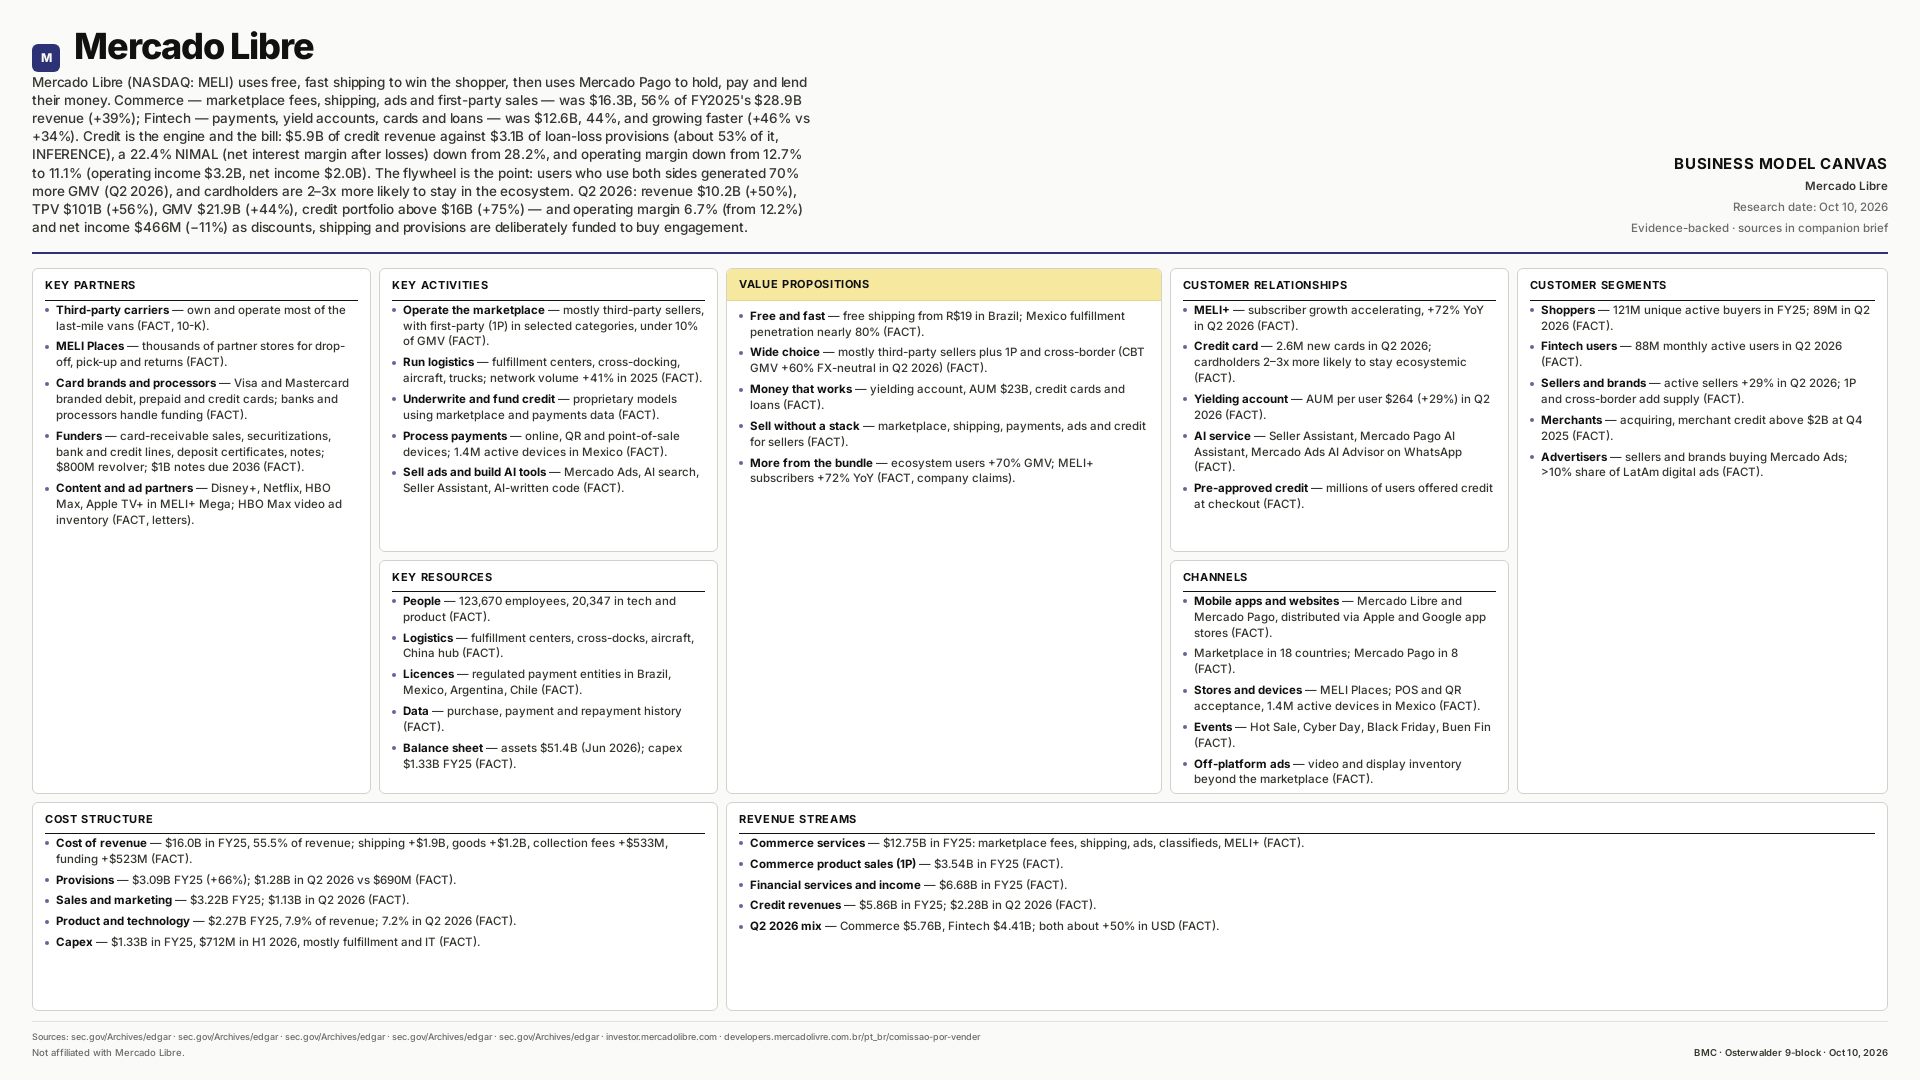

Mercado Libre
Free shipping wins the shopper, Mercado Pago holds, pays and lends: Commerce $16.3B (56%) + Fintech $12.6B (44%) = $28.9B FY25 revenue (+39%) on $65.0B GMV and $277.8B TPV → credit revenue $5.9B vs $3.1B of provisions (~53%), NIMAL 28.2% → 22.4% → operating margin 12.7% → 11.1% ($3.2B operating income) → Q2 2026 revenue $10.2B (+50%), credit book above $16B (+75%), operating margin 6.7%.
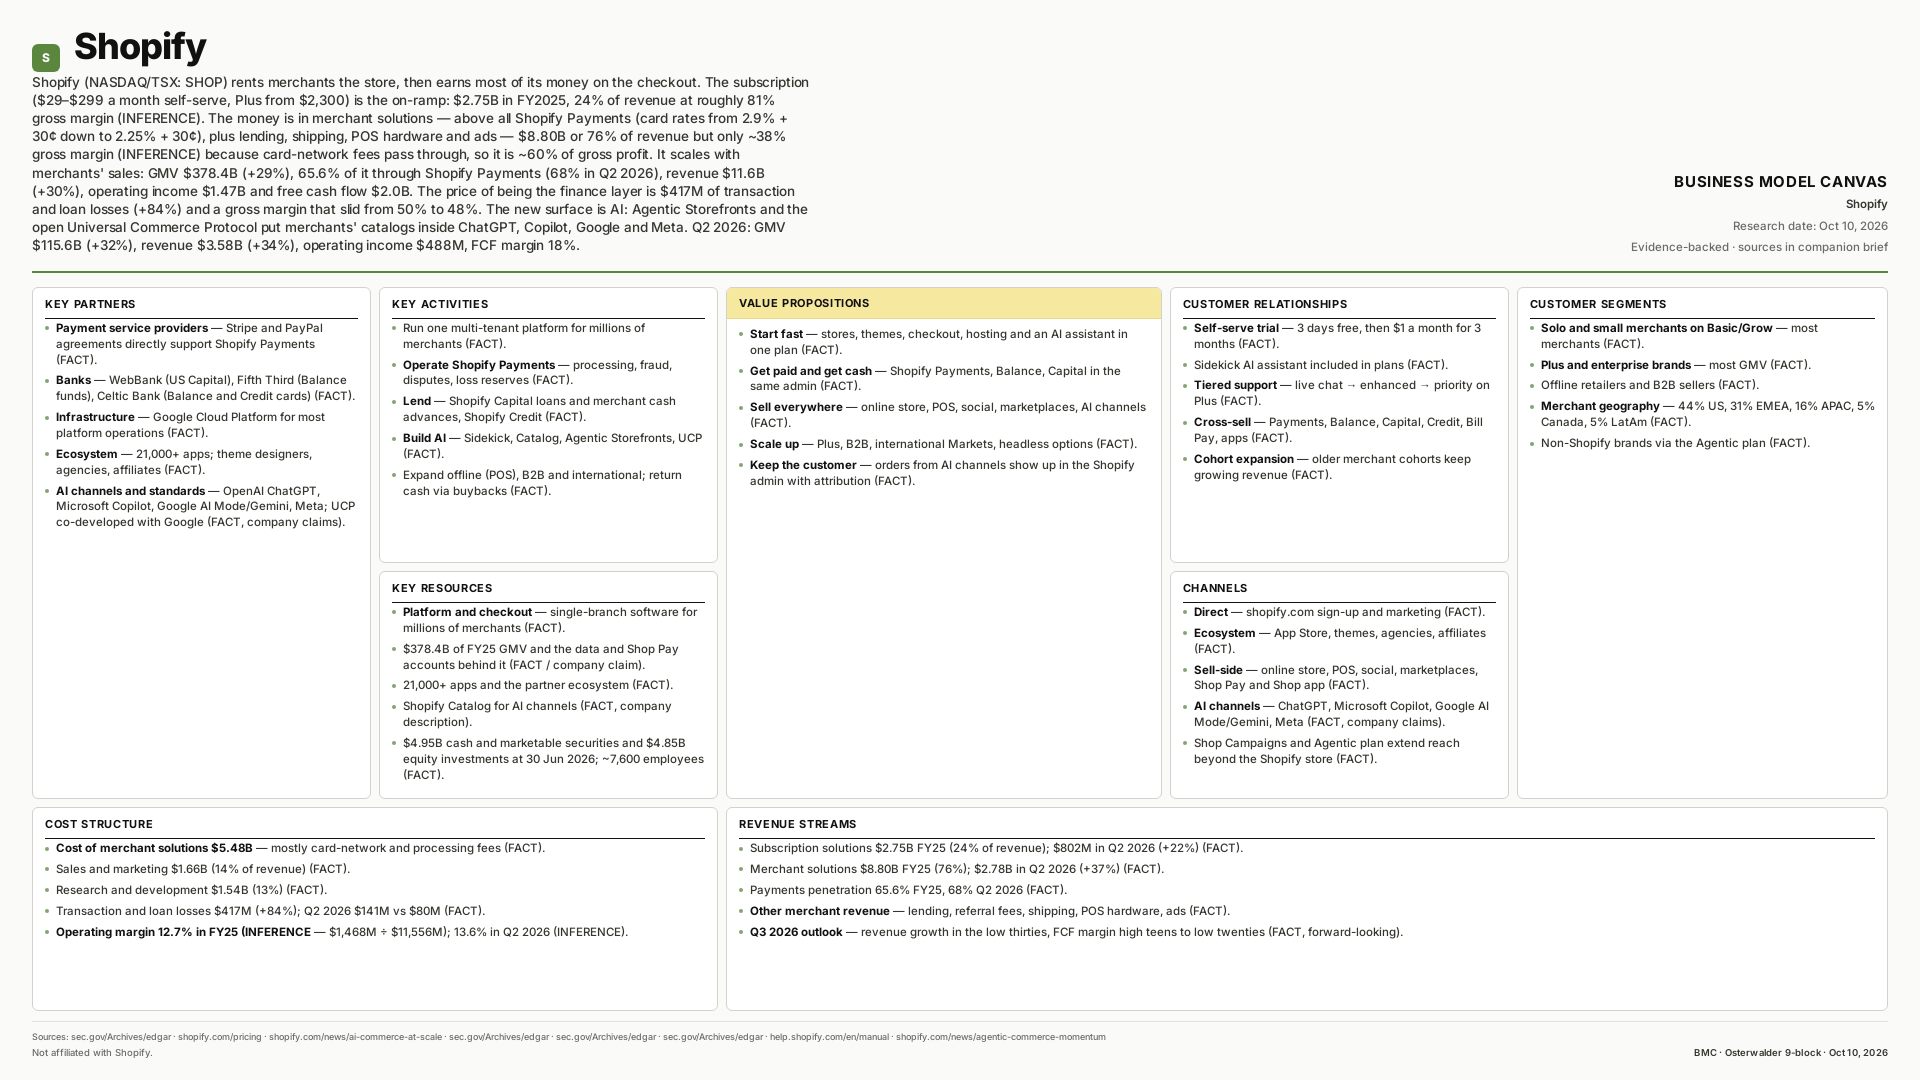

Shopify
Rent the store, rake the checkout: a $29–$2,300+/mo subscription ($2.75B, 24% of revenue, ~81% gross margin) feeds Shopify Payments and lending — merchant solutions $8.80B (76% of revenue, ~38% margin, ~60% of gross profit) on $378.4B of GMV (+29%), 65.6% via Payments → $11.6B FY25 revenue (+30%), $1.47B operating income, $2.0B FCF → $417M of transaction and loan losses (+84%) → Q2 2026 revenue $3.58B (+34%) and AI-agent selling (ChatGPT, Copilot, Google, Meta).
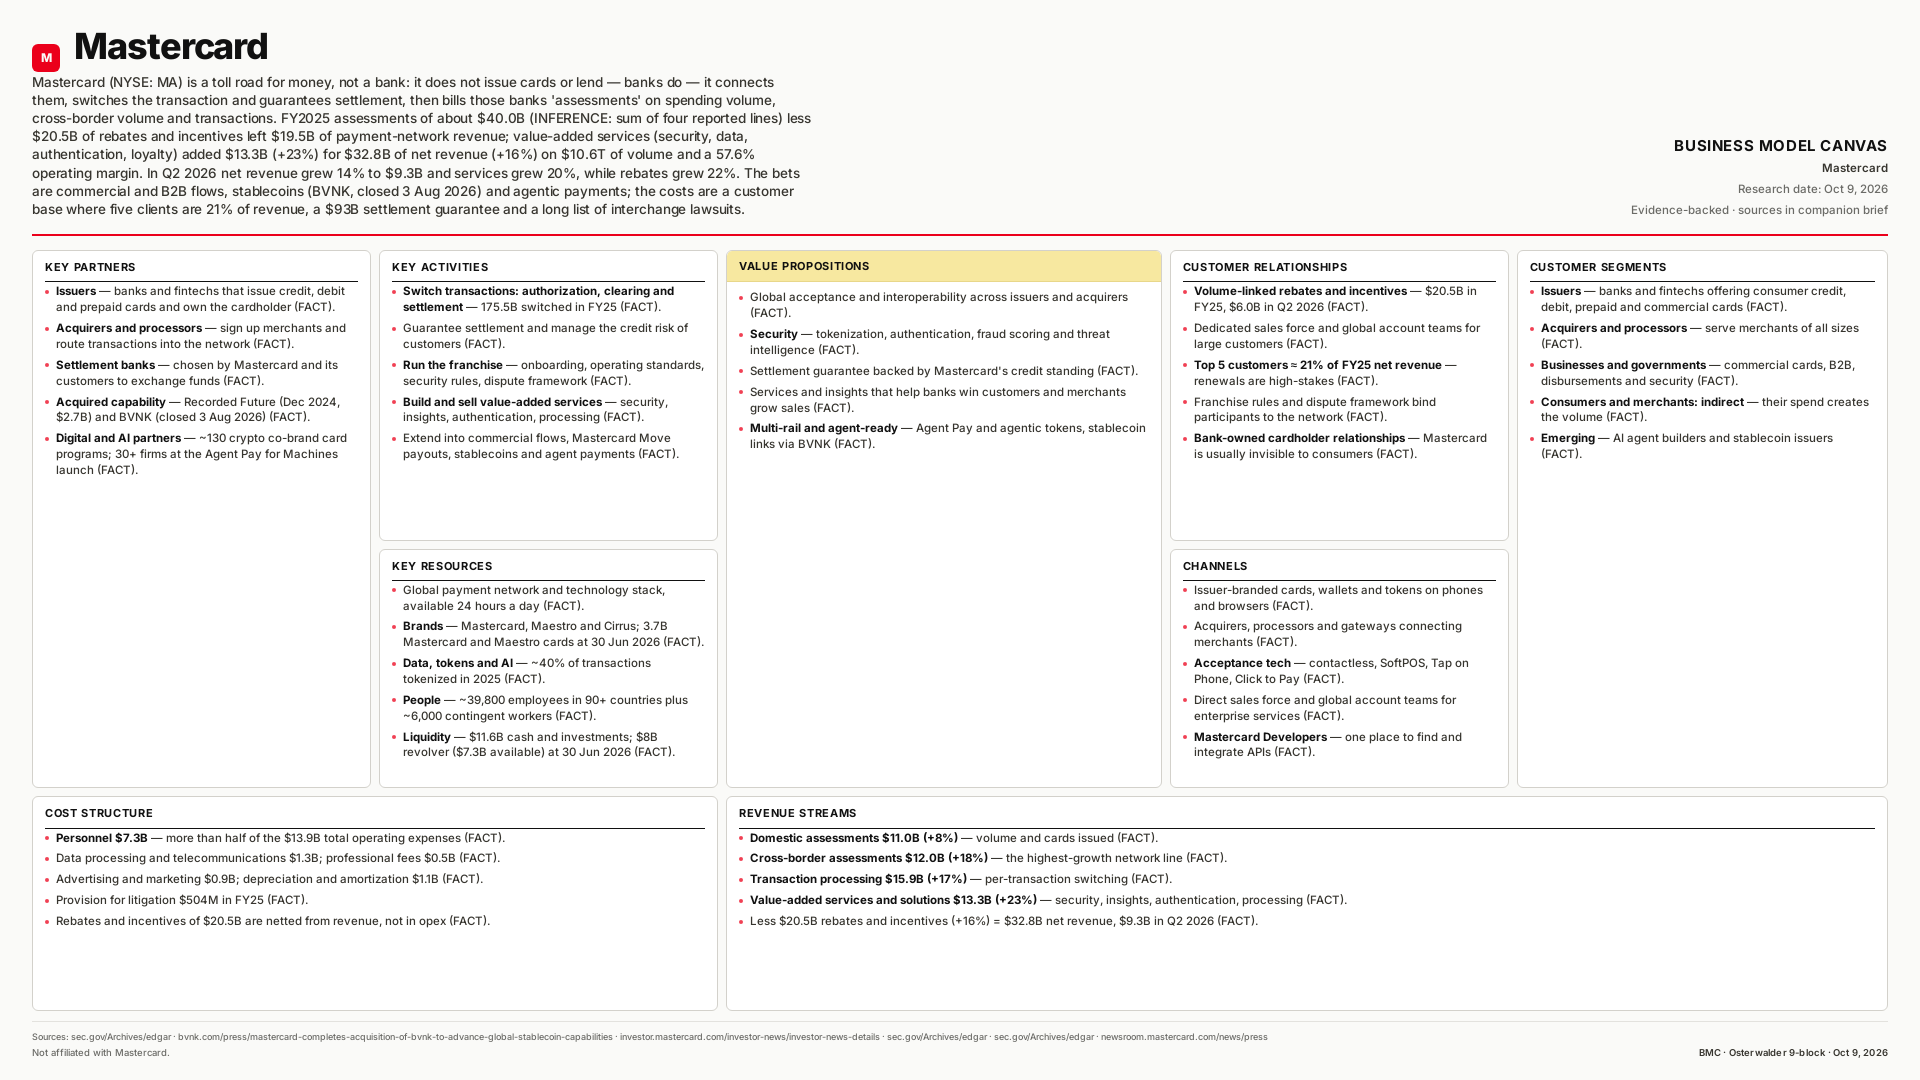

Mastercard
Network that never lends: ~$40.0B of assessments less $20.5B of rebates and incentives = $19.5B of payment-network revenue, plus $13.3B of value-added services (+23%) = $32.8B FY25 net revenue (+16%) on $10.6T volume (57.6% operating margin) → Q2 2026 $9.3B (+14%), rebates +22% → stablecoins (BVNK), agentic payments, and interchange litigation.
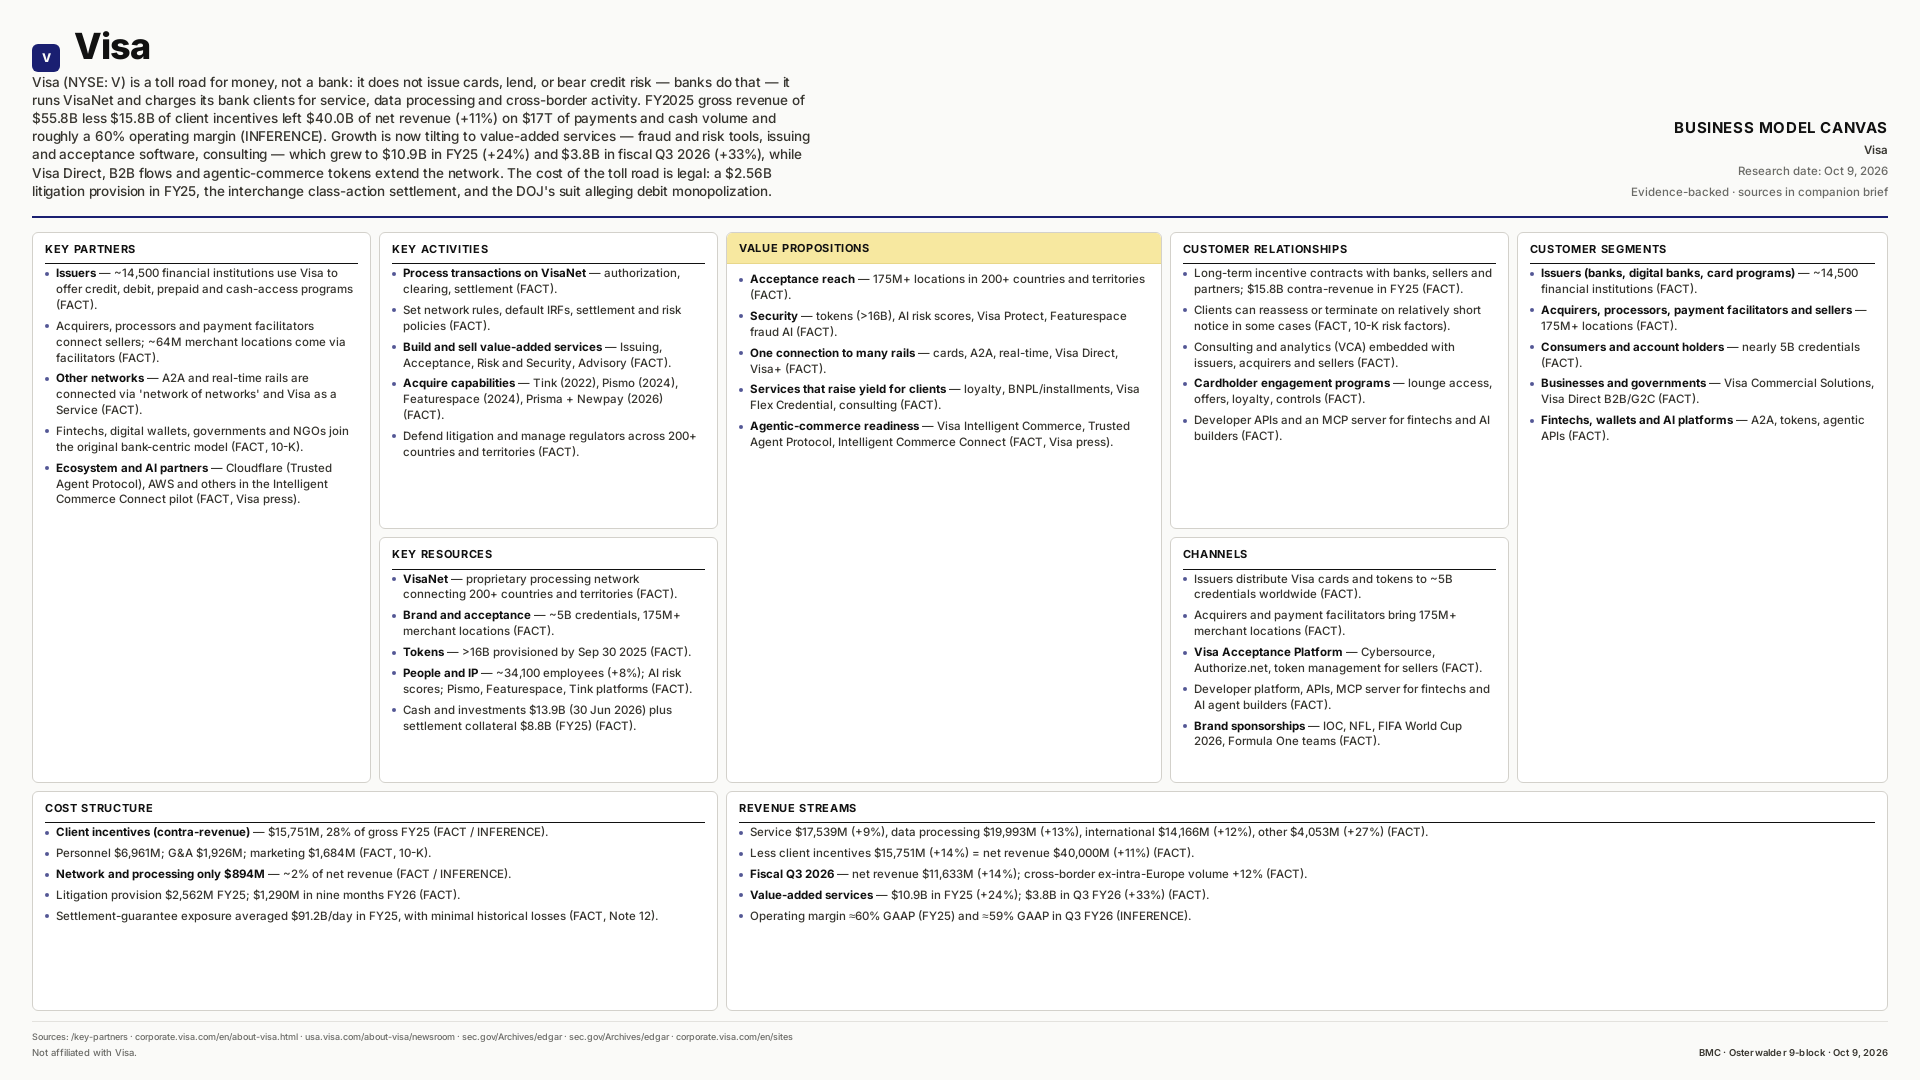

Visa
Network that never lends or bears credit risk: $55.8B of fees from banks less $15.8B of client incentives = $40.0B FY25 net revenue (+11%) on $17T volume (~60% operating margin) → value-added services $10.9B (+24%), $3.8B in fiscal Q3 2026 (+33%), plus Visa Direct, B2B and agentic-commerce tokens → $2.56B litigation provision, interchange settlement and the DOJ debit suit.
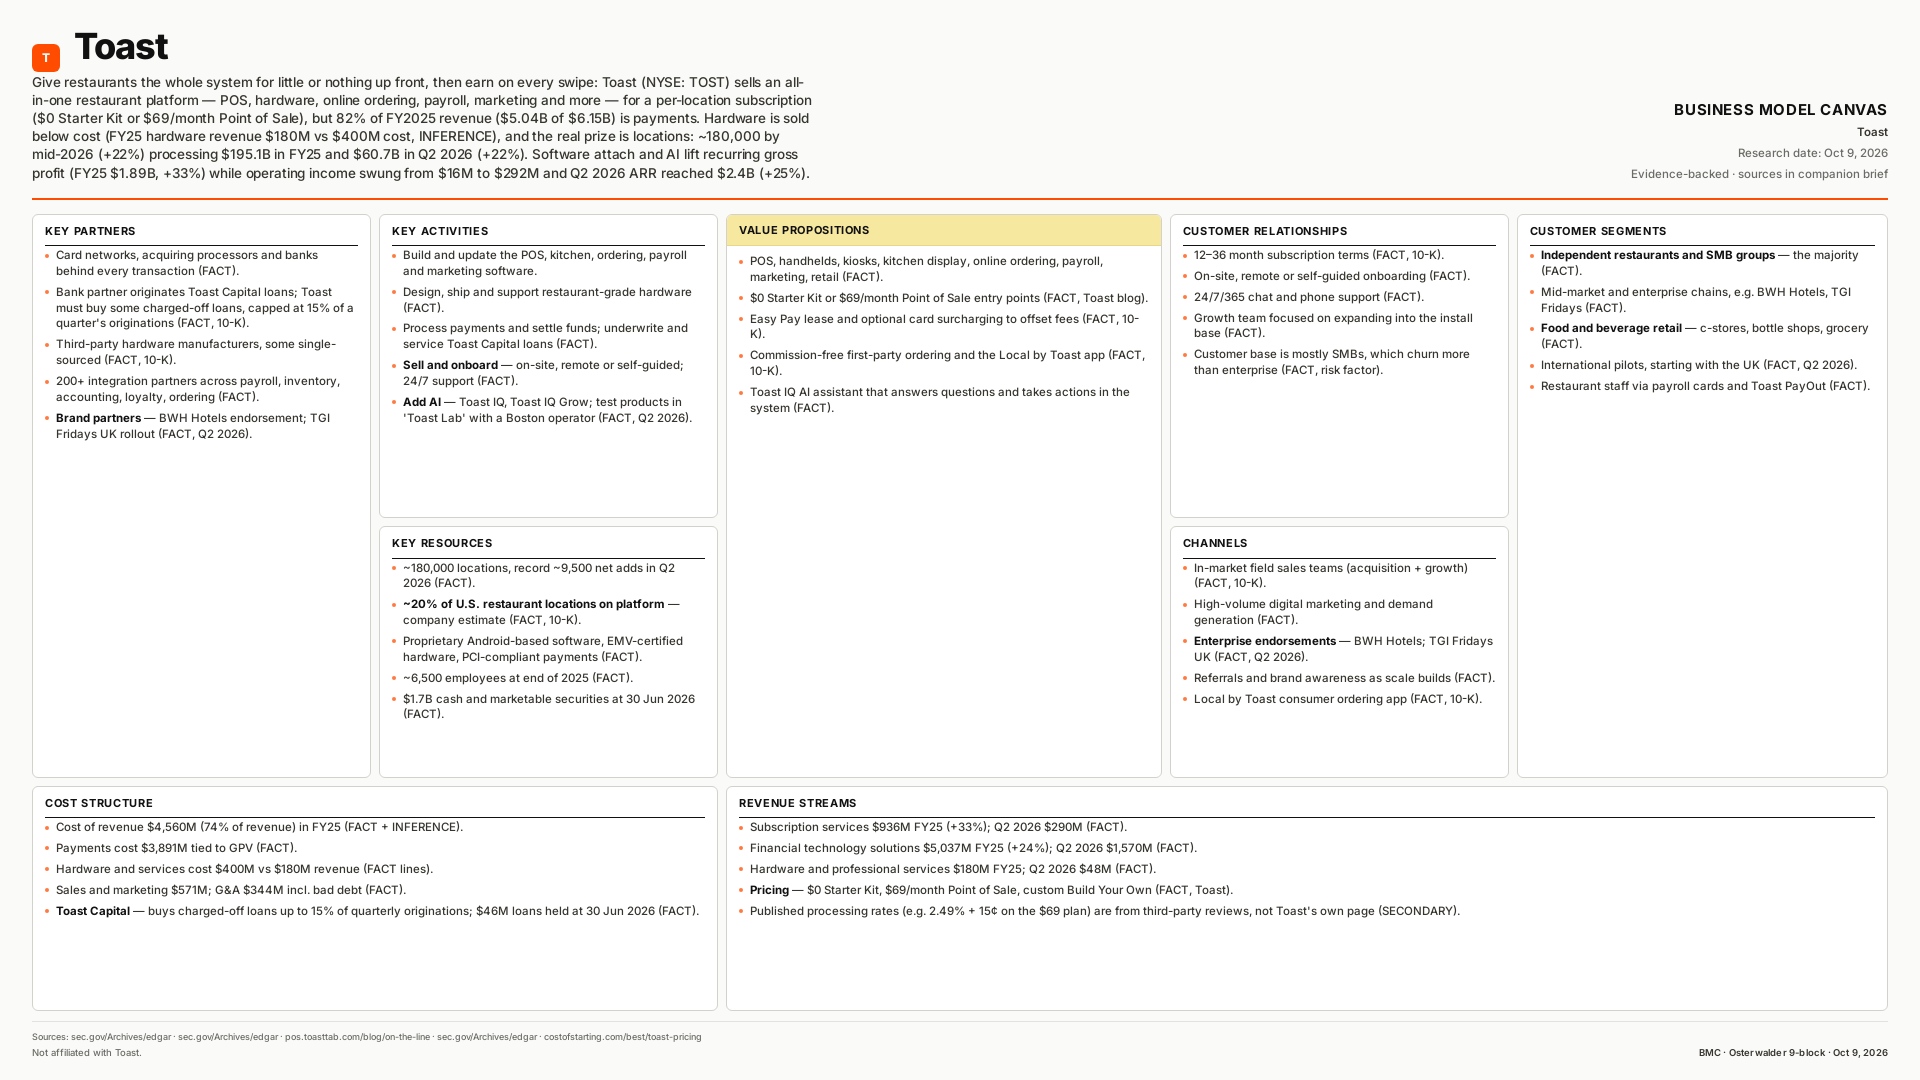

Toast
Cheap all-in-one restaurant system ($0 Starter Kit or $69/month per location, hardware sold below cost) → payments on every swipe are 82% of FY25 revenue ($5.04B of $6.15B) but only ~0.59% of volume as gross profit → ~180,000 locations (+22%), $60.7B Q2 volume and software/AI attach lift recurring gross profit +33% to $1.89B, operating income $16M → $292M, Q2 2026 ARR $2.41B (+25%).
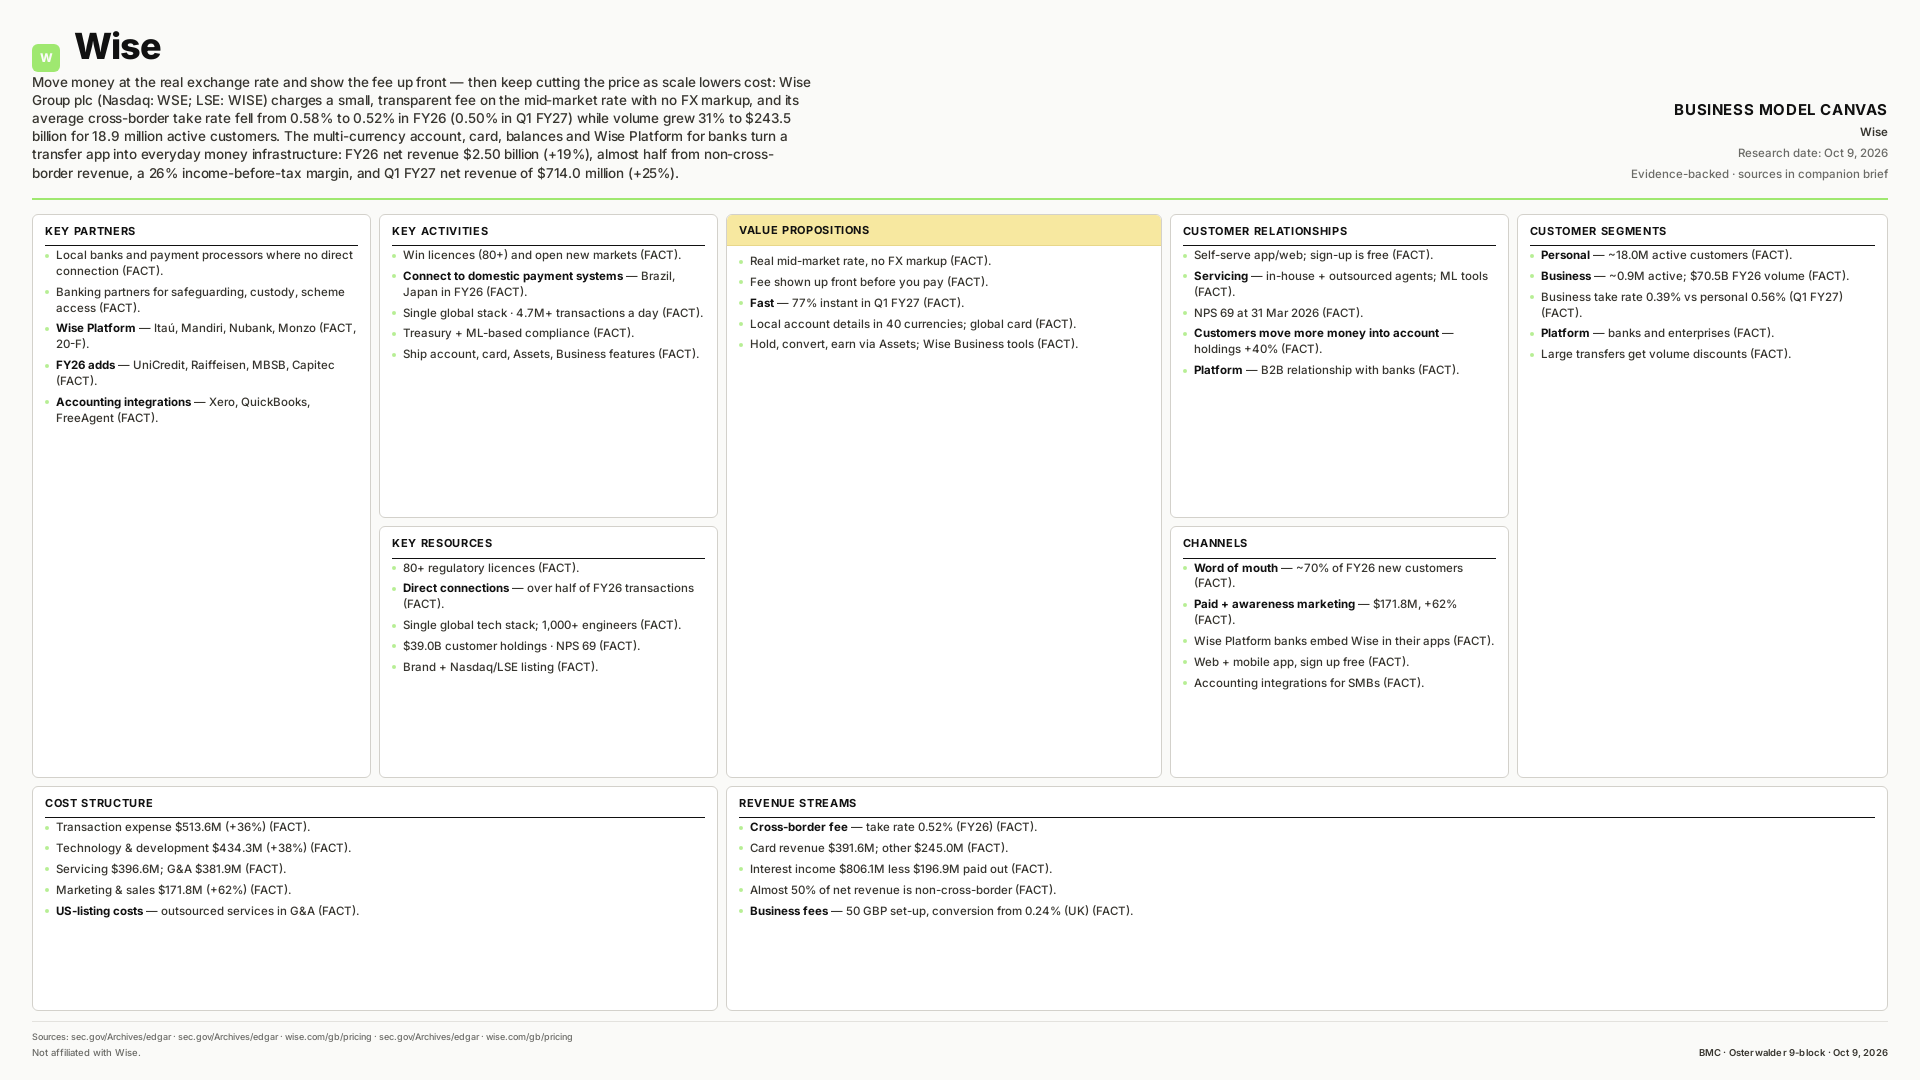

Wise
Mid-market rate + small upfront fee → take rate cut from 0.58% to 0.52% in FY26 (0.50% Q1 FY27) as direct payment-system connections lower cost → $243.5B cross-border volume (+31%) from 18.9M active customers, ~70% of new ones by word of mouth → account, card, balances and Wise Platform lift net revenue to $2.50B (+19%) with a 26% pre-tax margin; Q1 FY27 net revenue $714.0M (+25%).
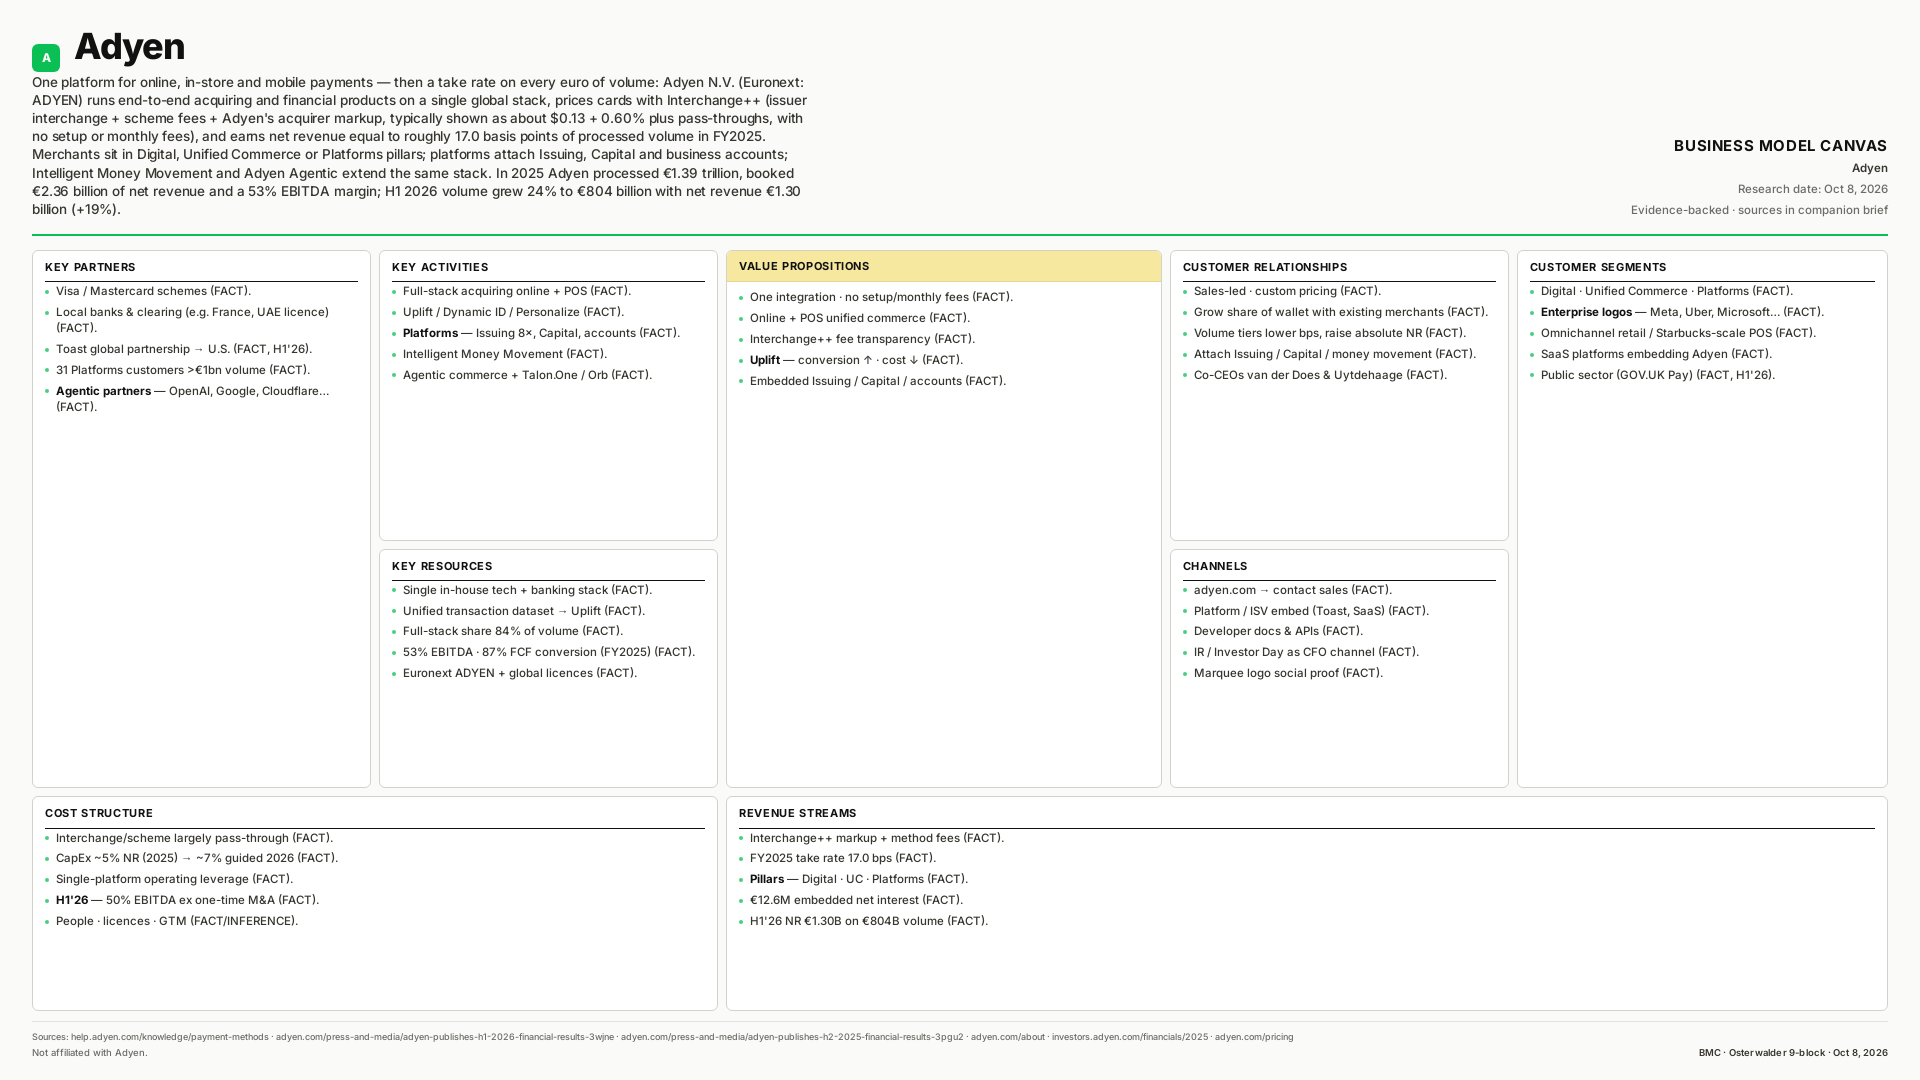

Adyen
Unified commerce on one global stack → Interchange++ processing take rate (~17.0 bps of volume in FY2025) → Digital / Unified Commerce / Platforms pillars with Issuing, Capital and Intelligent Money Movement attach → €1.39T processed volume, €2.36B net revenue and 53% EBITDA margin in 2025; H1 2026 volume +24% to €804B with net revenue €1.30B (+19%).
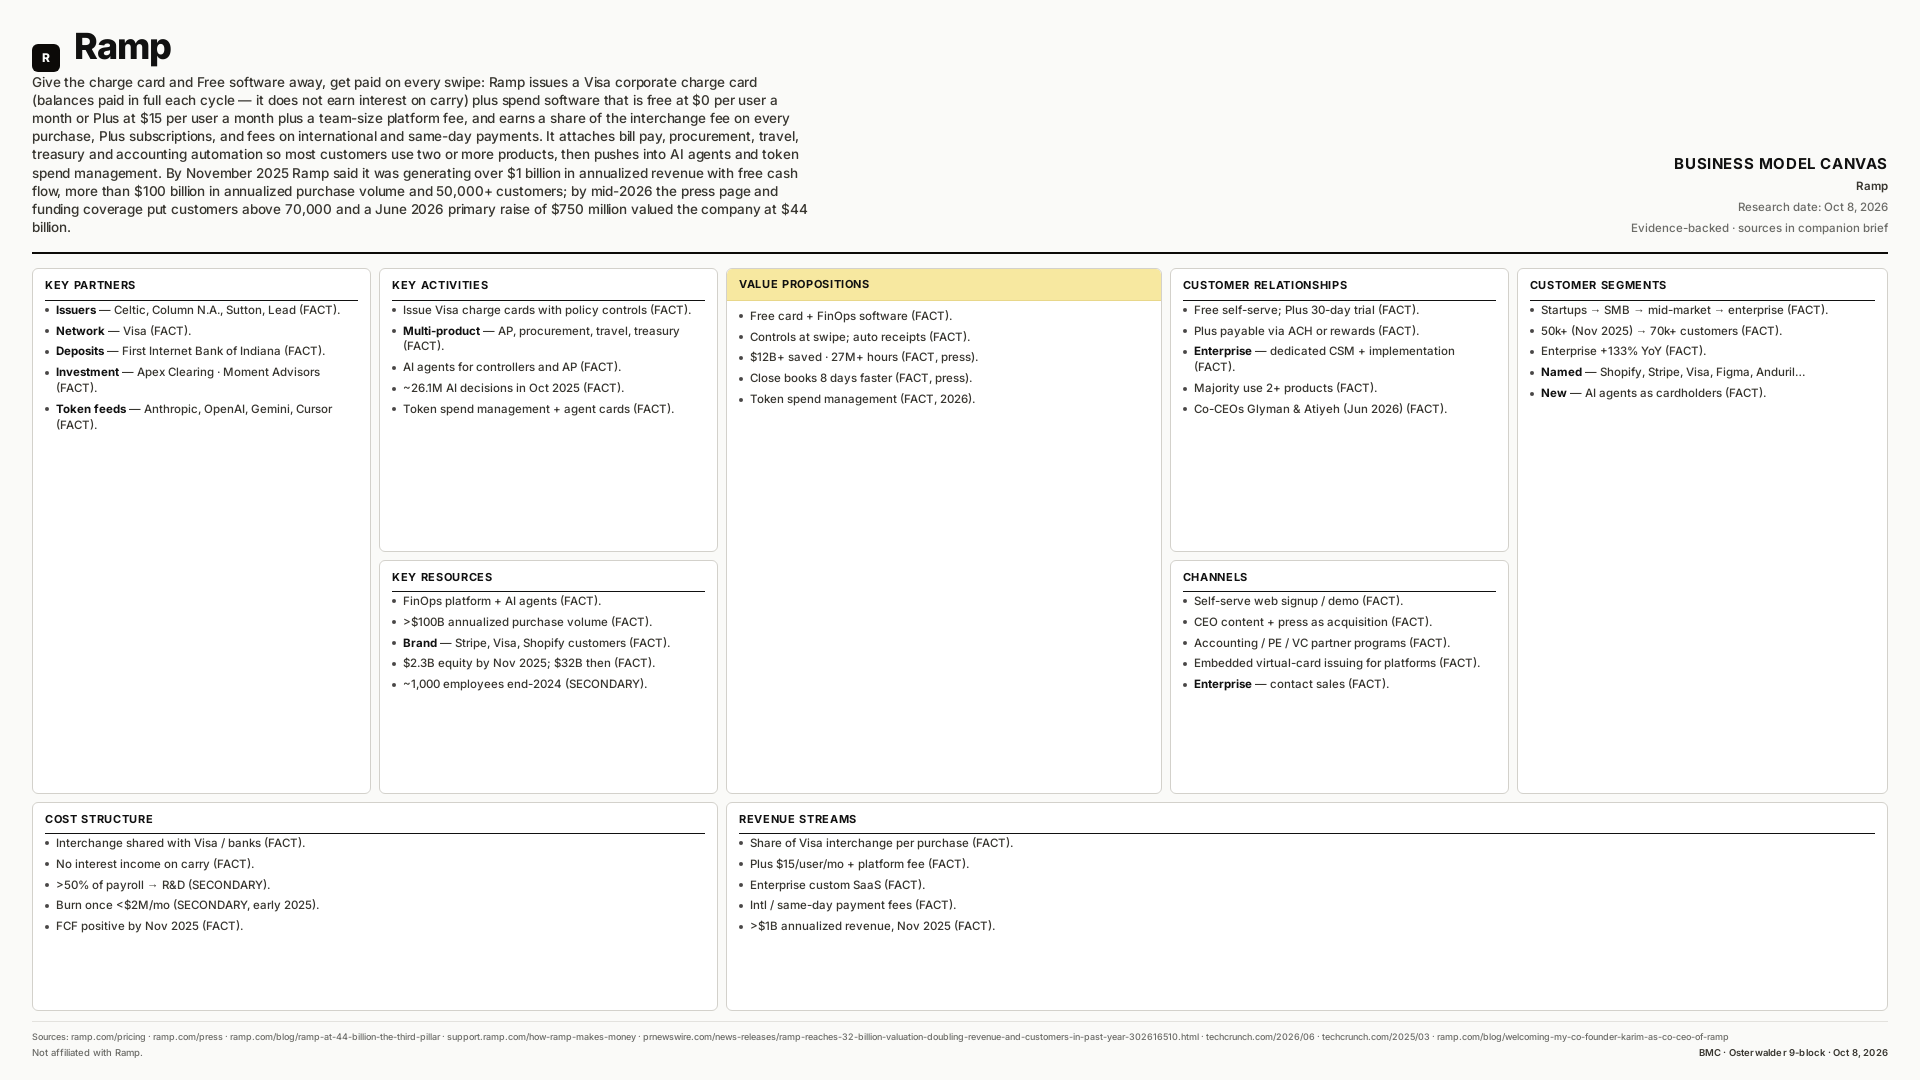

Ramp
Savings-first corporate charge card + FinOps software: Free at $0/user or Plus at $15/user → Ramp earns a share of Visa interchange on every purchase (no interest on carry), plus SaaS and payment fees → attach bill pay, procurement, travel, treasury → >$1B annualized revenue and free cash flow by Nov 2025, 70,000+ customers, >$100B purchase volume → June 2026 raise at $44B valuation with a push into AI token spend management.
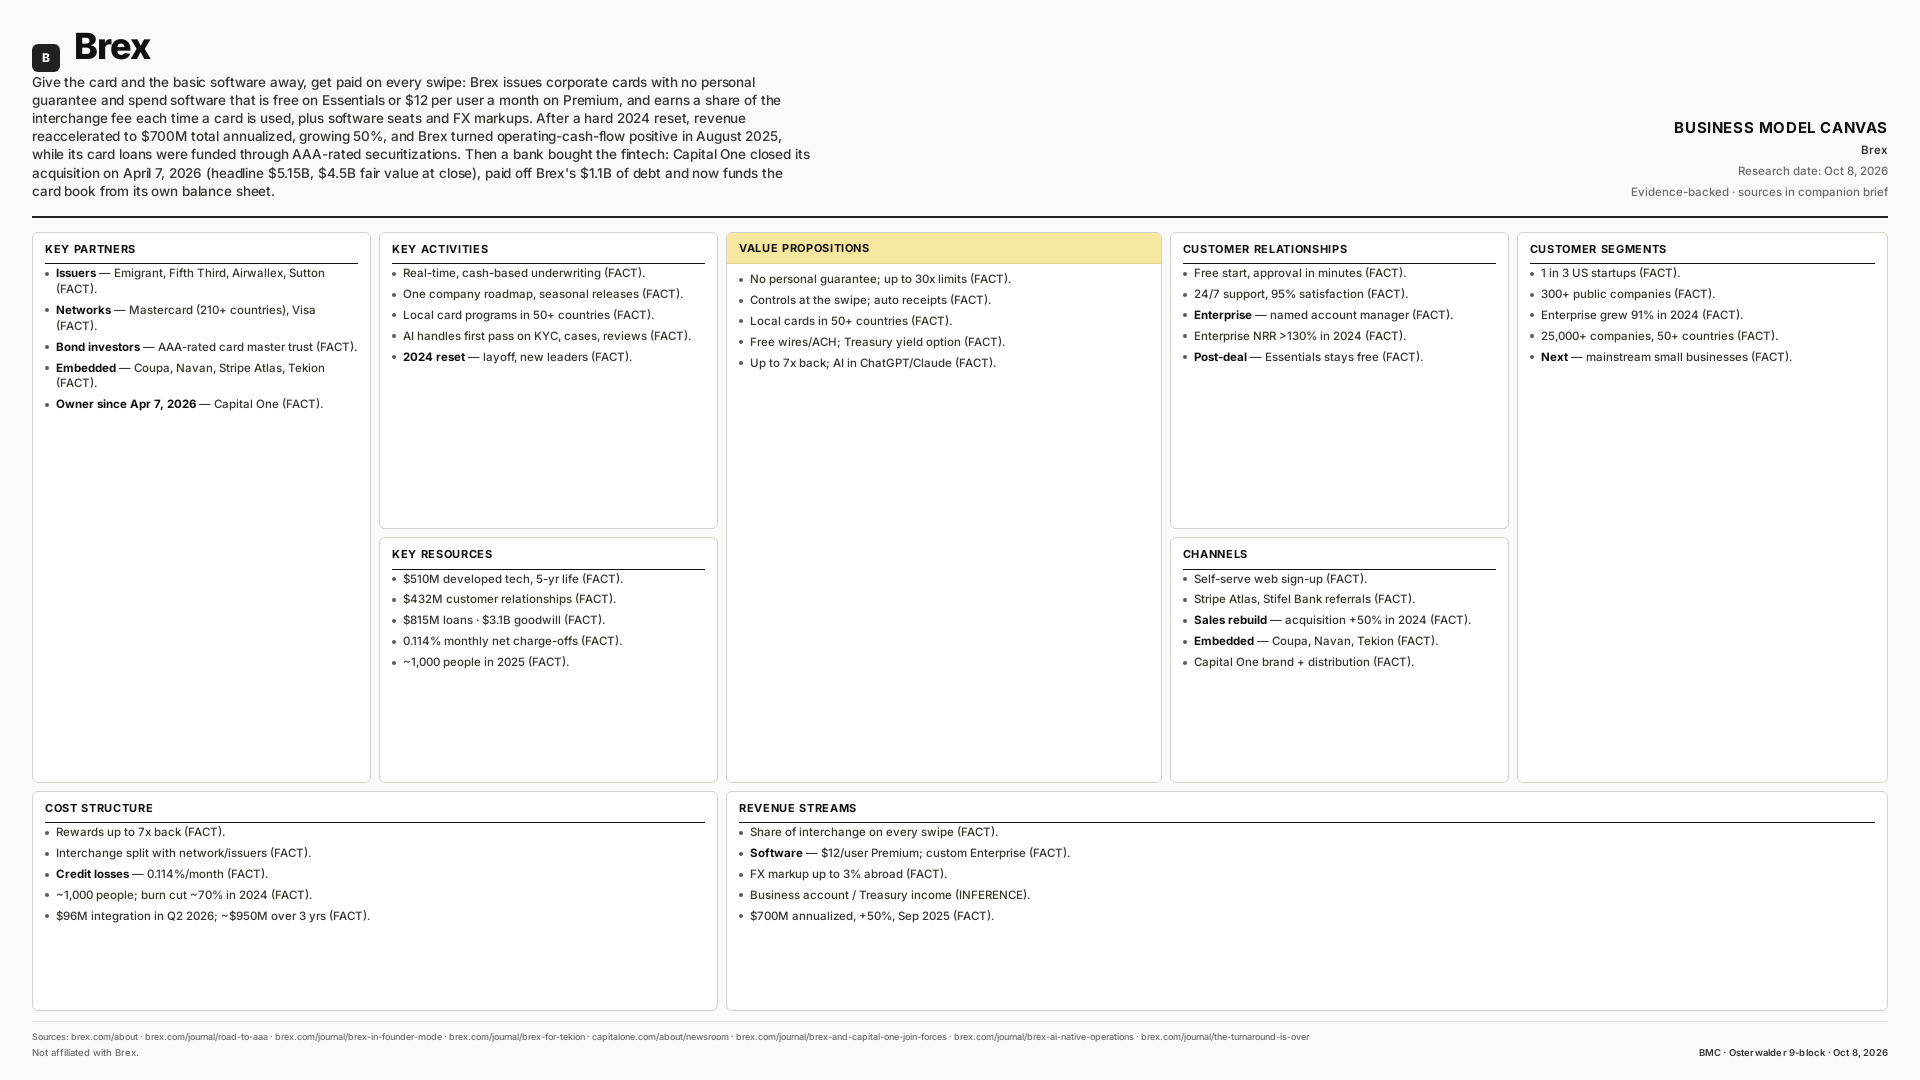

Brex
Free card, paid by the swipe: no-personal-guarantee corporate cards plus spend software at $0 (Essentials) or $12/user/month (Premium) → Brex earns a share of interchange on every transaction, plus seats and FX markups → 2024 reset, then $700M annualized revenue growing 50% and first positive operating cash flow (Aug 2025) → card loans funded through AAA-rated securitizations (0.114% monthly net charge-offs) → Capital One closes the acquisition Apr 7, 2026 ($5.15B headline, $4.5B fair value), pays off $1.1B of debt and books $3.1B of goodwill.
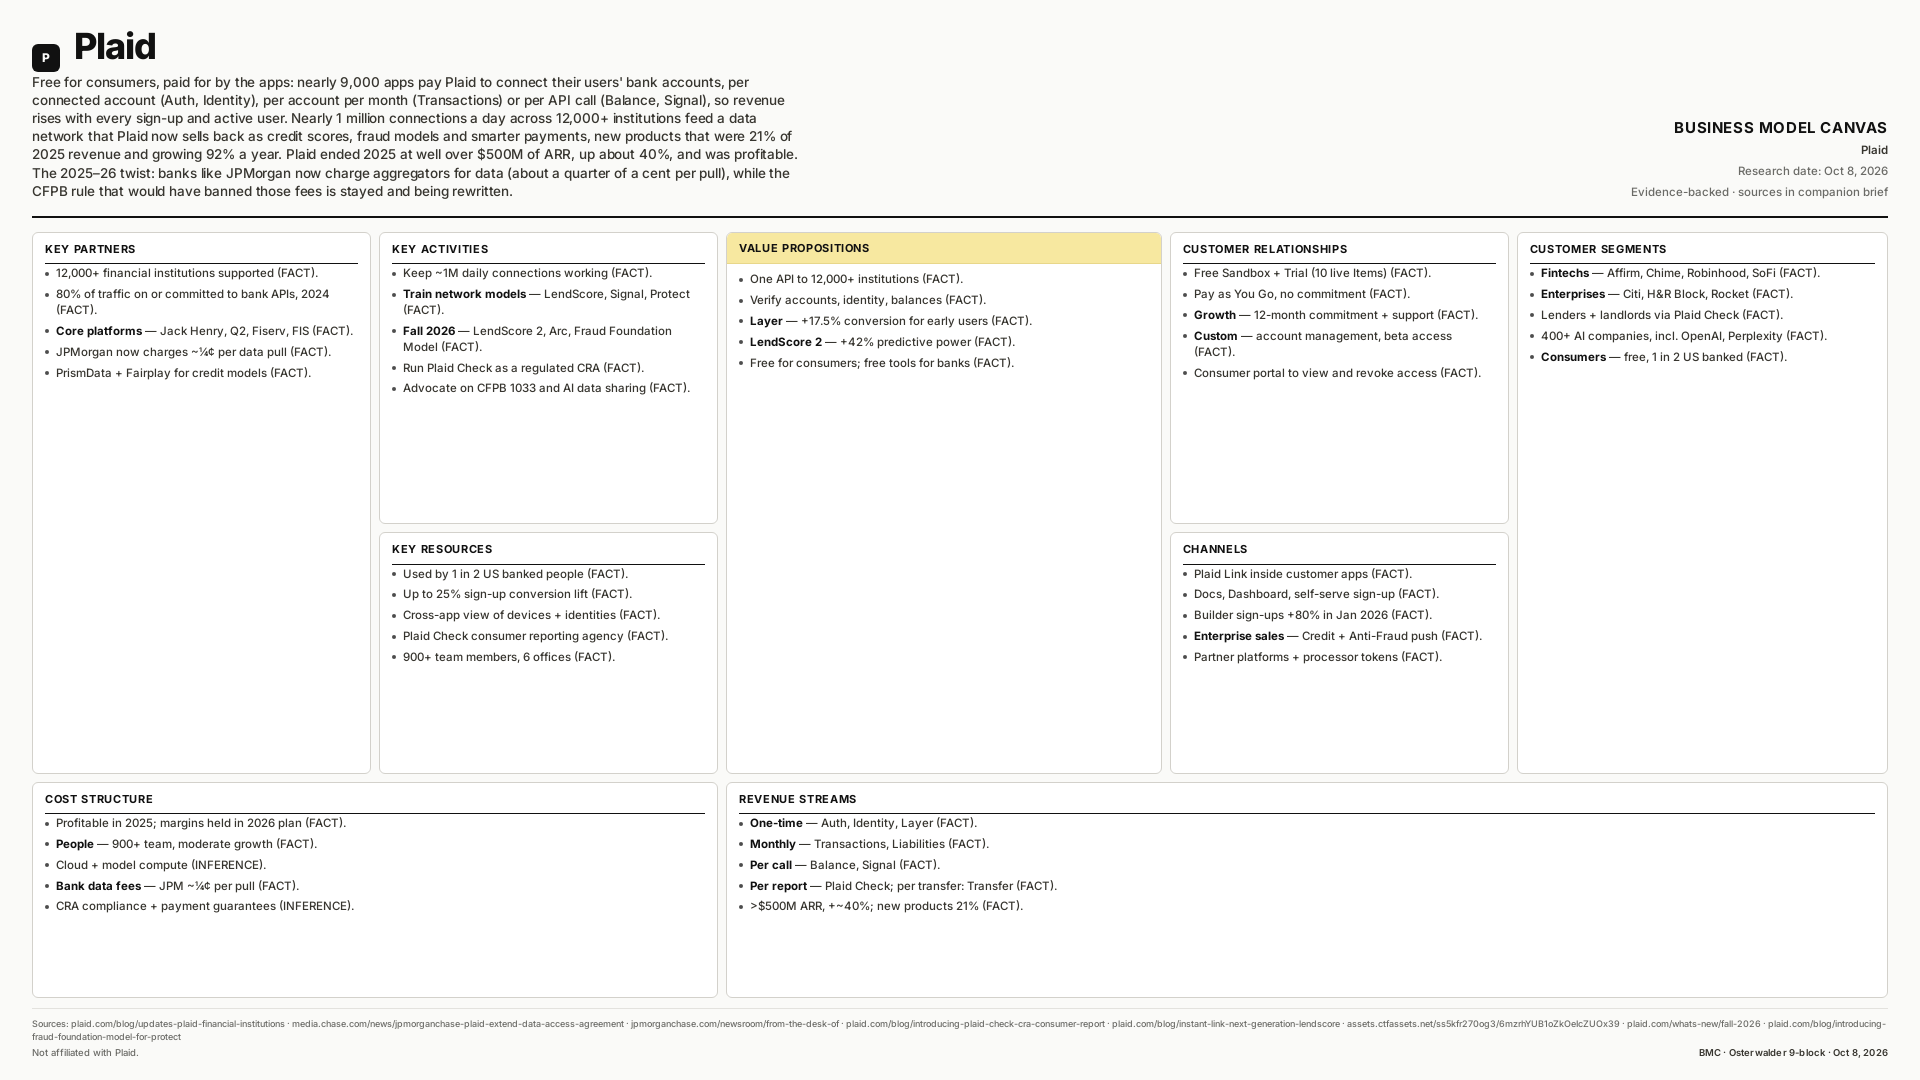

Plaid
Free for consumers, paid for by nearly 9,000 apps: one-time fees per connected account (Auth, Identity), monthly fees per account (Transactions) and per-call fees (Balance, Signal) → ~1M connections a day across 12,000+ institutions feed a network Plaid resells as credit scores, fraud models and smarter payments (21% of 2025 revenue, +92%/yr) → well over $500M ARR in Q4 2025, up ~40%, profitable → 2025–26: banks start charging aggregators for data (JPMorgan ~¼¢ per pull) while the CFPB 1033 rule is stayed and rewritten.
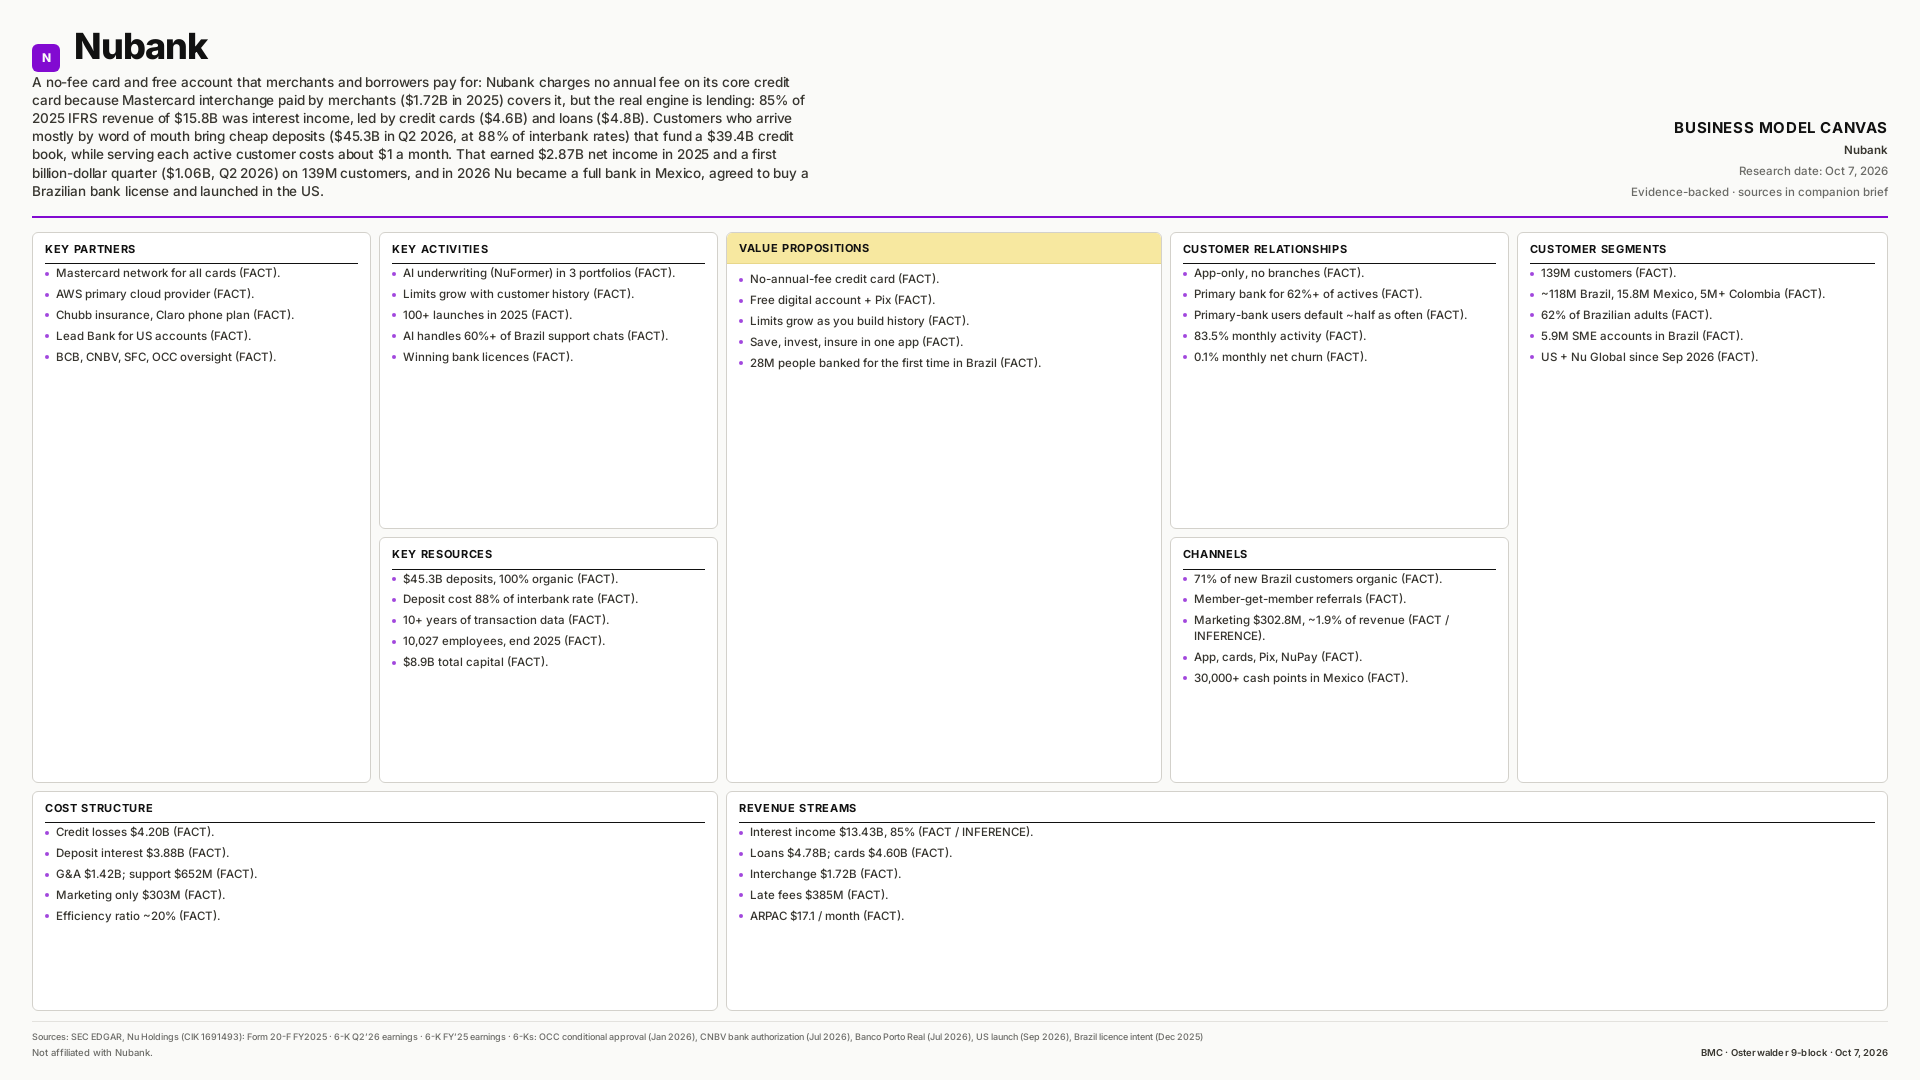

Nubank
A free account and no-annual-fee card paid for by merchants (Mastercard interchange $1.72B) and, mostly, borrowers: interest was 85% of 2025's $15.8B IFRS revenue (cards $4.6B, loans $4.8B) → word-of-mouth growth brings 100%-organic deposits ($45.3B at 88% of interbank rates) that fund a $39.4B credit book at ~$1/month cost to serve → $2.87B 2025 net income and a first $1B quarter (Q2'26) on 139M customers → 2026 full bank in Mexico, Brazil bank licence deal, US launch.
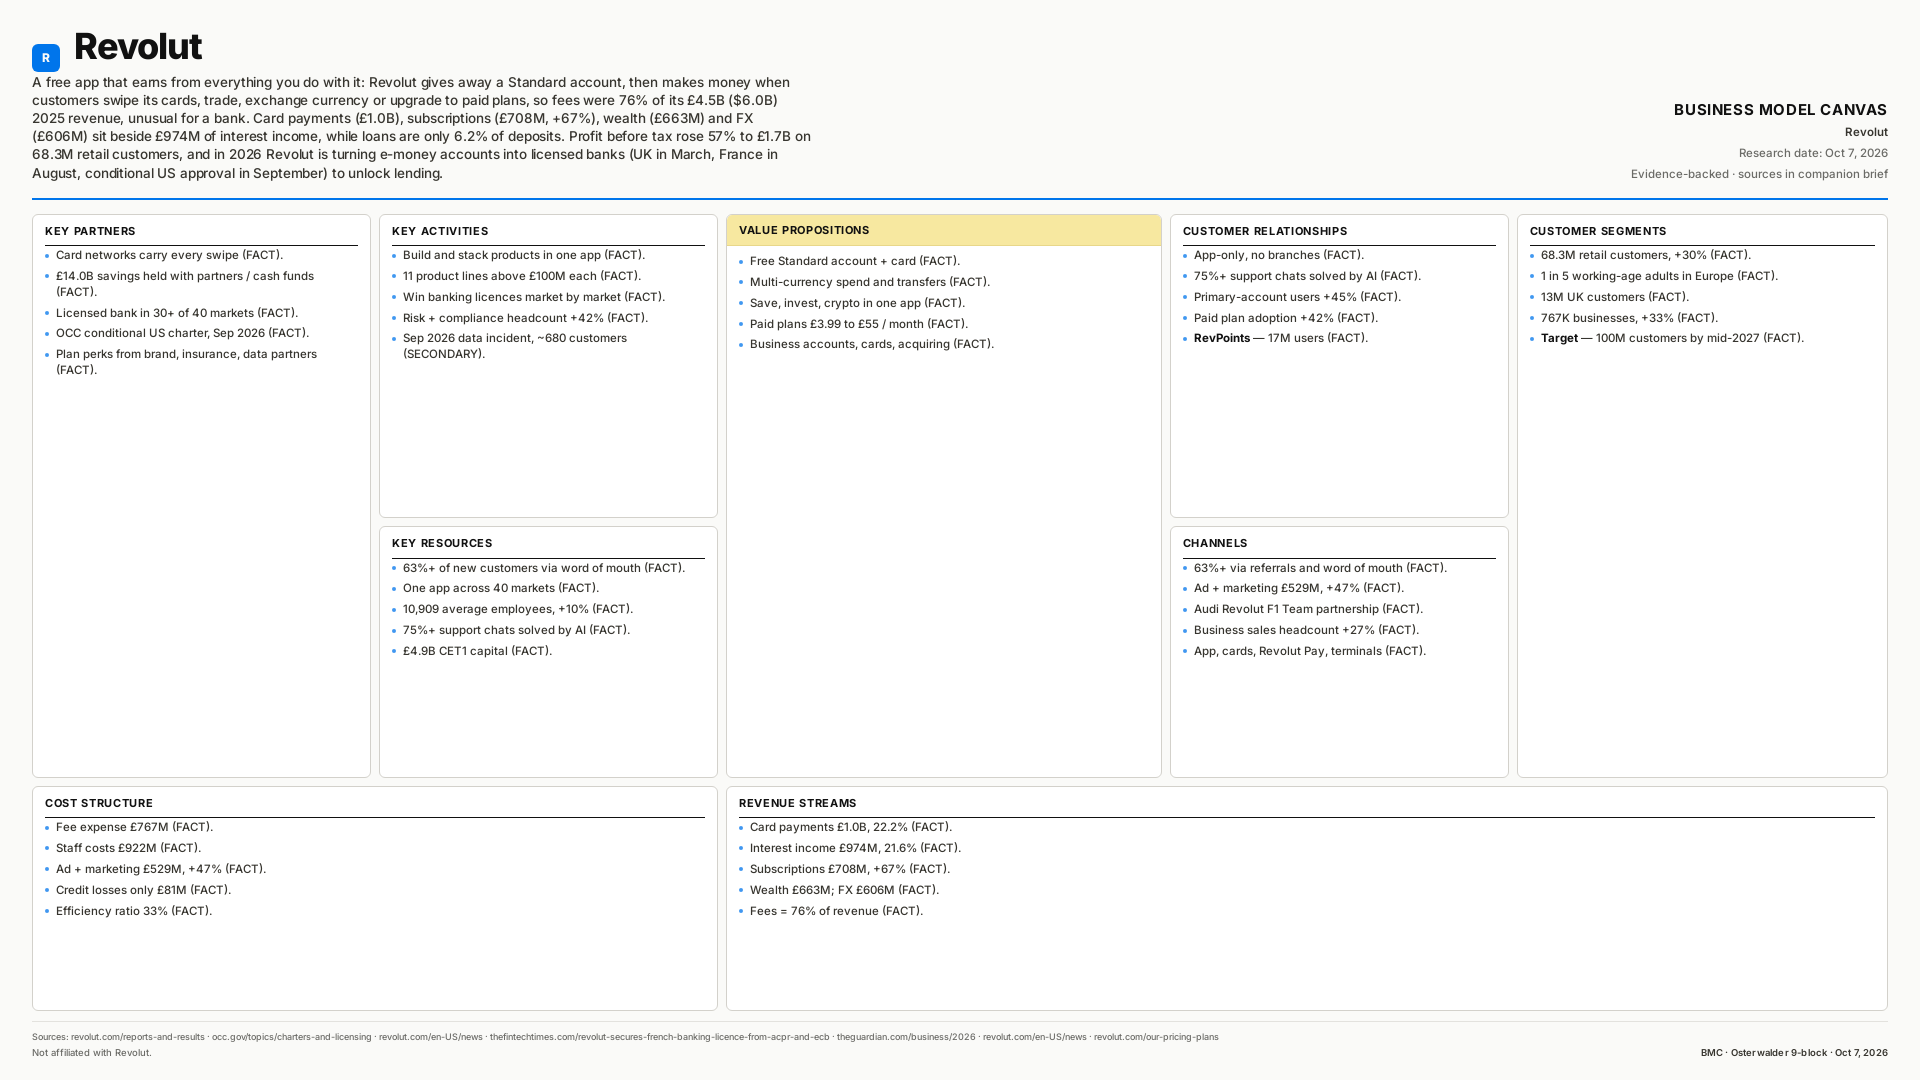

Revolut
A free app with many paid engines: fees were 76% of 2025's £4.5B revenue (card payments £1.0B, subscriptions £708M +67%, wealth £663M, FX £606M) → deposits mostly parked in cash and bonds, loans just 6.2% of deposits → PBT £1.7B +57% on 68.3M retail customers → 2026 shift from e-money to licensed banks (UK, France, conditional US) to unlock lending.
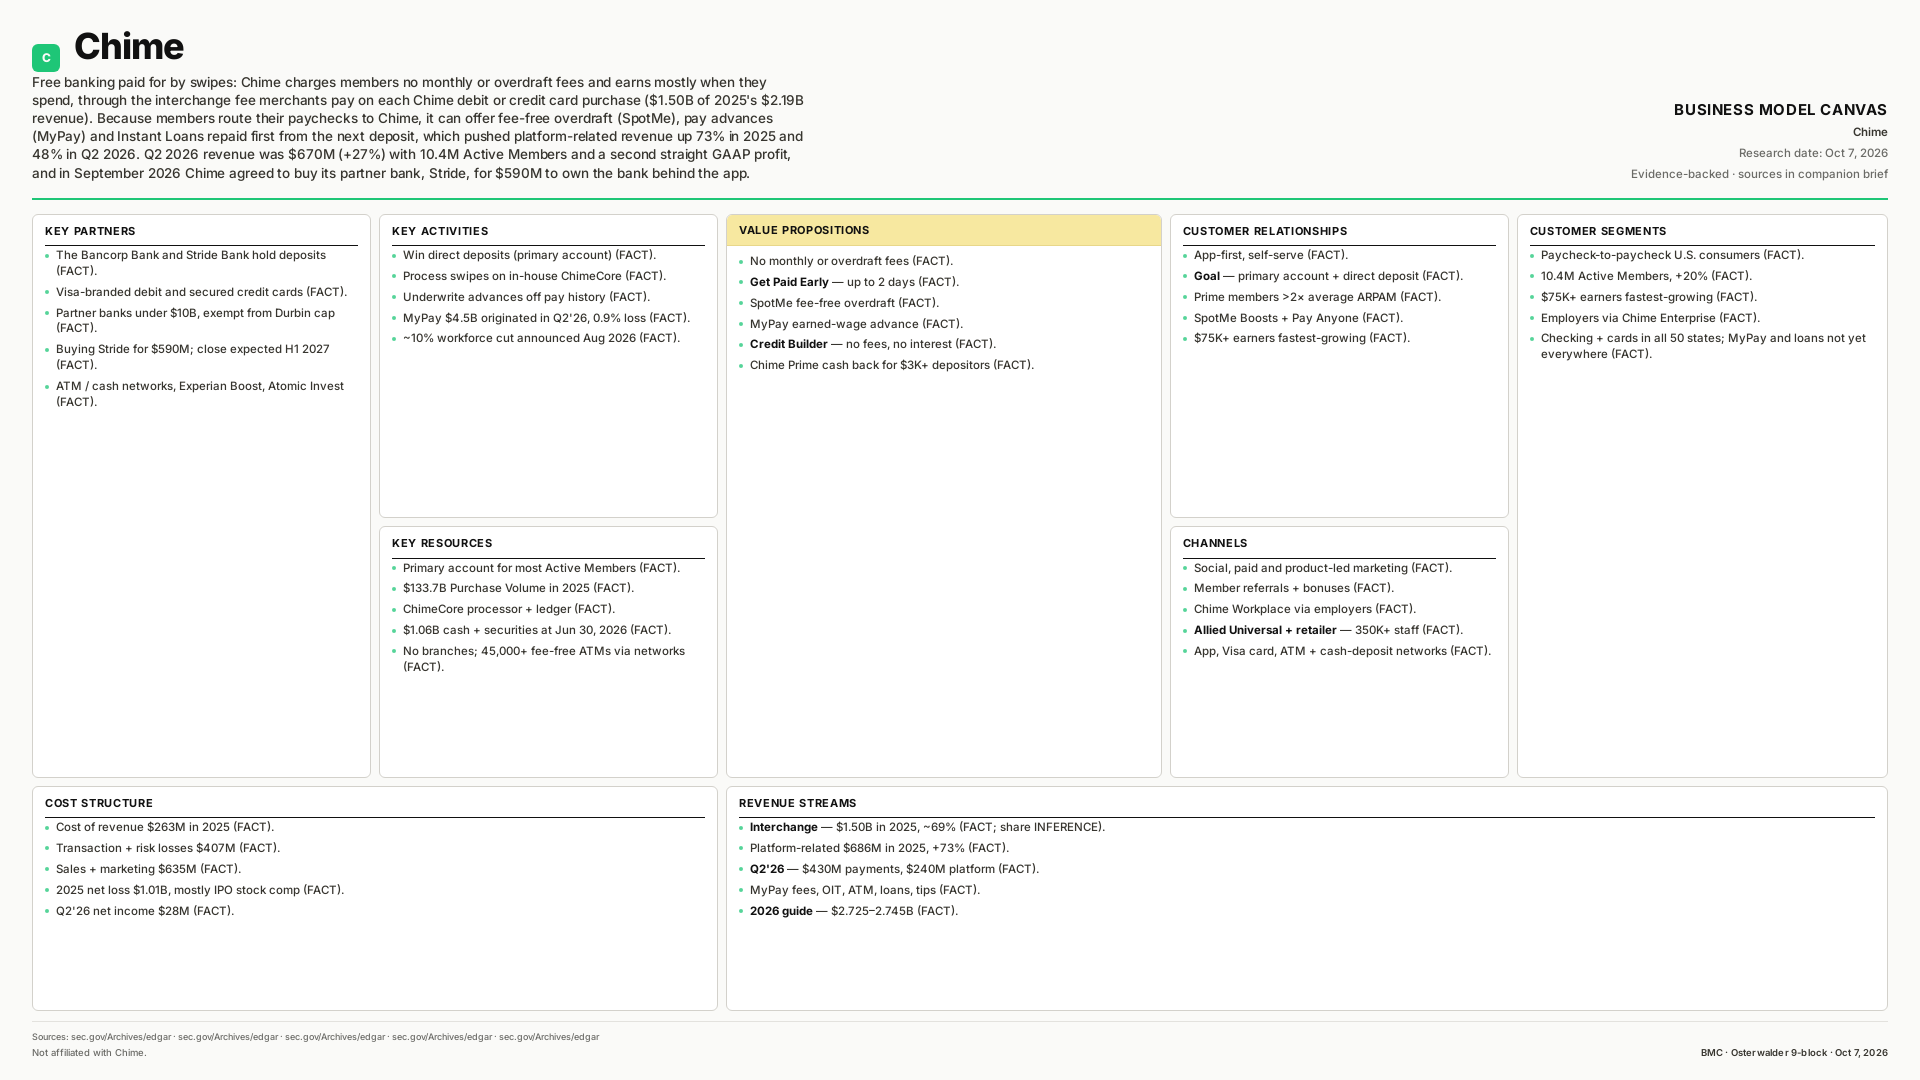

Chime
Fee-free banking paid for by swipes (interchange was $1.50B of 2025's $2.19B revenue) → paychecks routed to Chime let it advance cash via SpotMe, MyPay and Instant Loans (platform revenue +73% in 2025) → Q2'26 revenue $670M +27%, 10.4M Active Members, second GAAP profit → $590M deal to buy partner bank Stride.
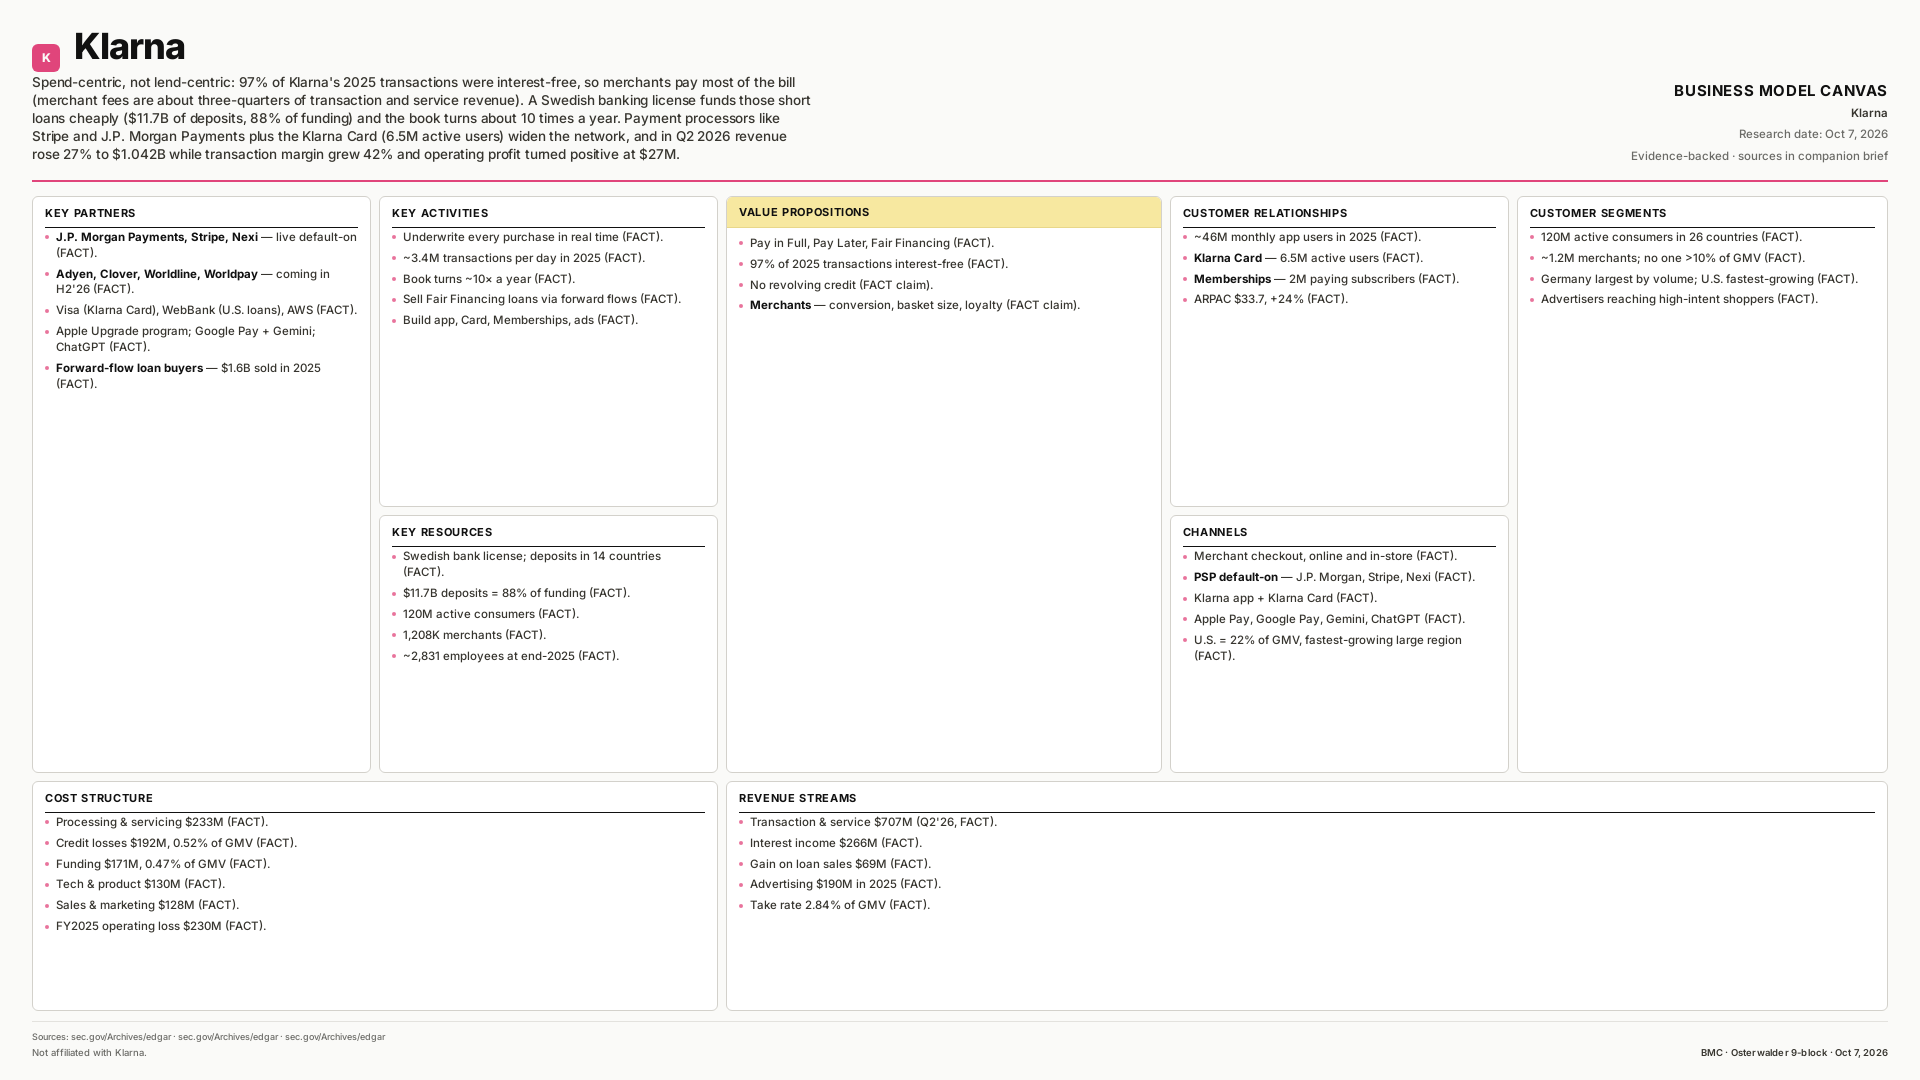

Klarna
Merchants pay most of the bill (97% of 2025 transactions interest-free) → a Swedish bank funds ~40-day loans with $11.7B of deposits (88% of funding) → PSPs like Stripe and J.P. Morgan Payments switch Klarna on by default while the Klarna Card (6.5M users) deepens use → Q2'26 revenue $1.042B +27%, transaction margin +42%, operating profit +$27M.
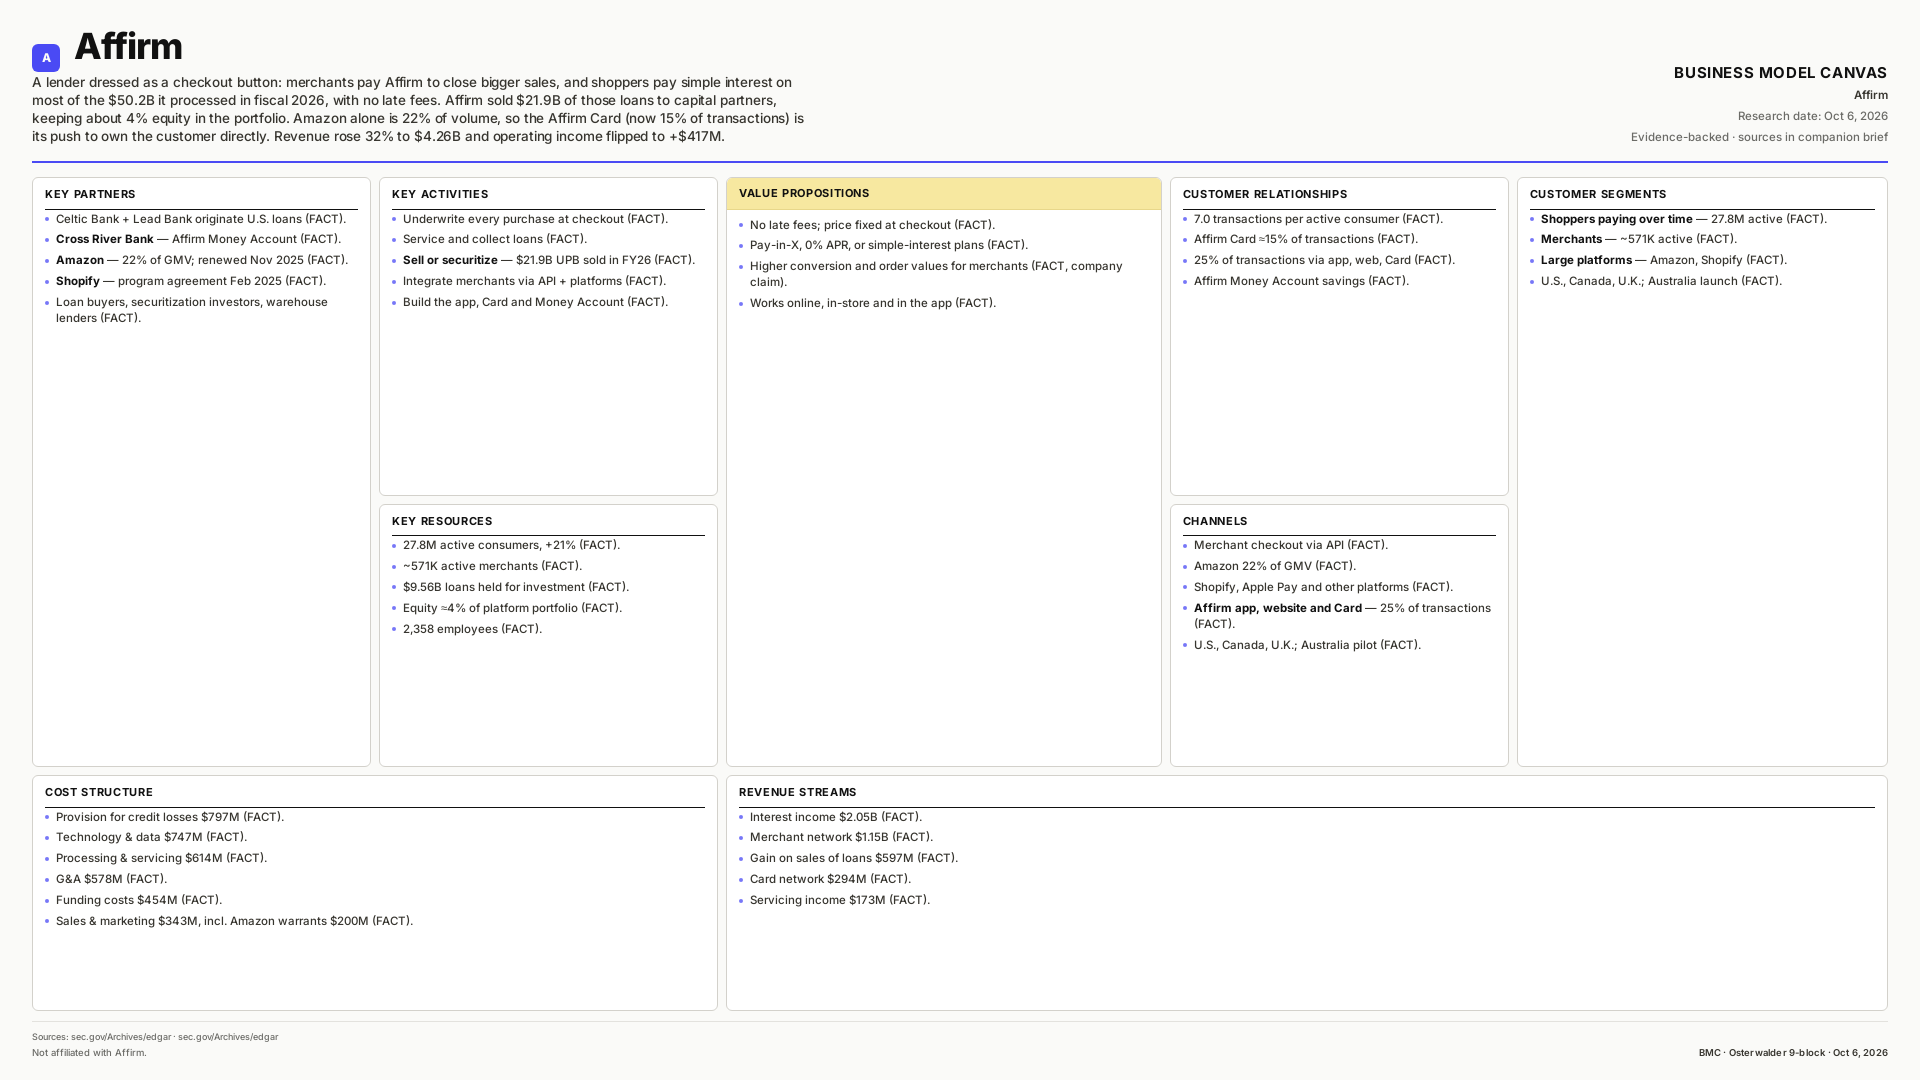

Affirm
Merchants pay to close bigger sales → shoppers pay simple interest on 70% of $50.2B GMV, never late fees → loans sold to capital partners on ~4% equity → Amazon is 22% of GMV, so the Affirm Card (15% of transactions) builds a direct relationship → FY26 operating income +$417M.
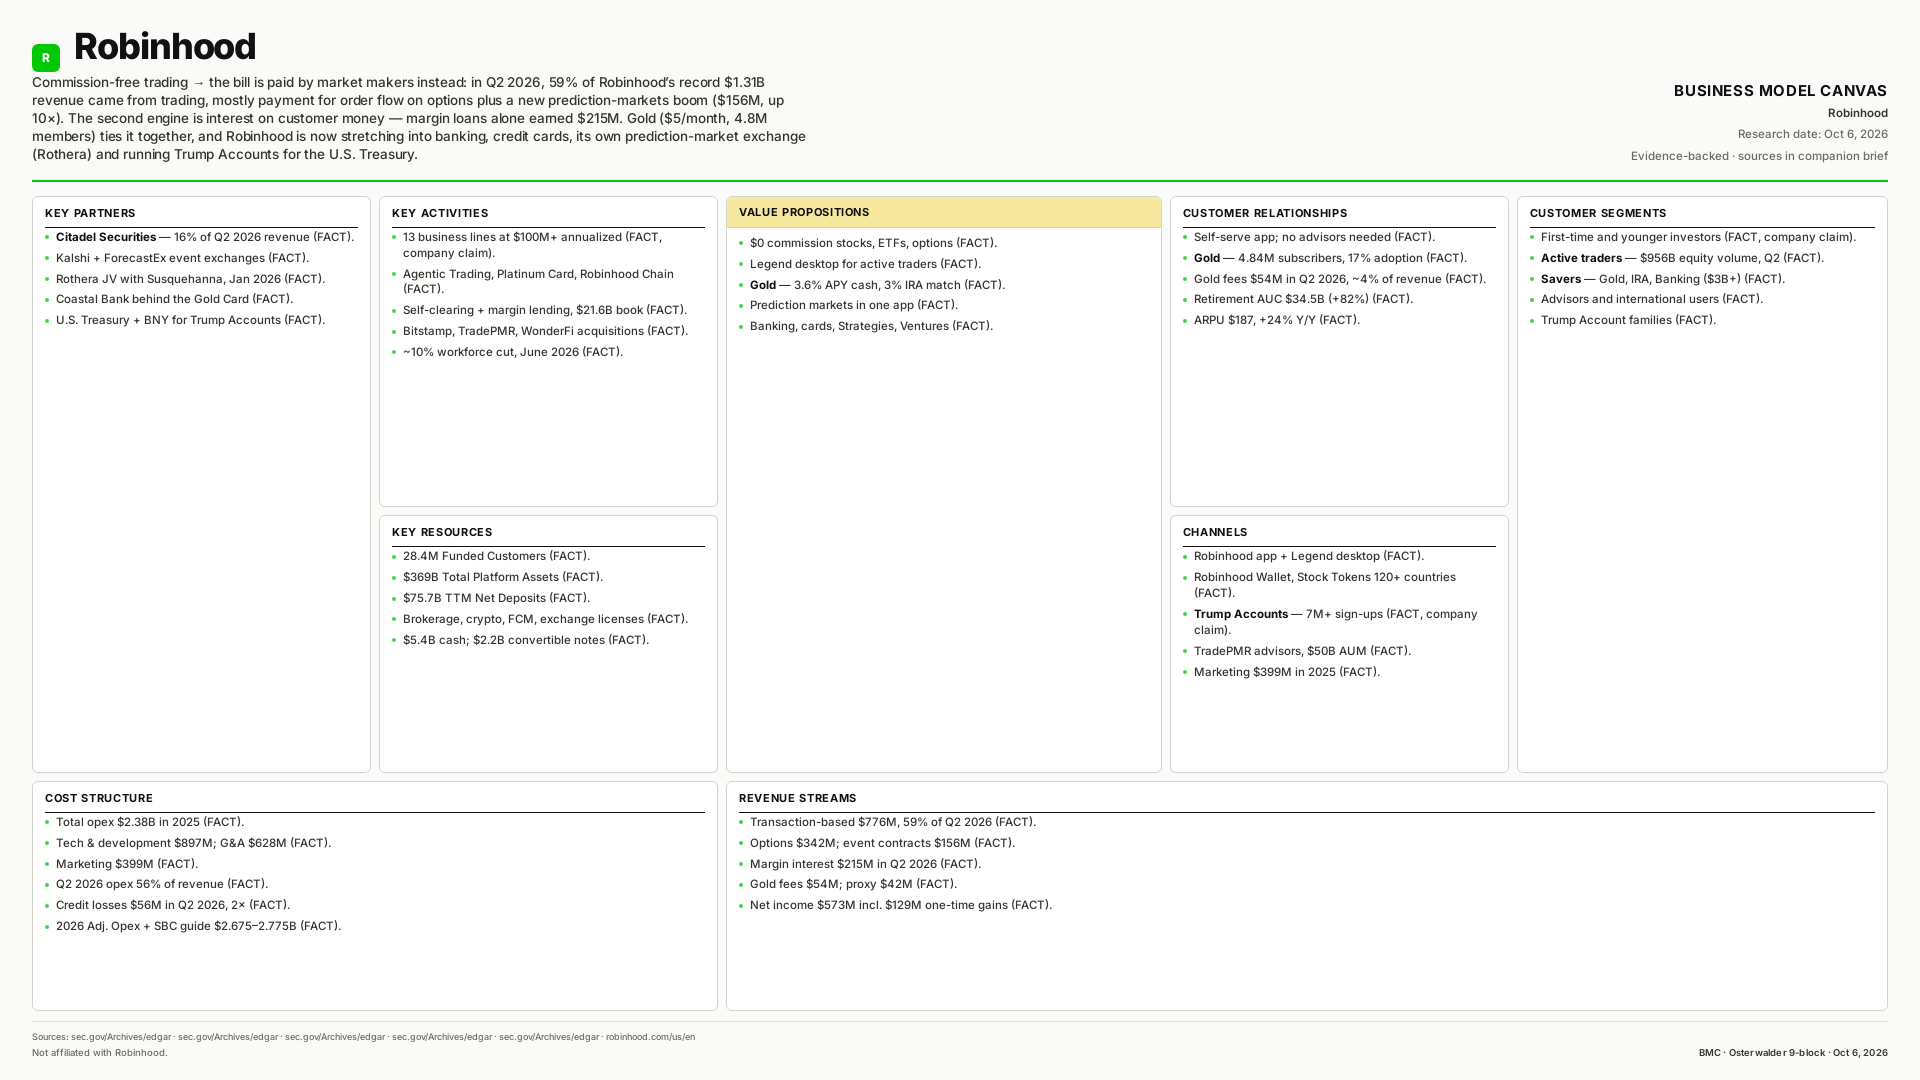

Robinhood
Commission-free trading → paid for by market makers (Citadel Securities alone 16% of Q2 2026 revenue) → margin and cash interest as a second engine → Gold at $5/month (4.8M members) → prediction markets up 10×+, Rothera, banking, cards and Trump Accounts.
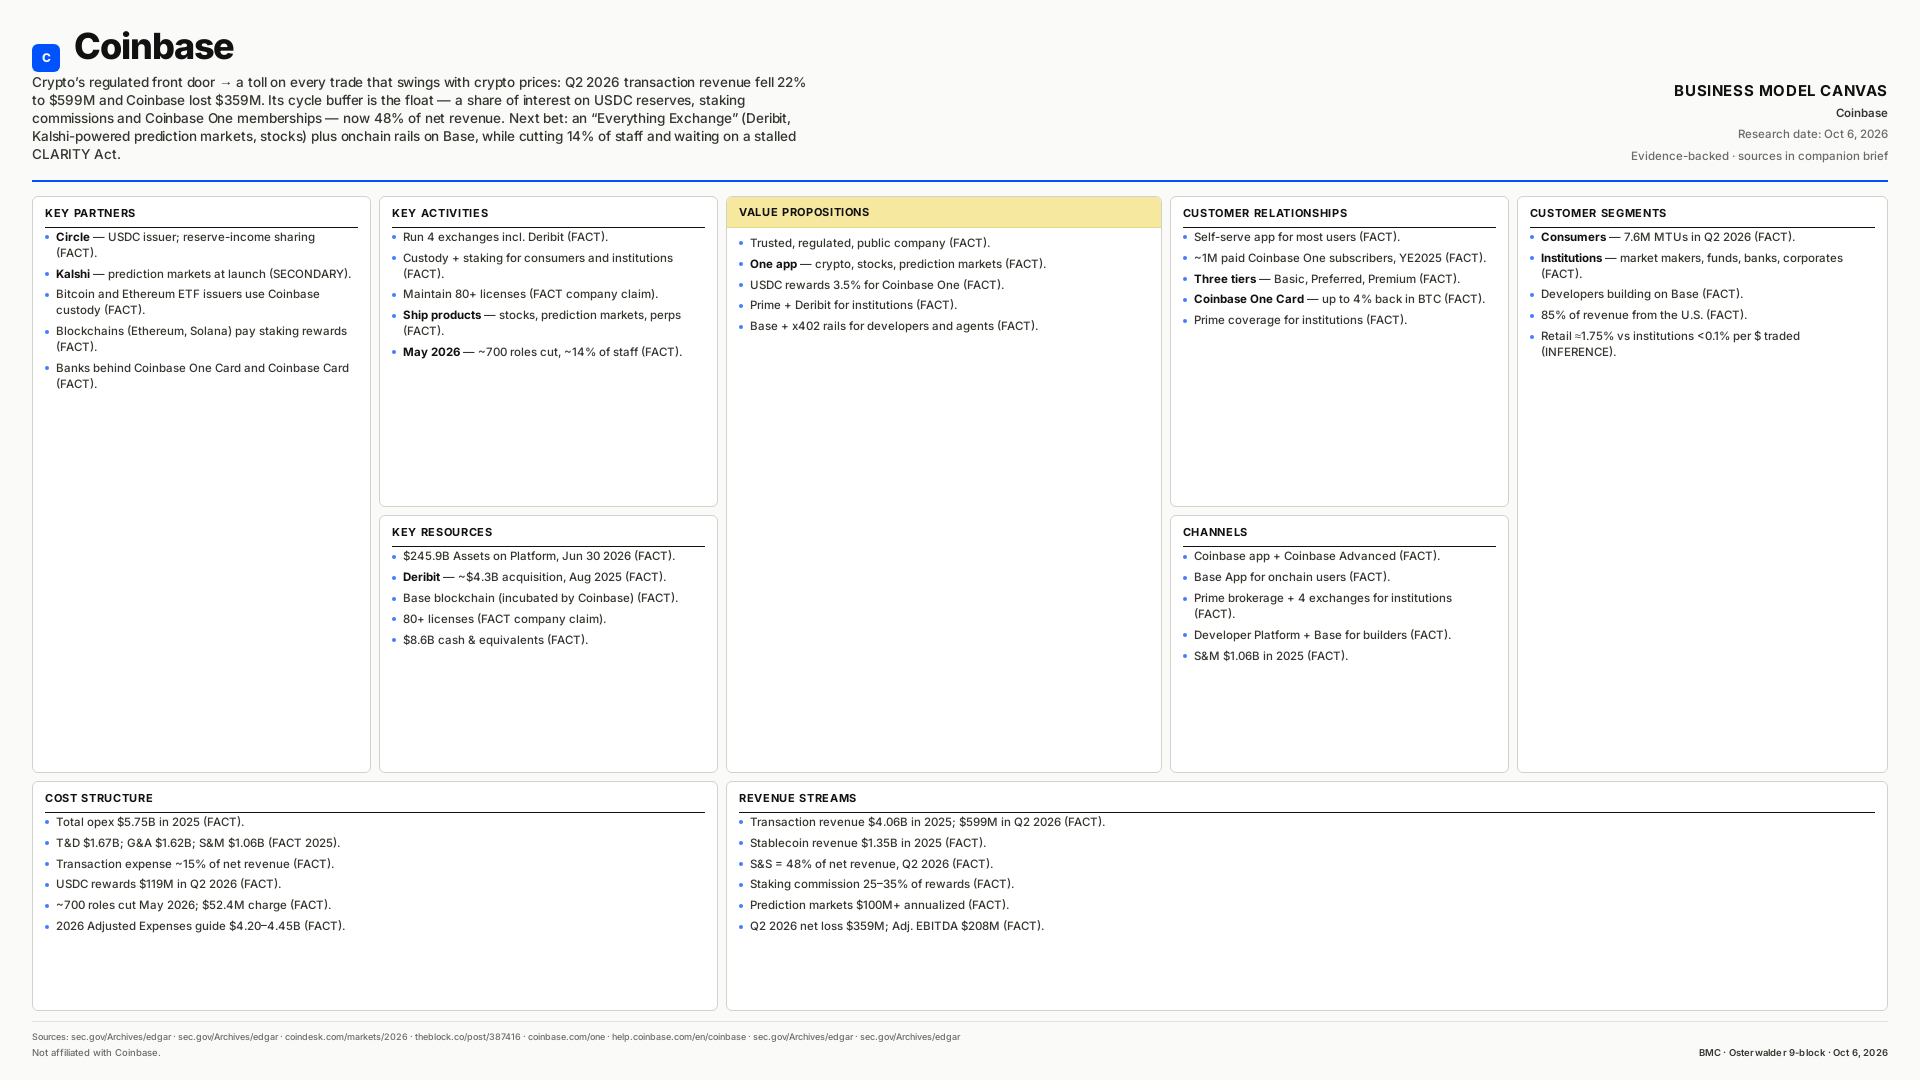

Coinbase
Crypto’s regulated front door → a trading toll that swings with crypto prices (Q2 2026 transaction revenue −22% to $599M) → a USDC, staking and Coinbase One float now 48% of net revenue → Everything Exchange and Base bets amid 14% layoffs.
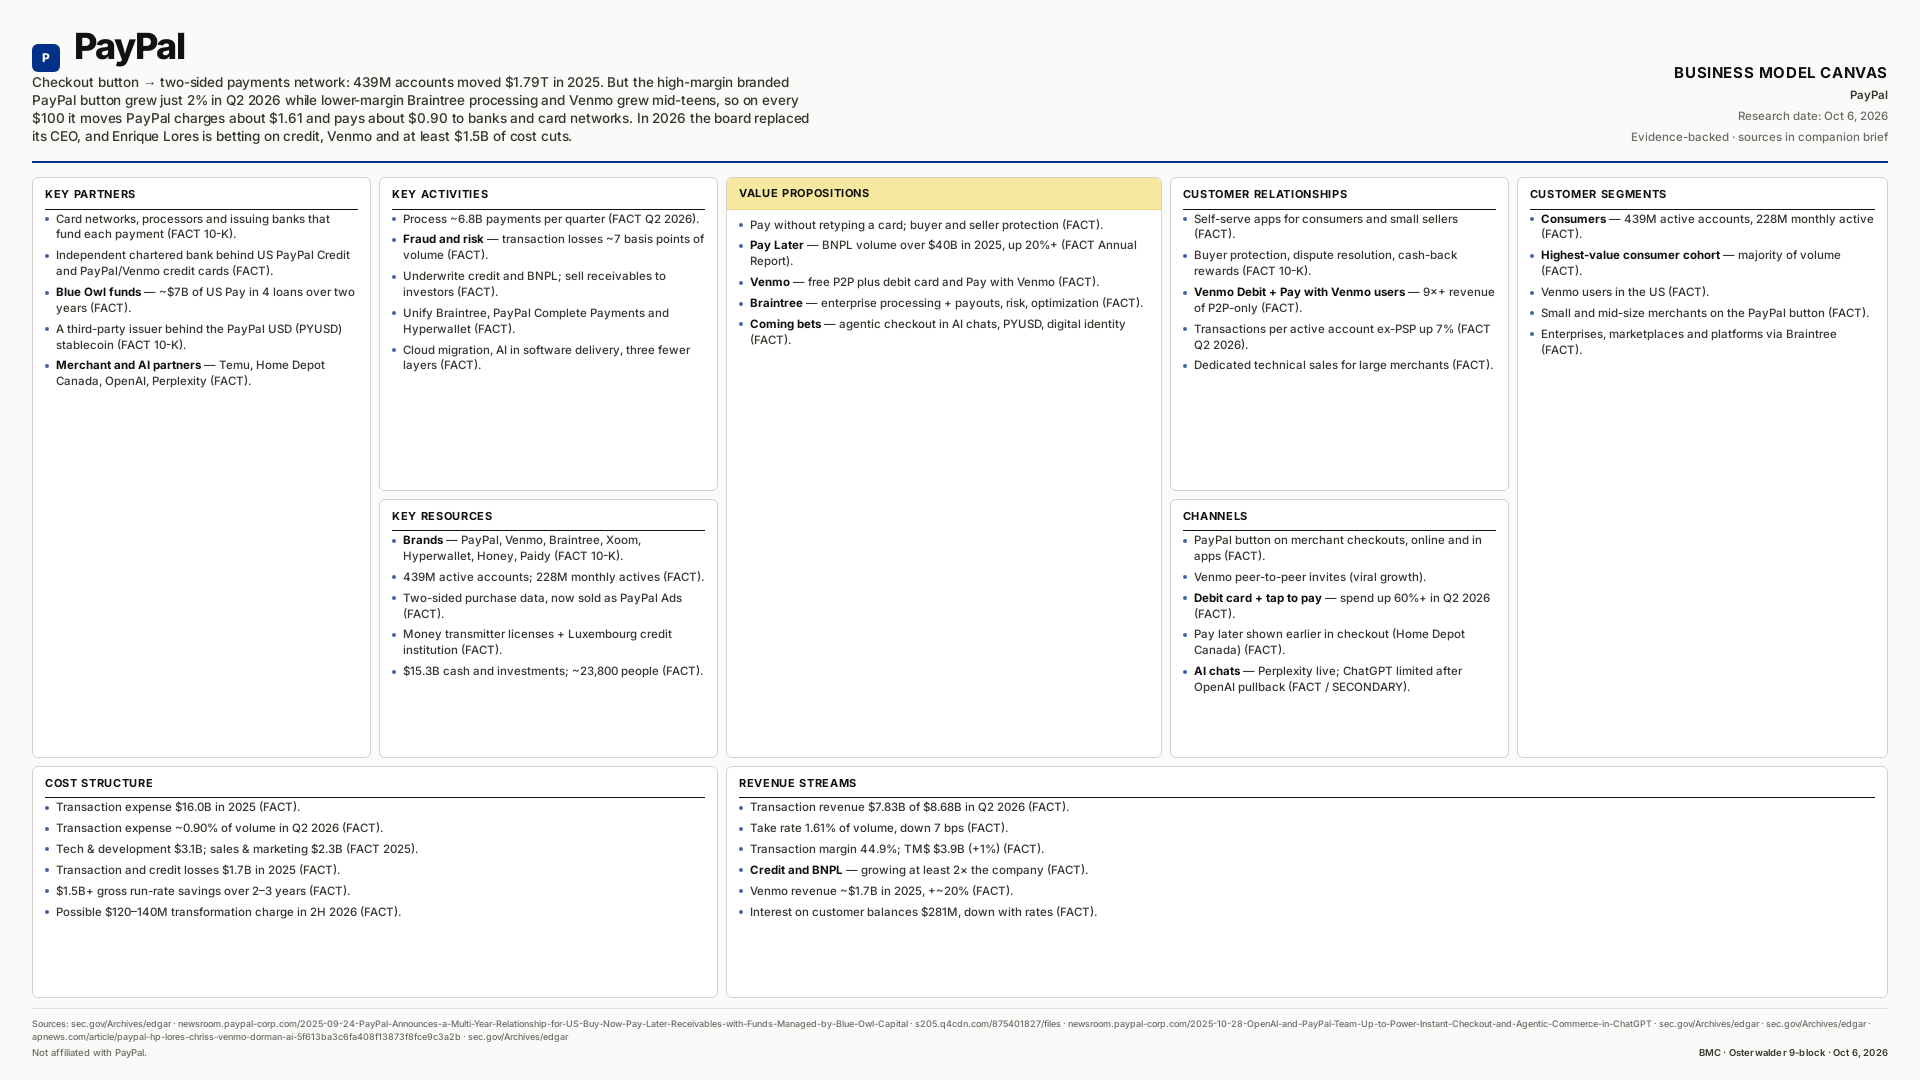

PayPal
Trusted checkout button → two-sided payments network (439M accounts, $1.79T in 2025) → branded checkout stalls while Braintree and Venmo grow → new CEO bets on credit, Venmo and cost cuts.
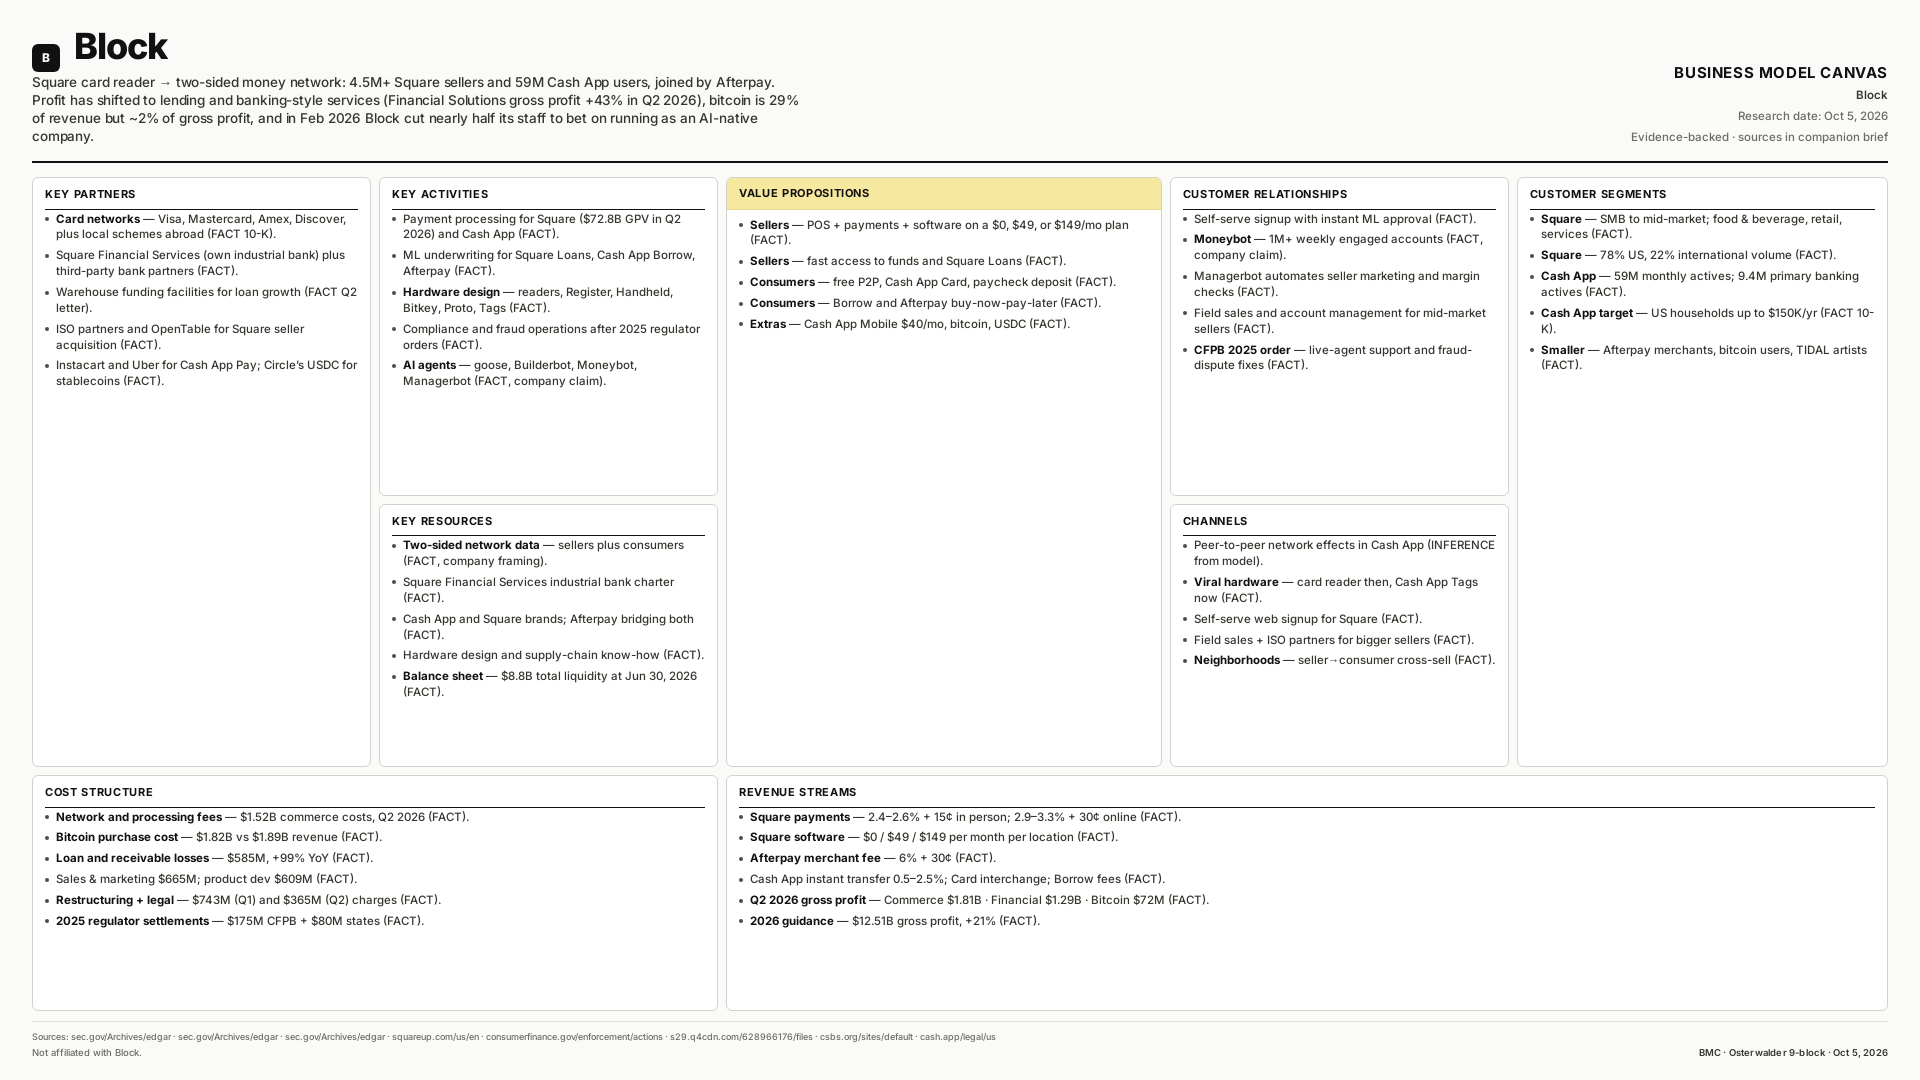

Block
Square card reader → two-sided money network (Square + Cash App + Afterpay) → profit shifts to lending → AI-driven halving of headcount.
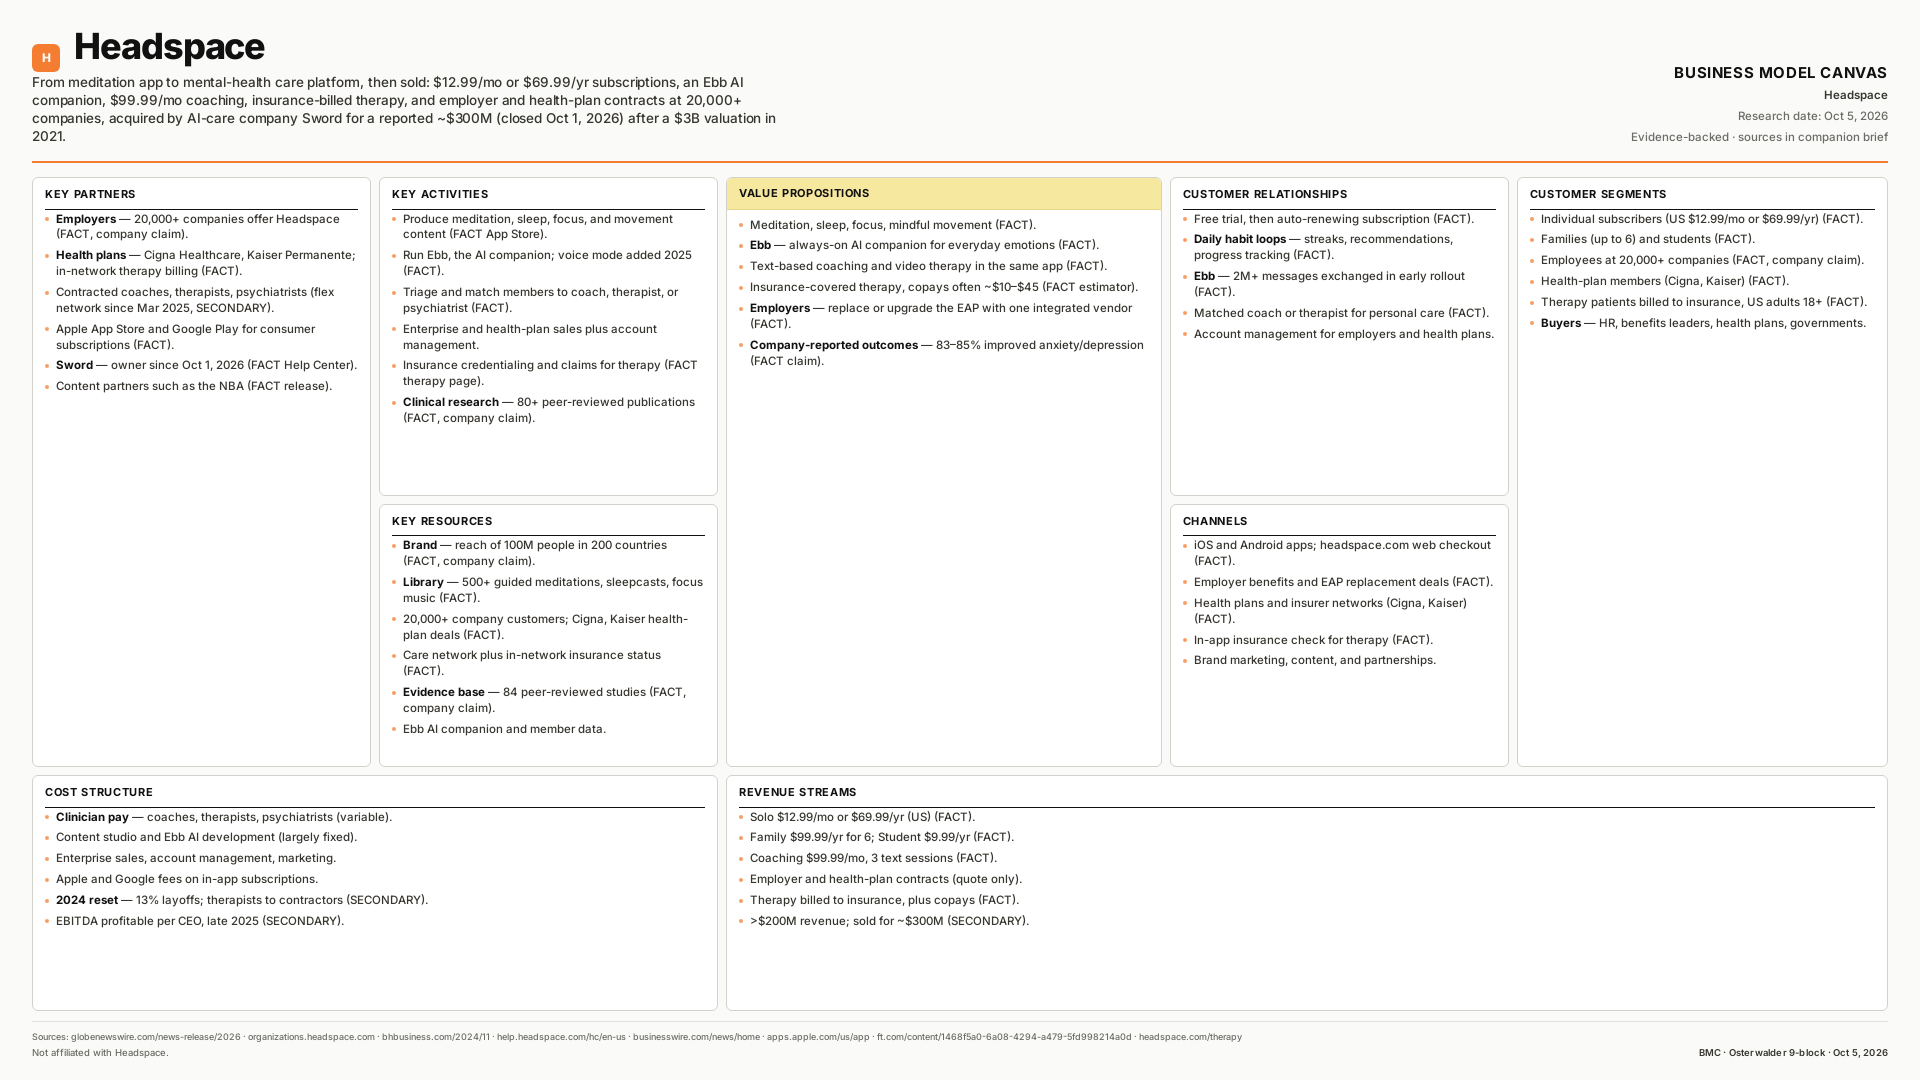

Headspace
Meditation app → B2B mental-health care platform → AI companion → sold to Sword.
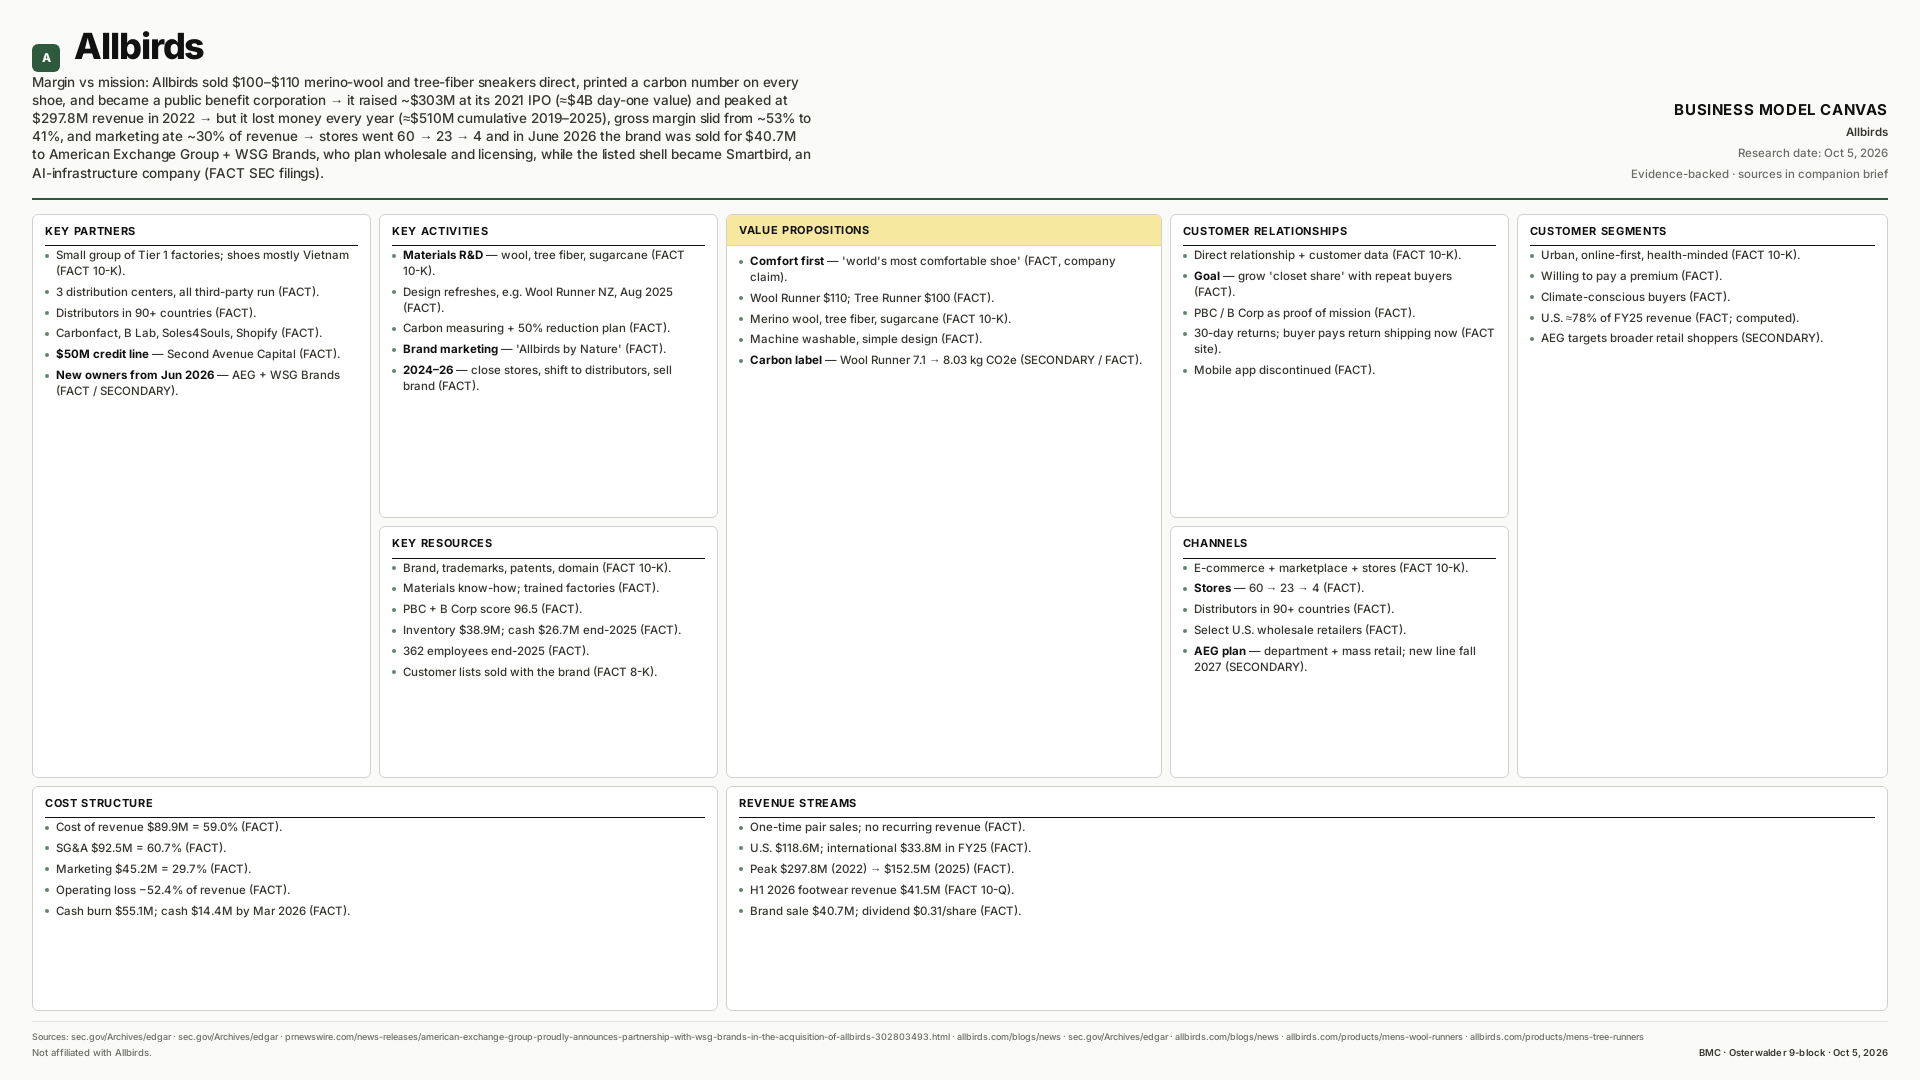

Allbirds
DTC sustainability brand where the mission outran the margin — then the brand was sold.
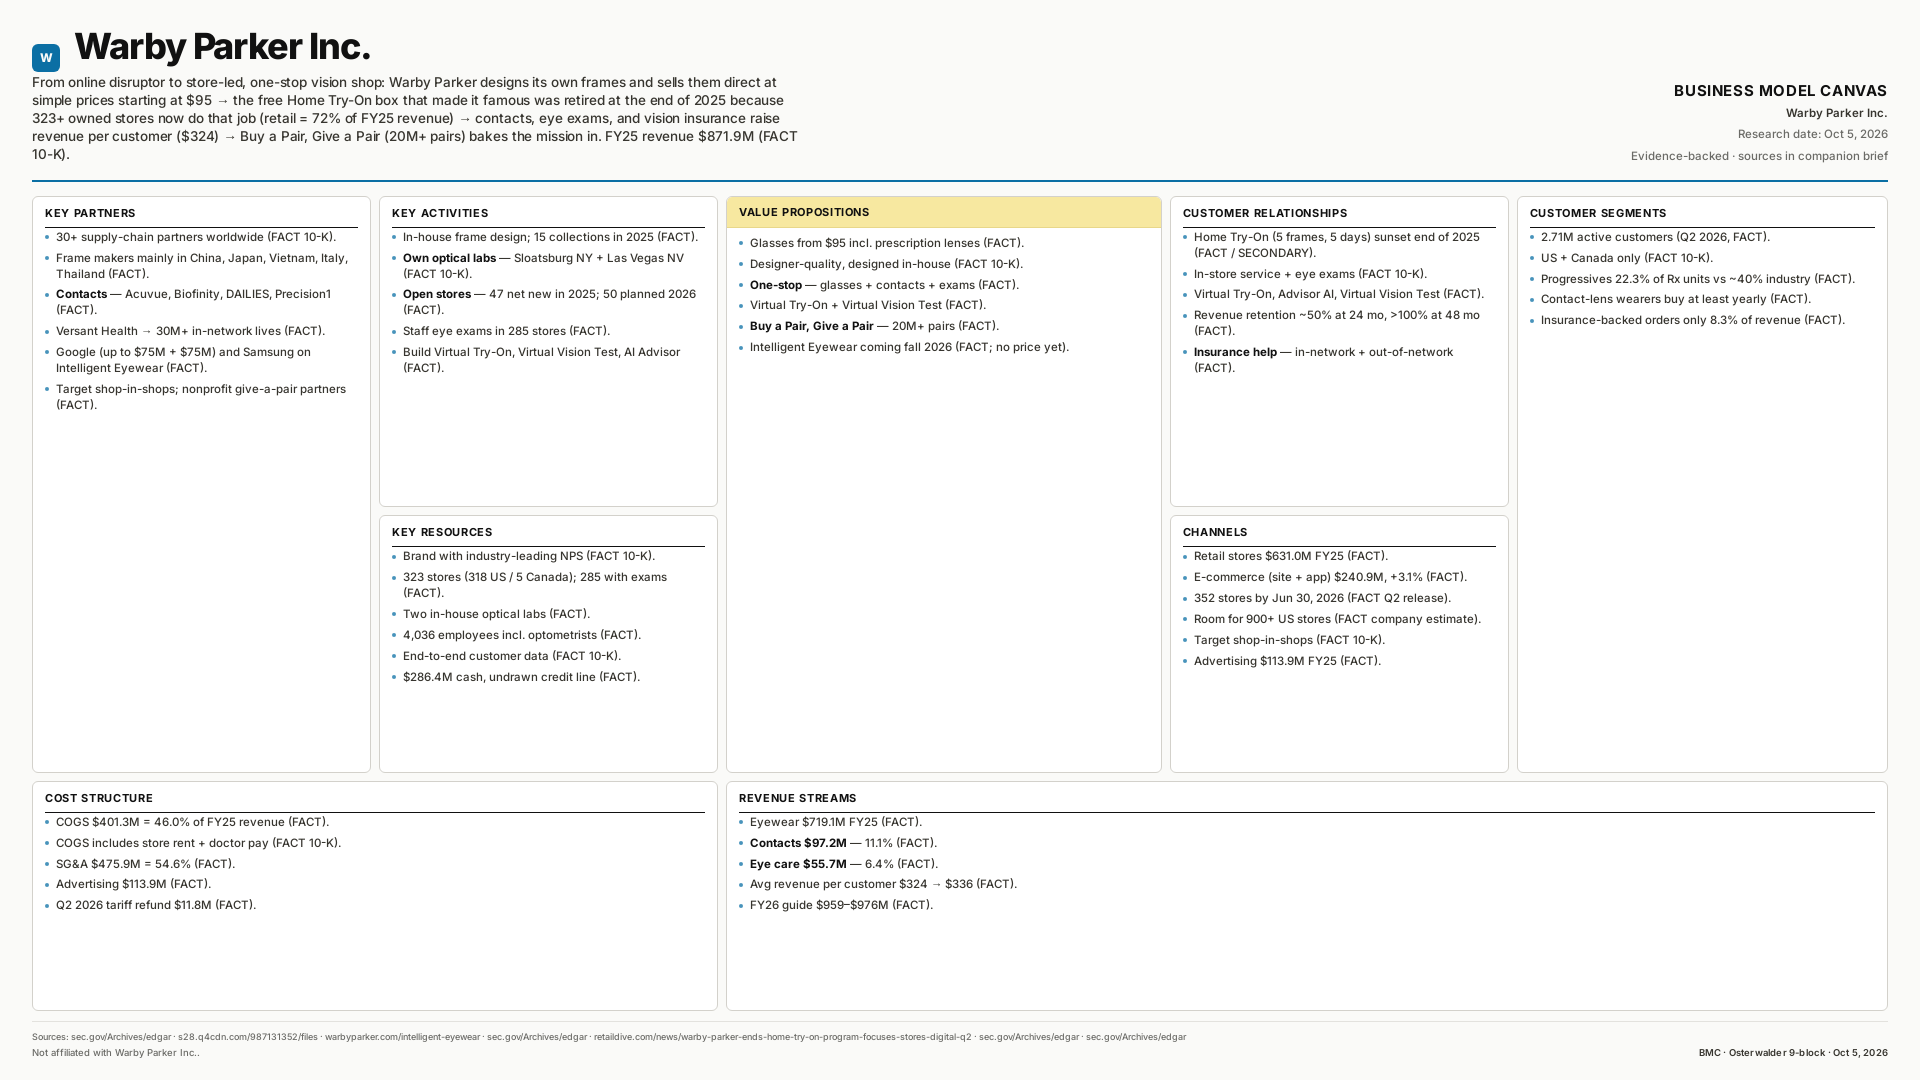

Warby Parker Inc.
From DTC disruptor to store-led, one-stop vision shop.
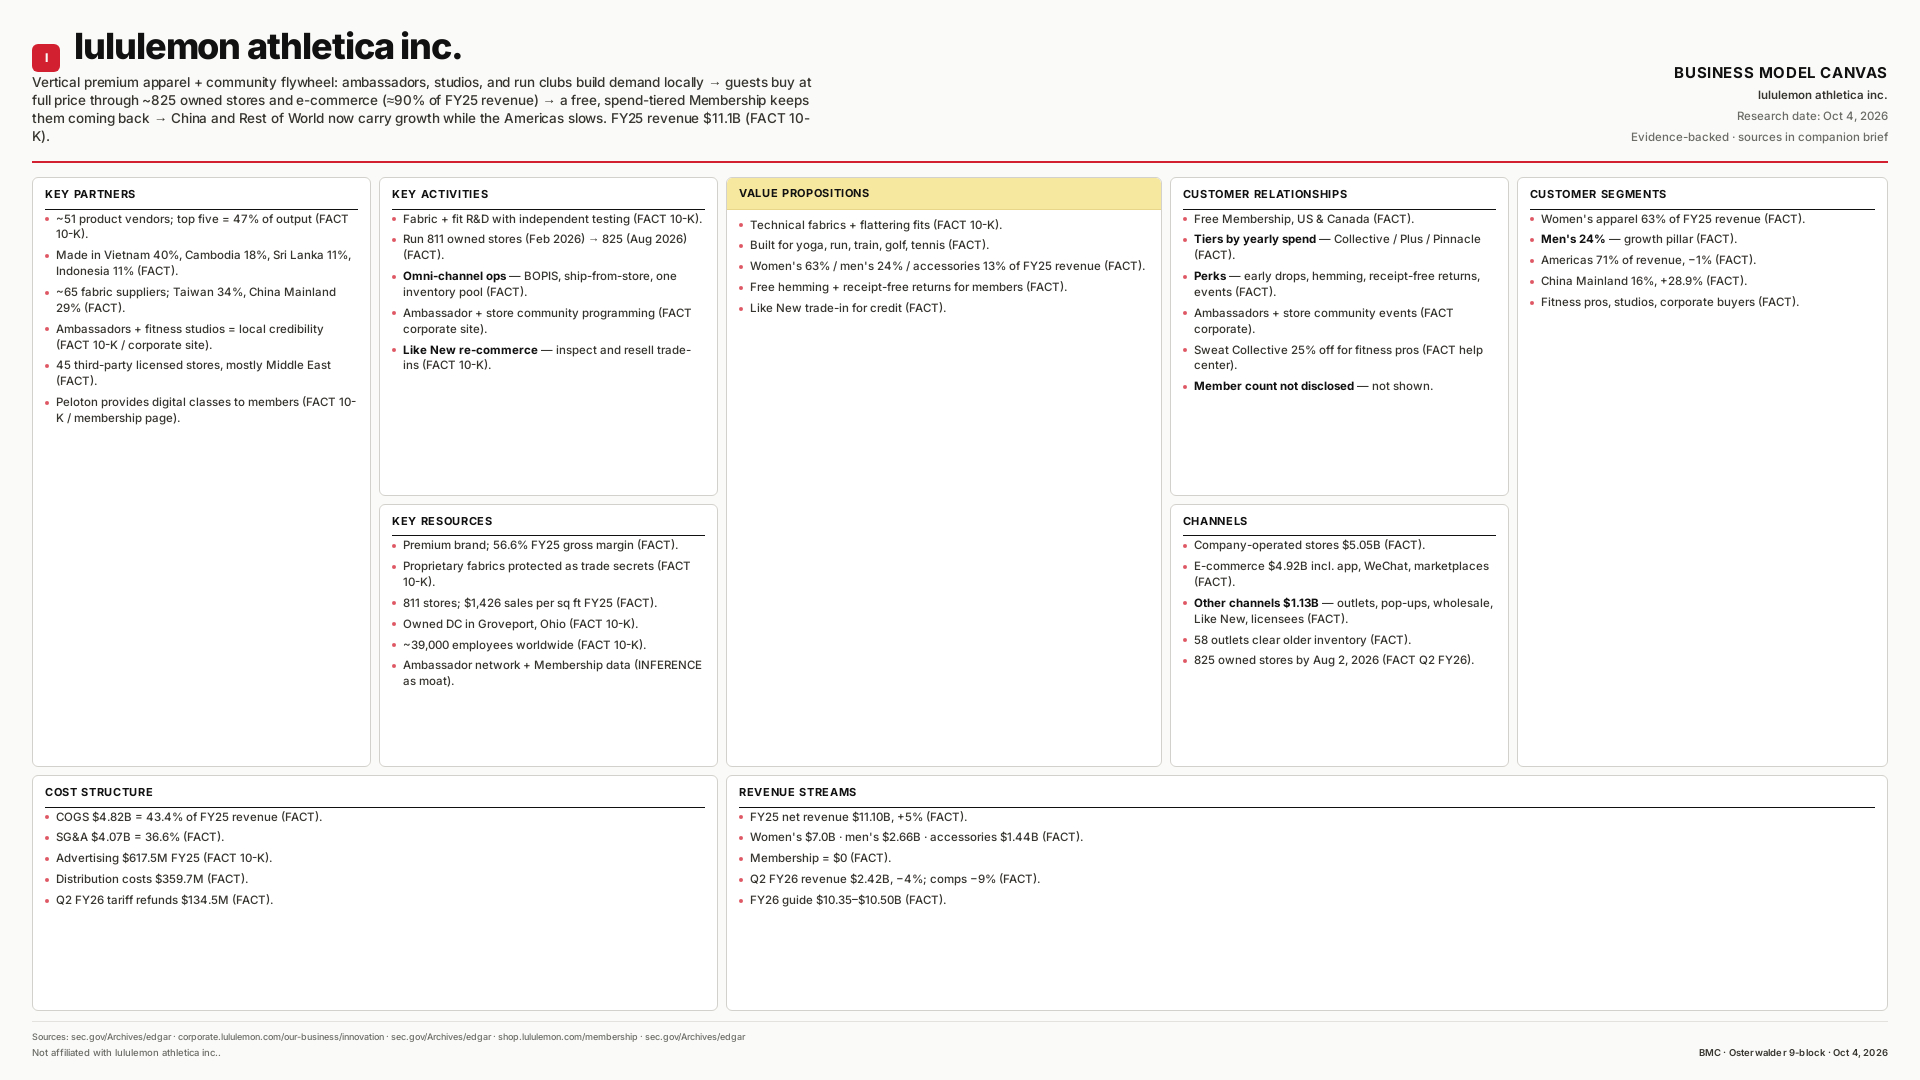

lululemon athletica inc.
Vertical premium apparel + community flywheel.
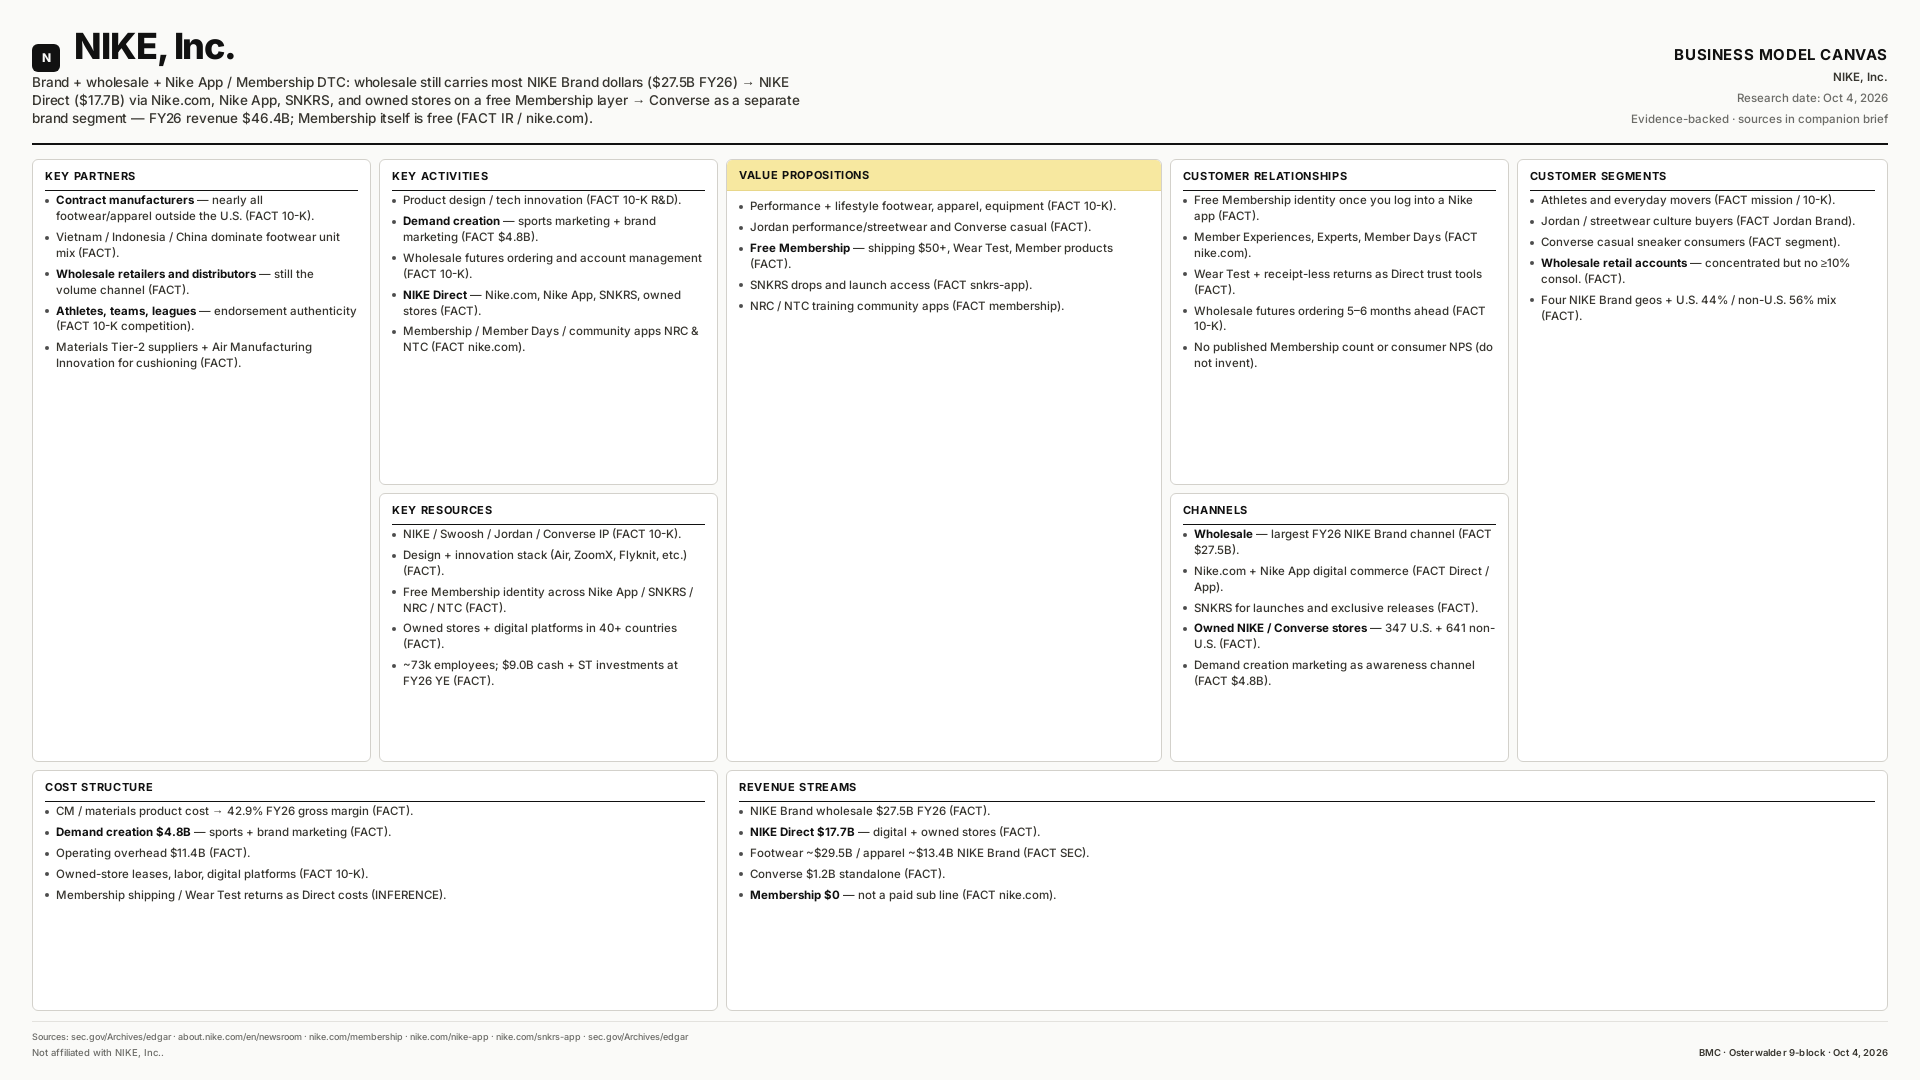

NIKE, Inc.
Brand + wholesale + Nike App / Membership DTC.
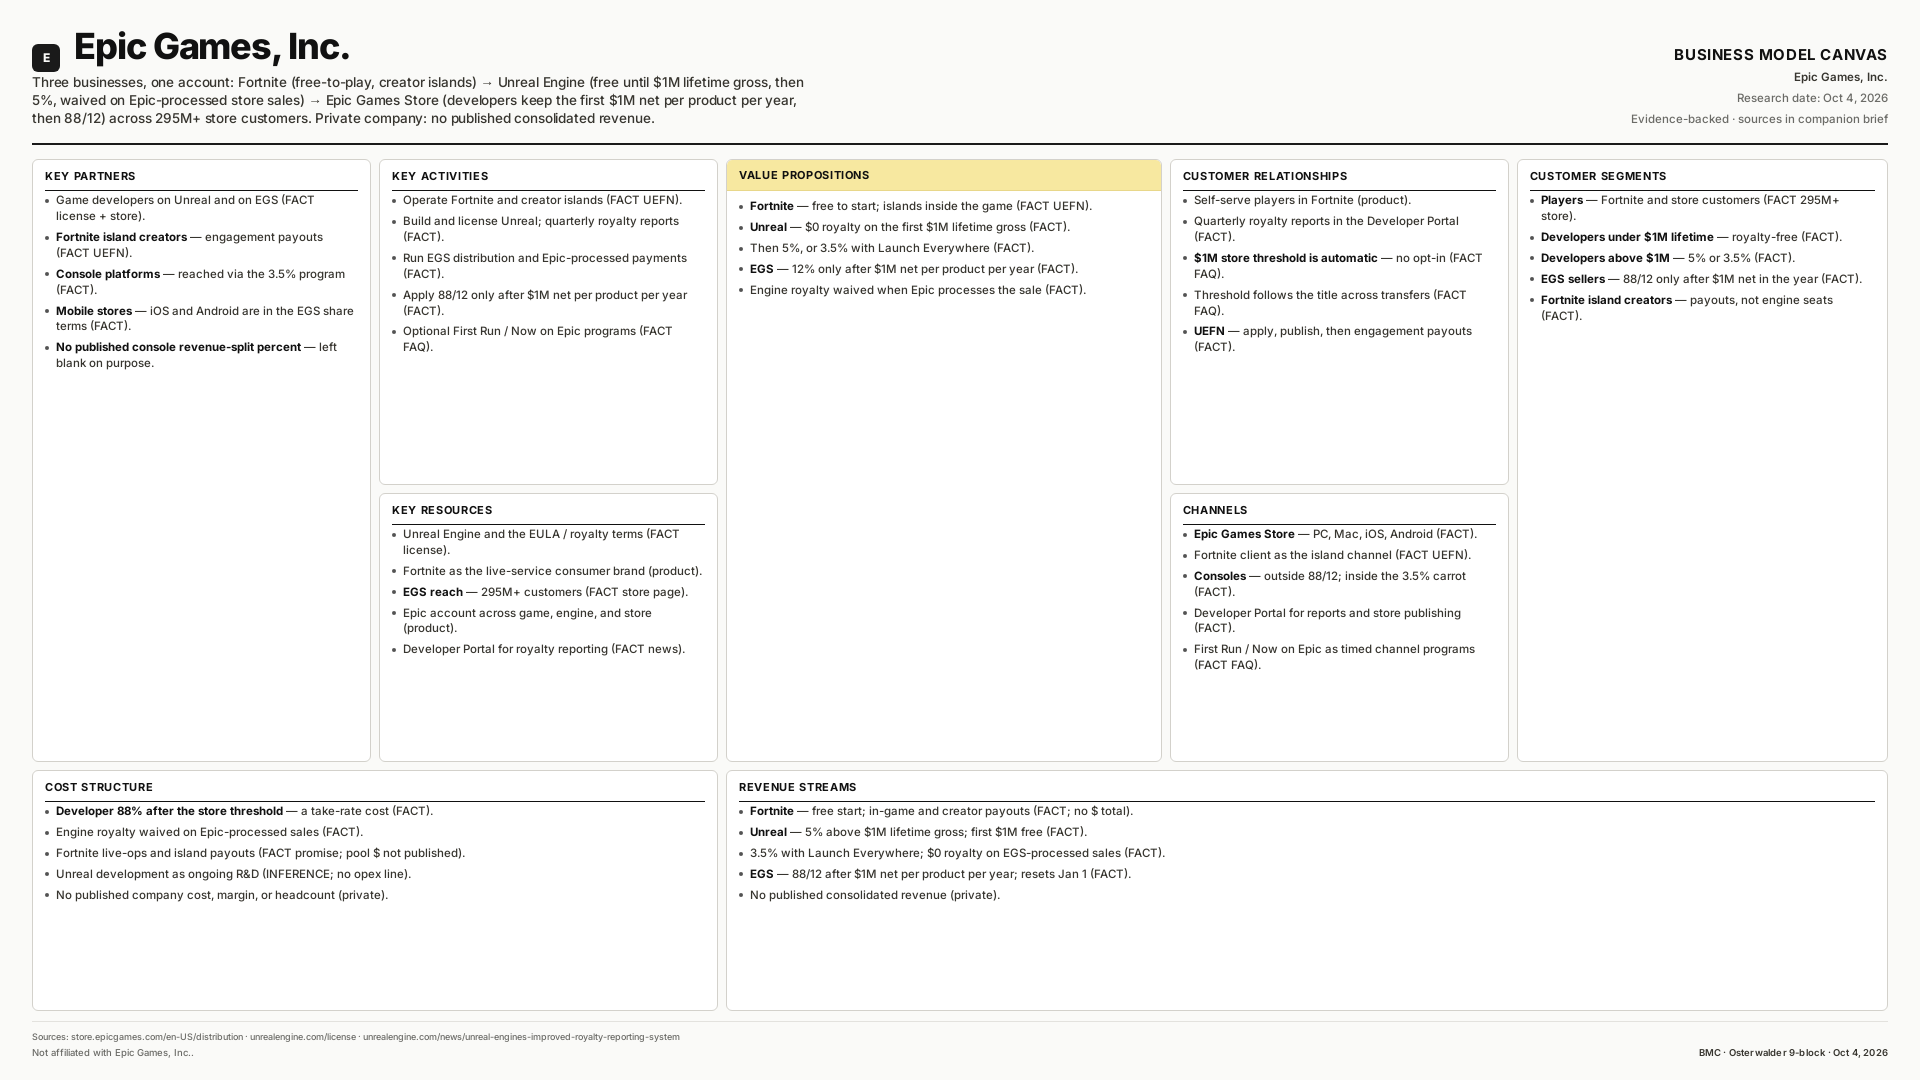

Epic Games, Inc.
Fortnite + Unreal royalty + Epic Games Store 88/12 after $1M.
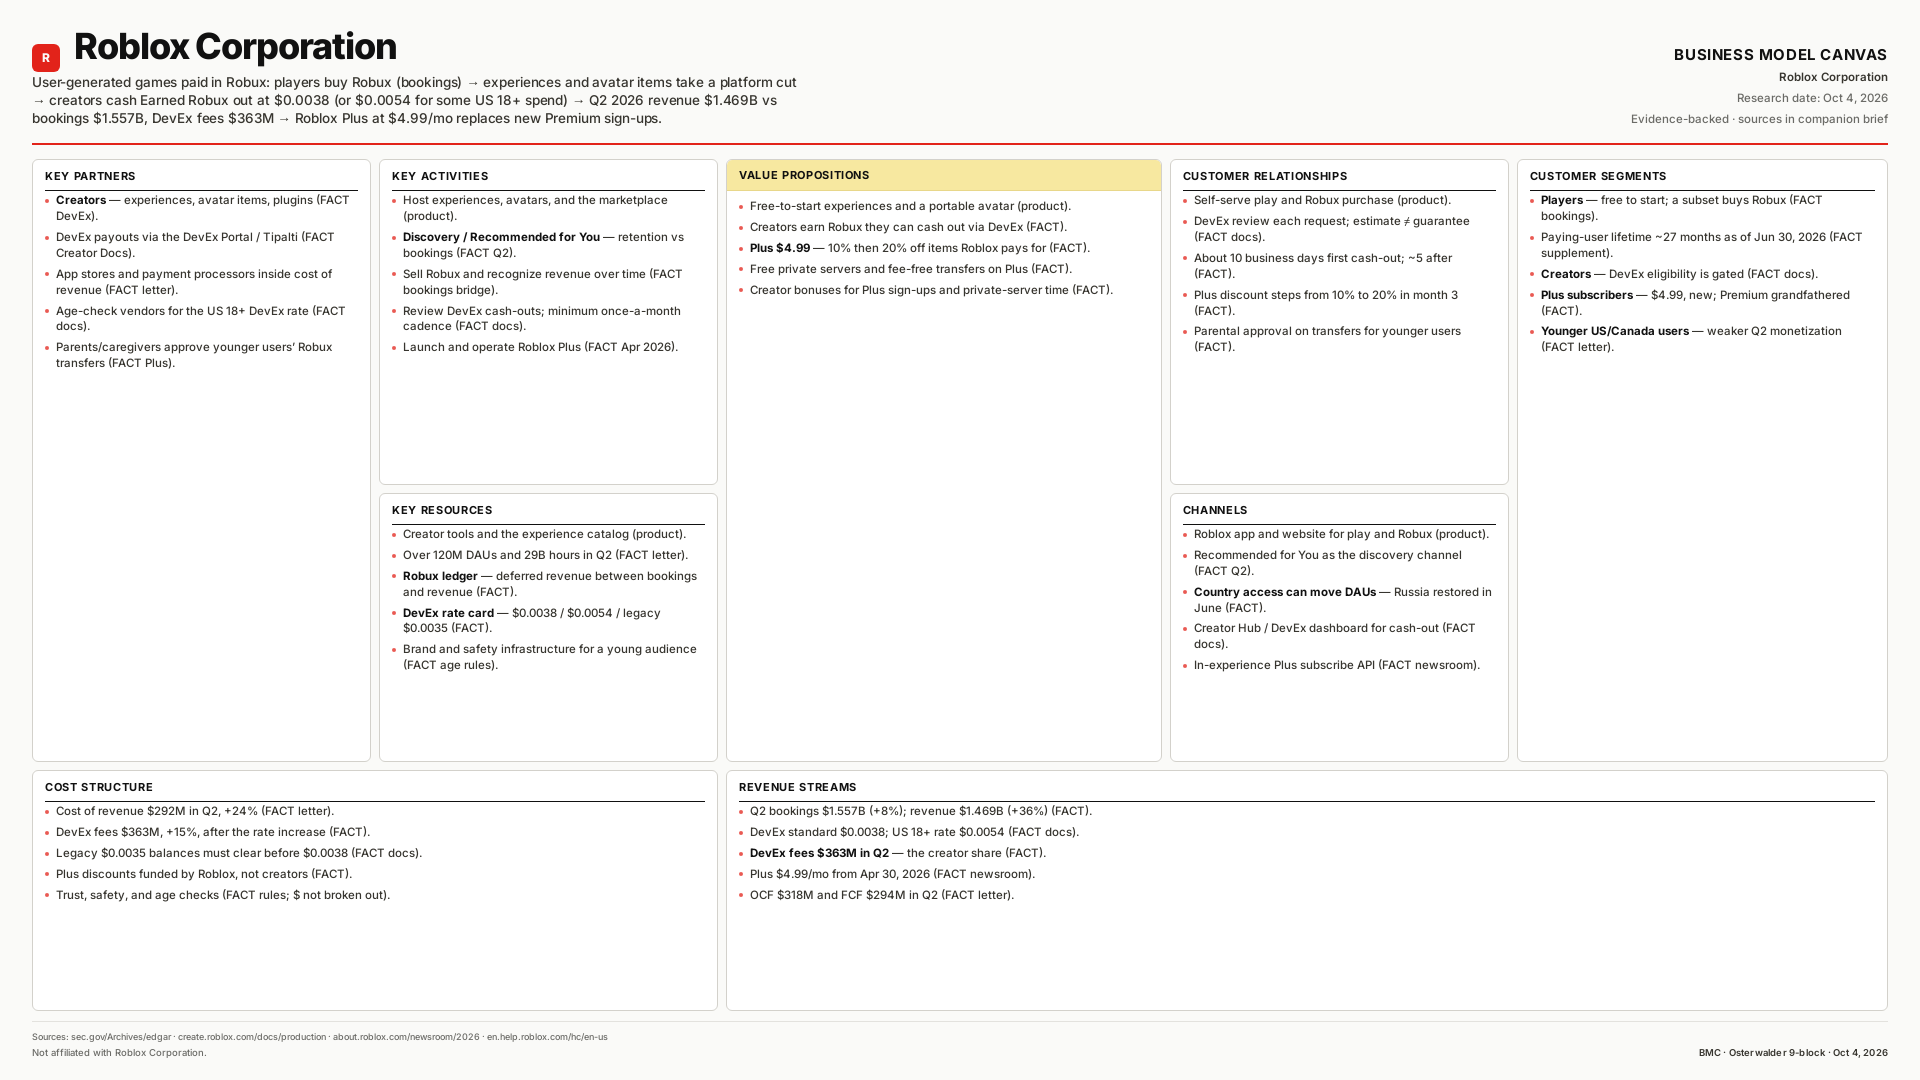

Roblox Corporation
Robux bookings → deferred revenue → DevEx take-rate → Roblox Plus.
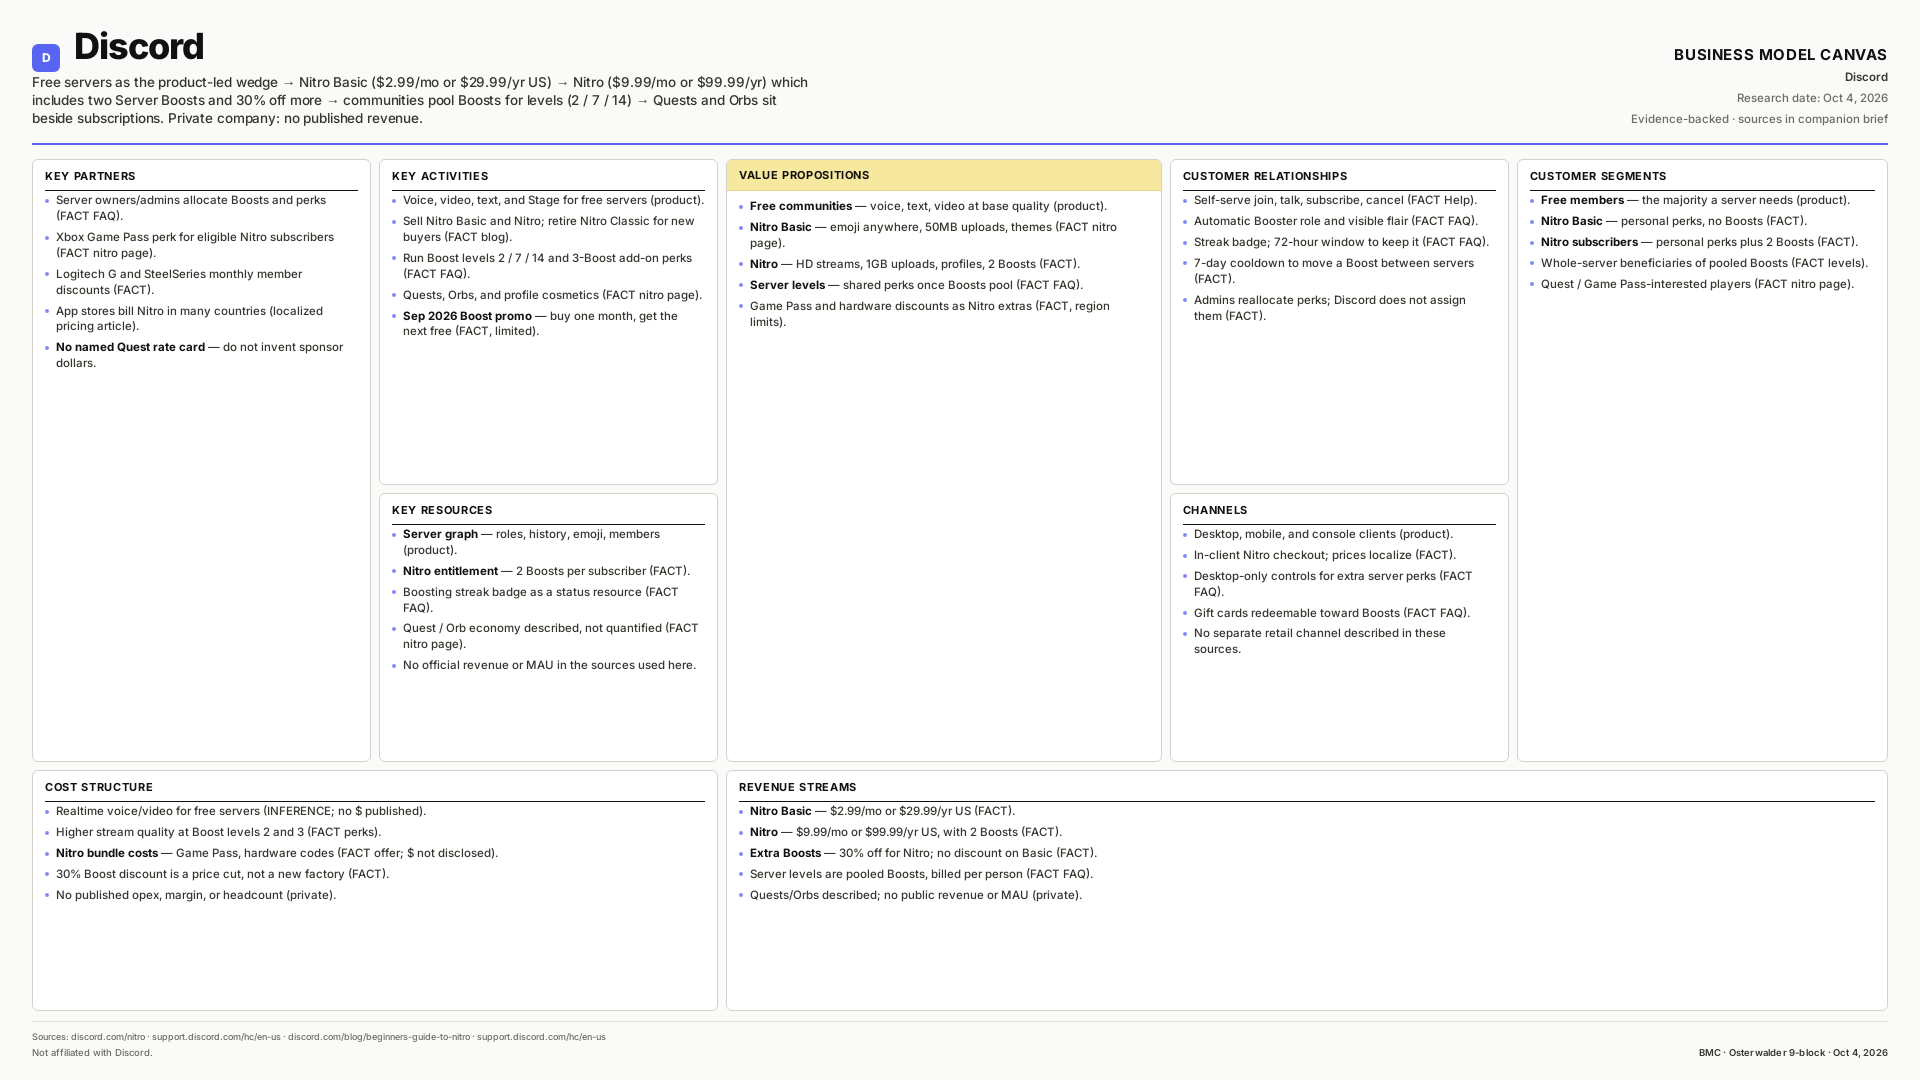

Discord
Free servers → Nitro Basic → Nitro with Boosts → communities level up together.
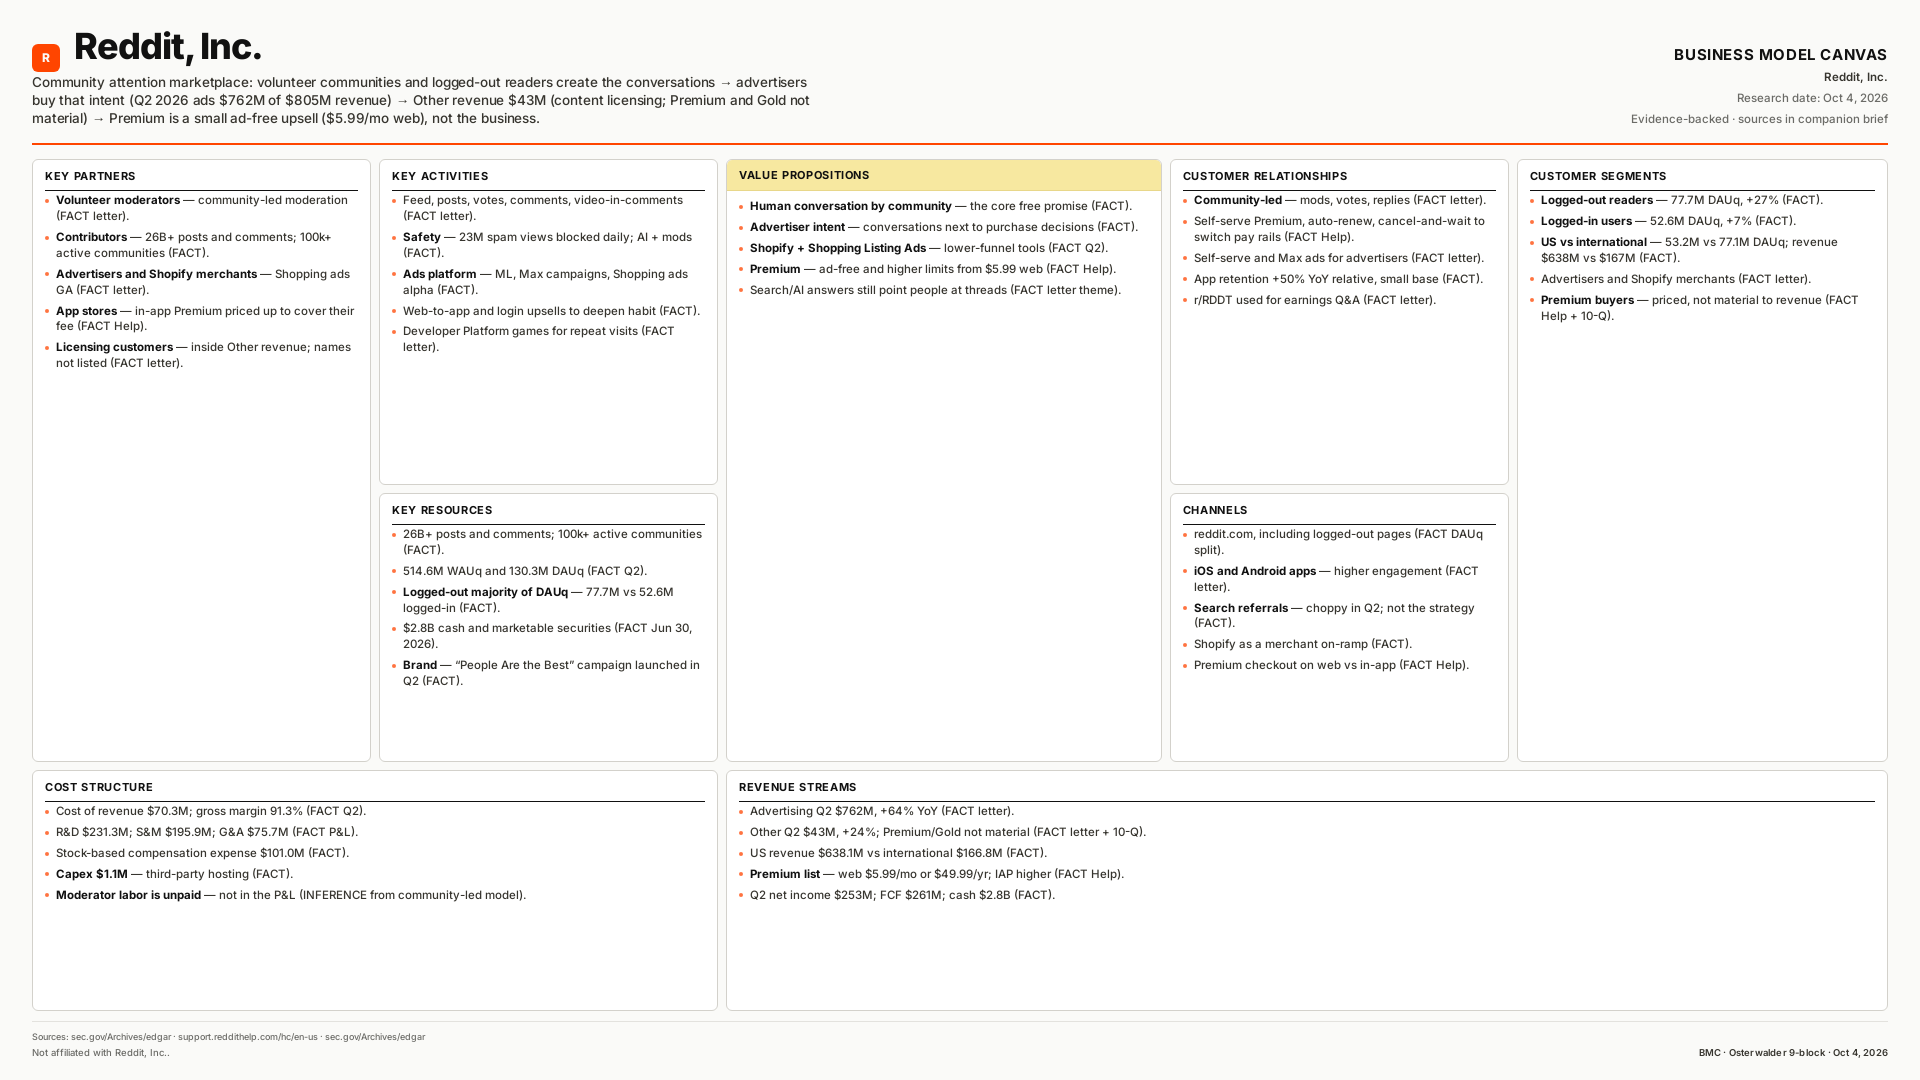

Reddit, Inc.
Community ads → logged-out reach → Other/licensing → Premium is not the business.
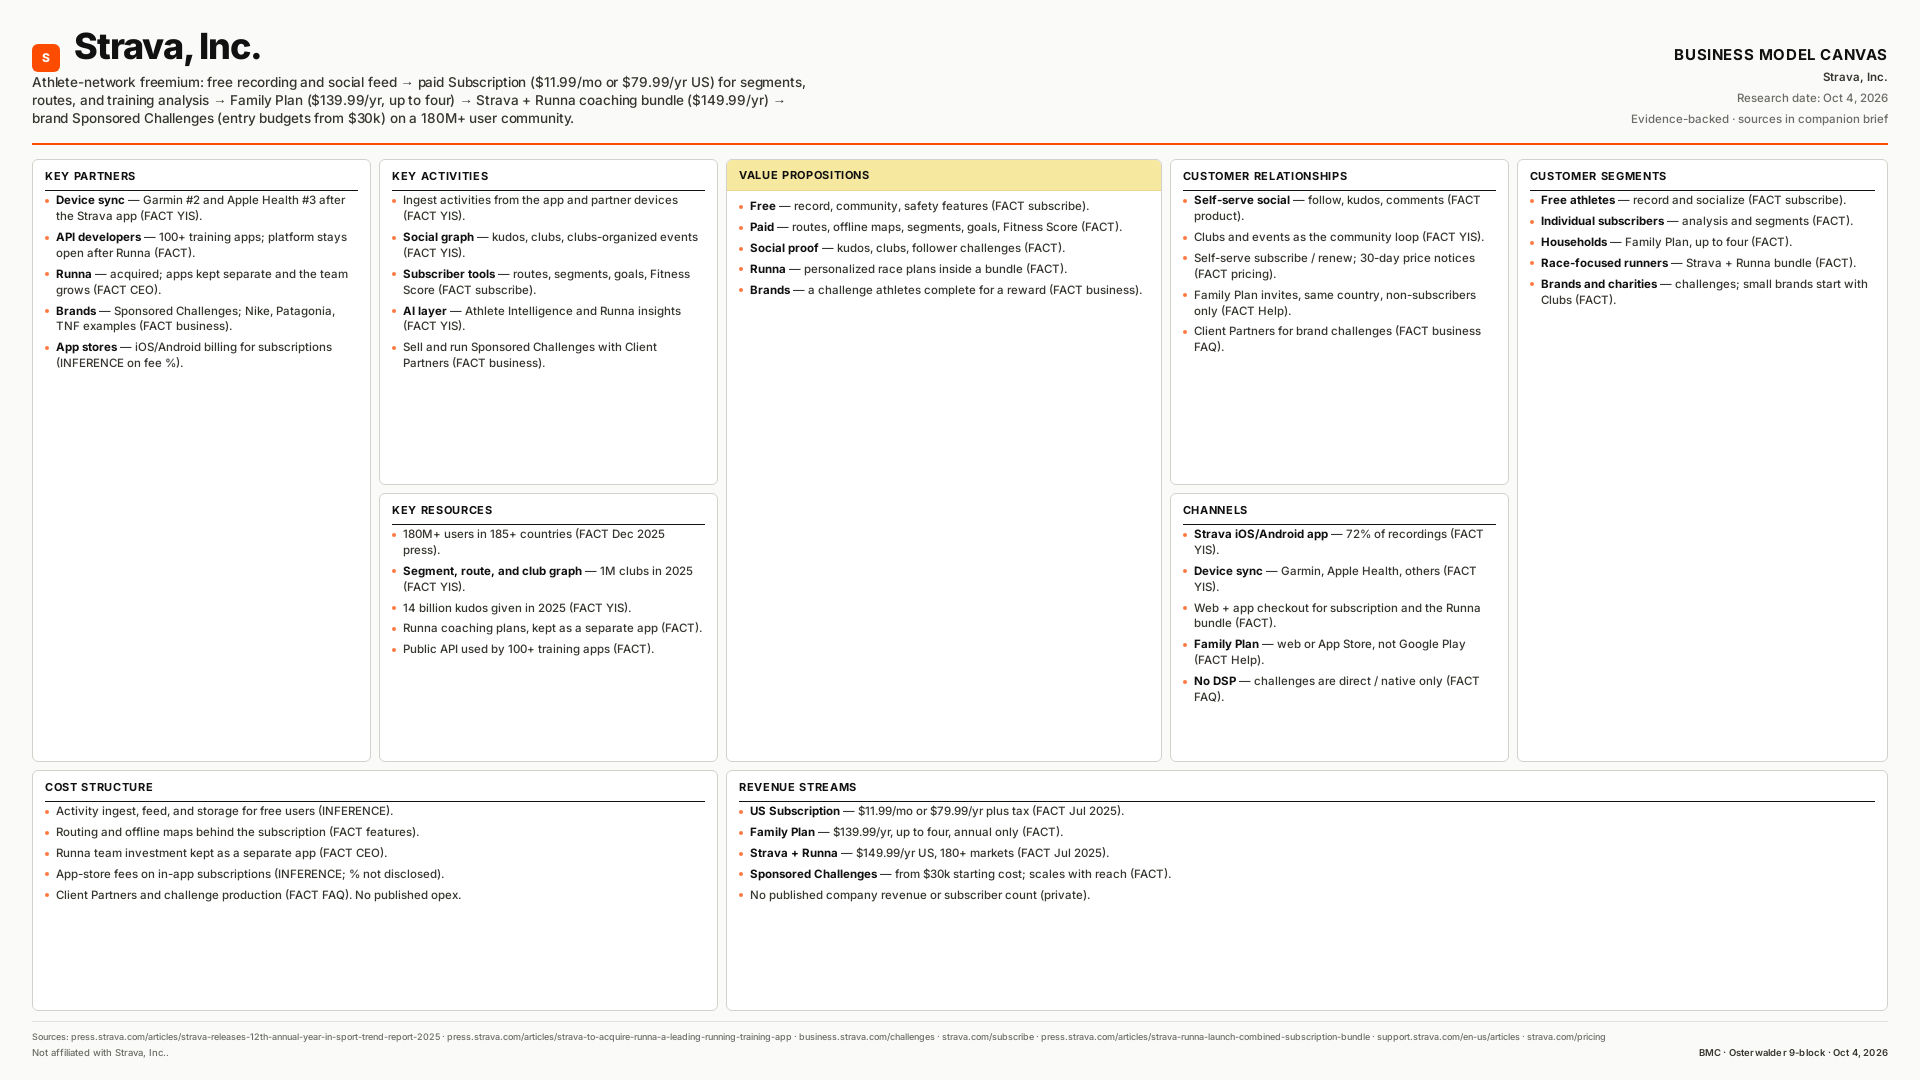

Strava, Inc.
Freemium athlete network → Subscription → Family / Runna → Sponsored Challenges.
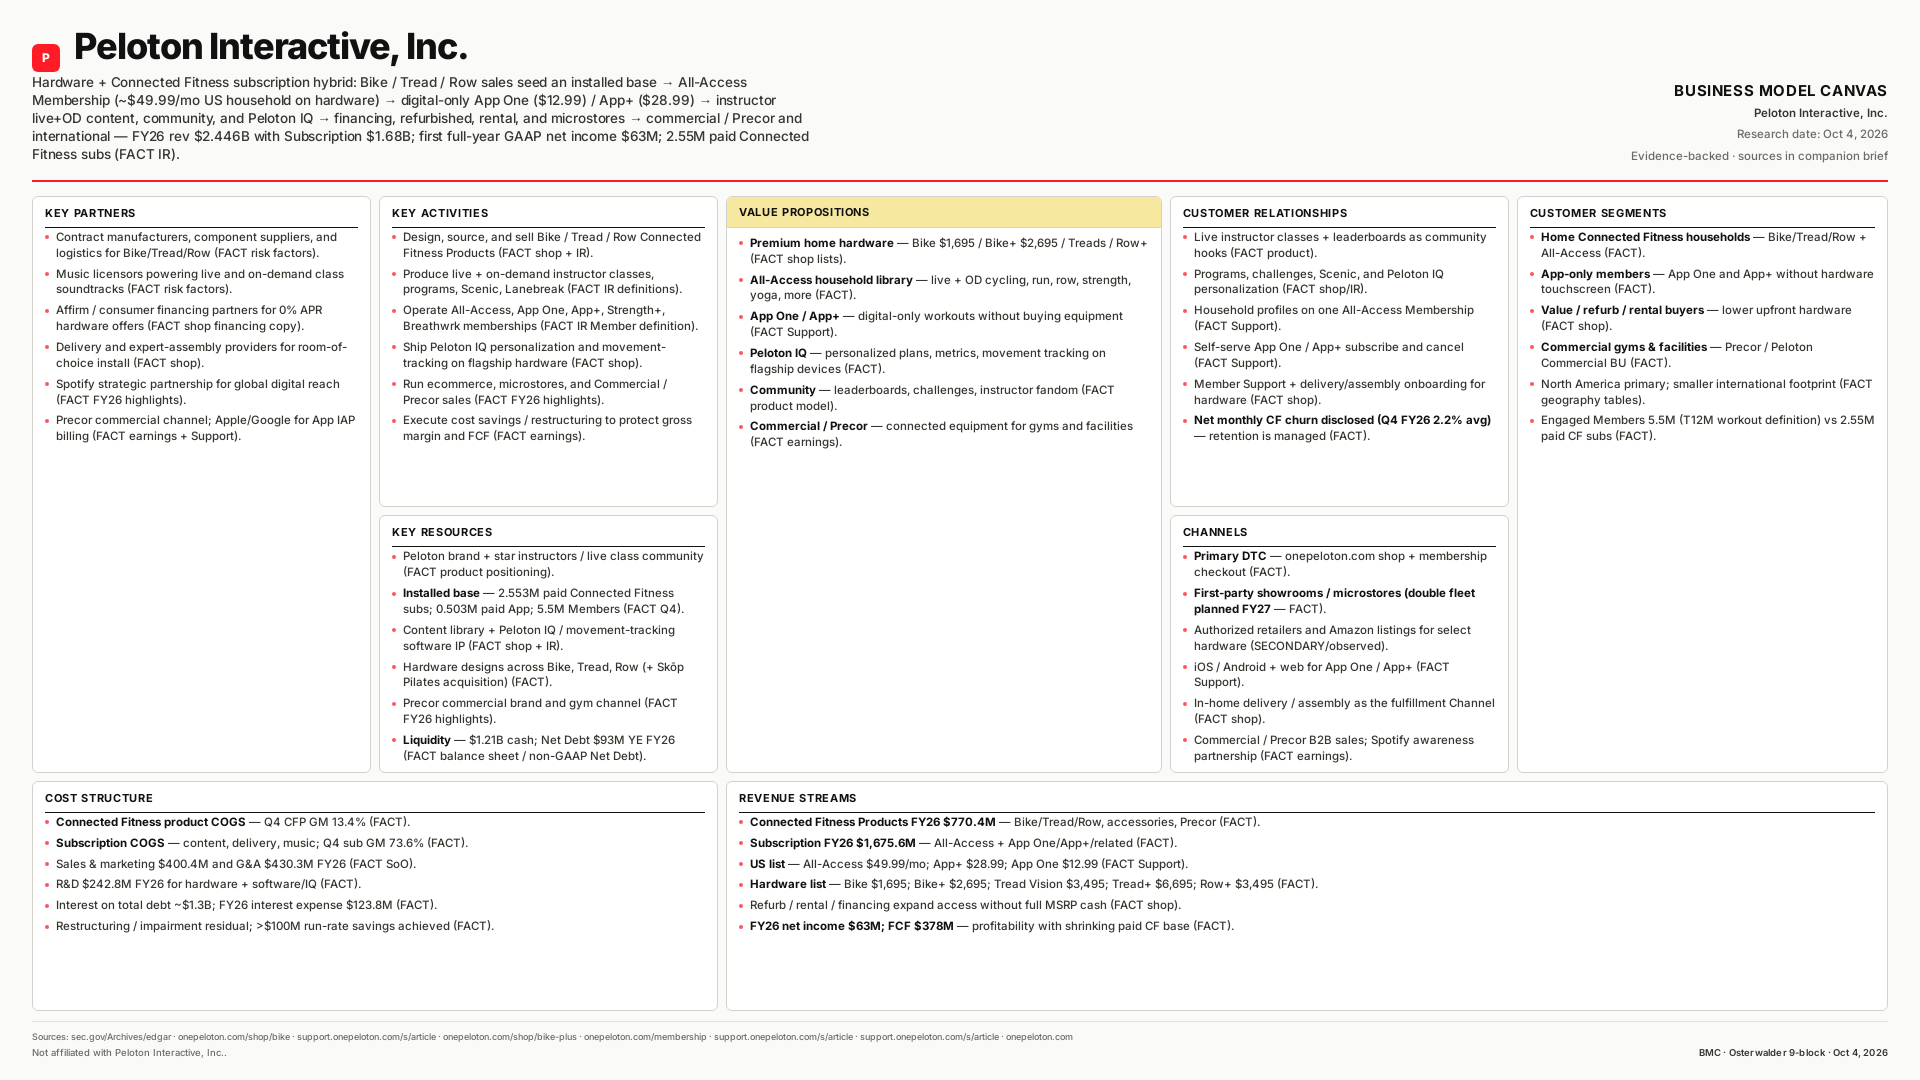

Peloton Interactive, Inc.
Hardware + Connected Fitness sub → All-Access → App One/App+ → commercial/Precor.
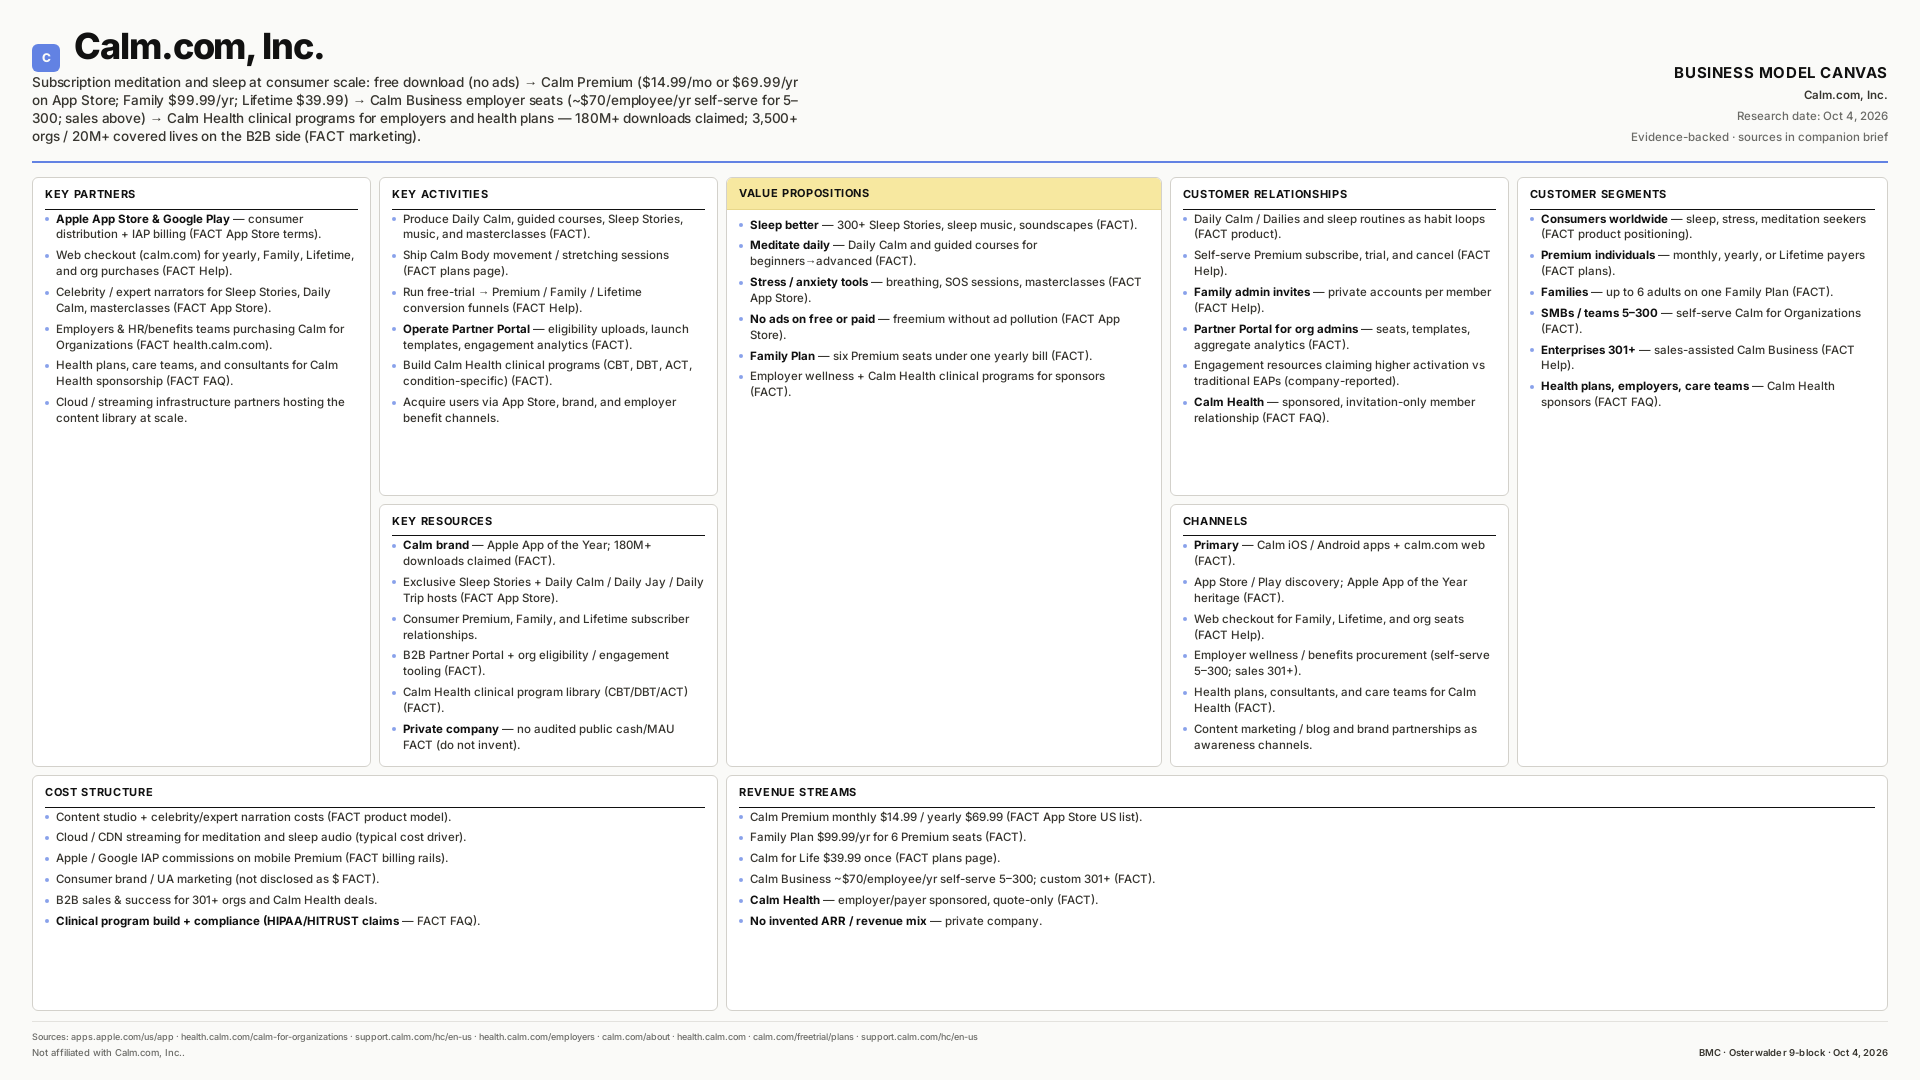

Calm.com, Inc.
Subscription meditation → Premium / Family → Calm Business B2B → Calm Health.
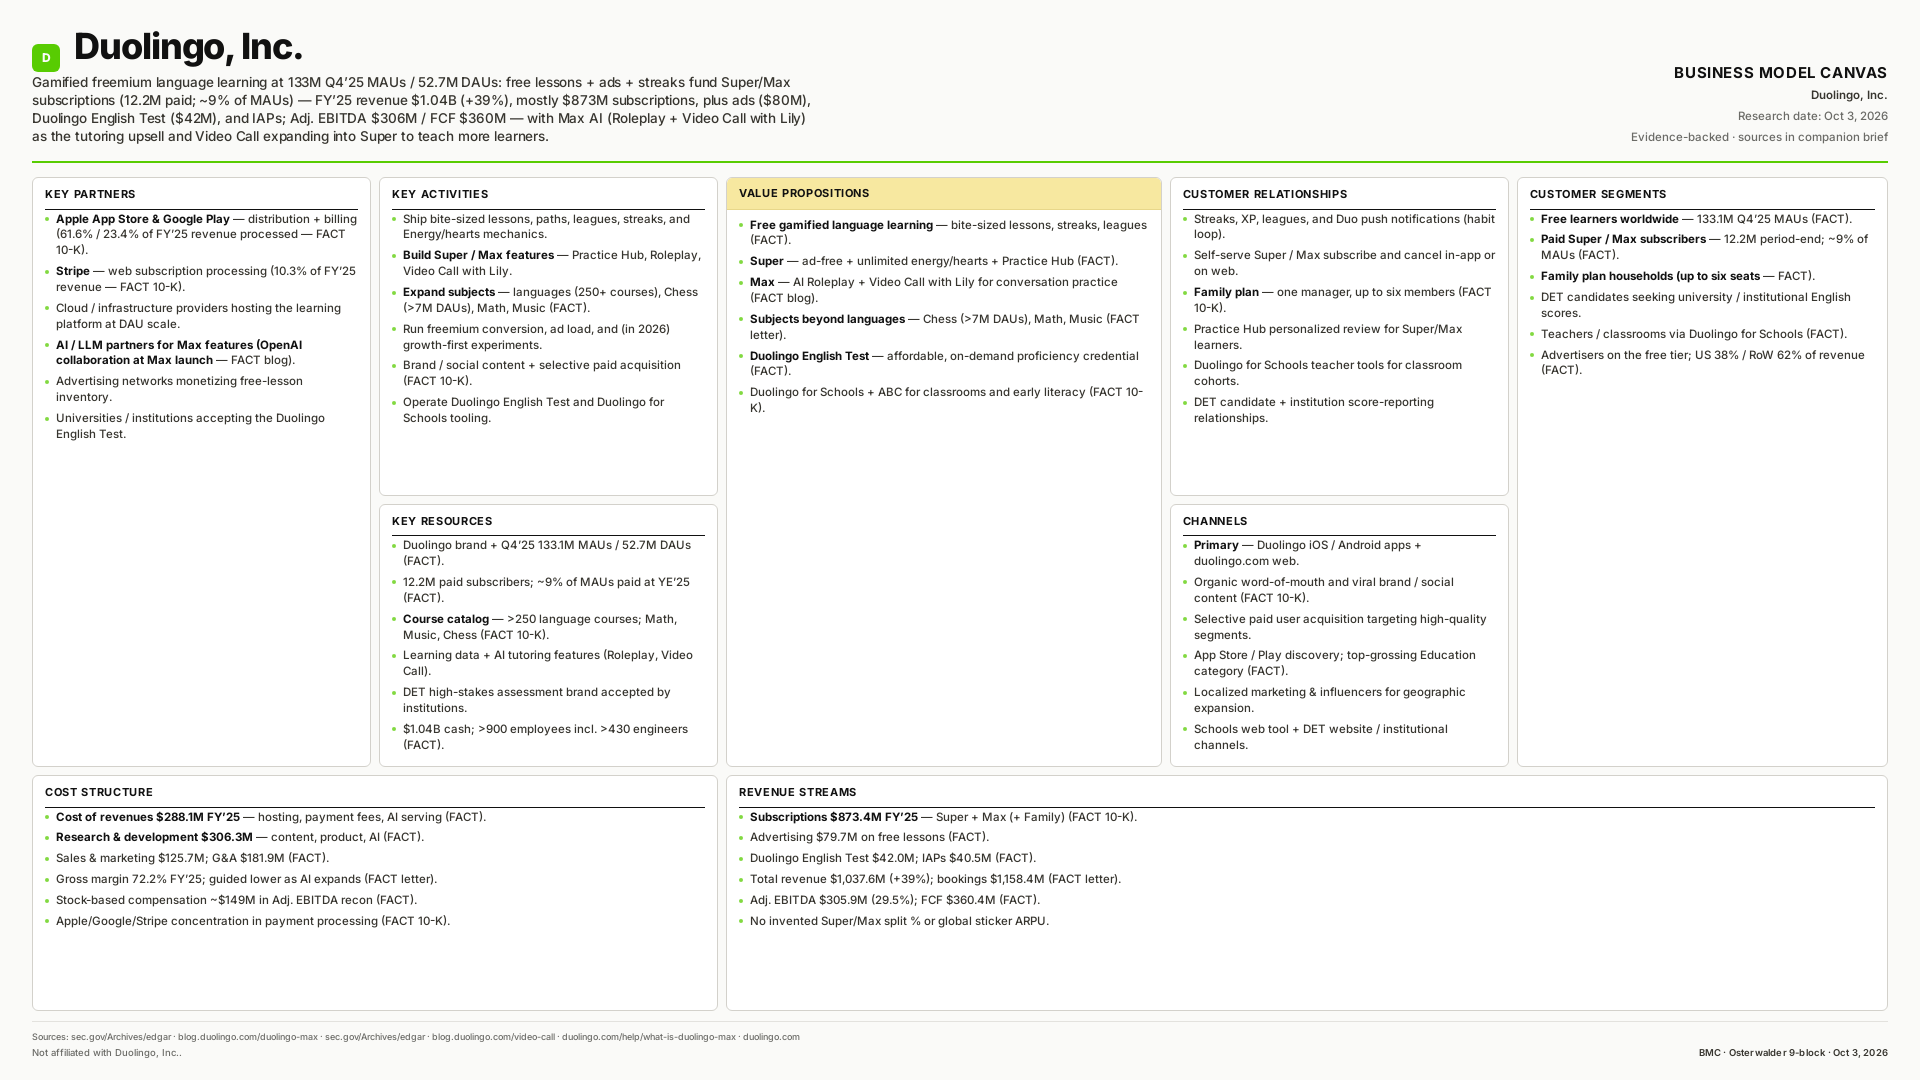

Duolingo, Inc.
Gamified freemium → Super/Max AI tutoring → ads + DET + IAPs.
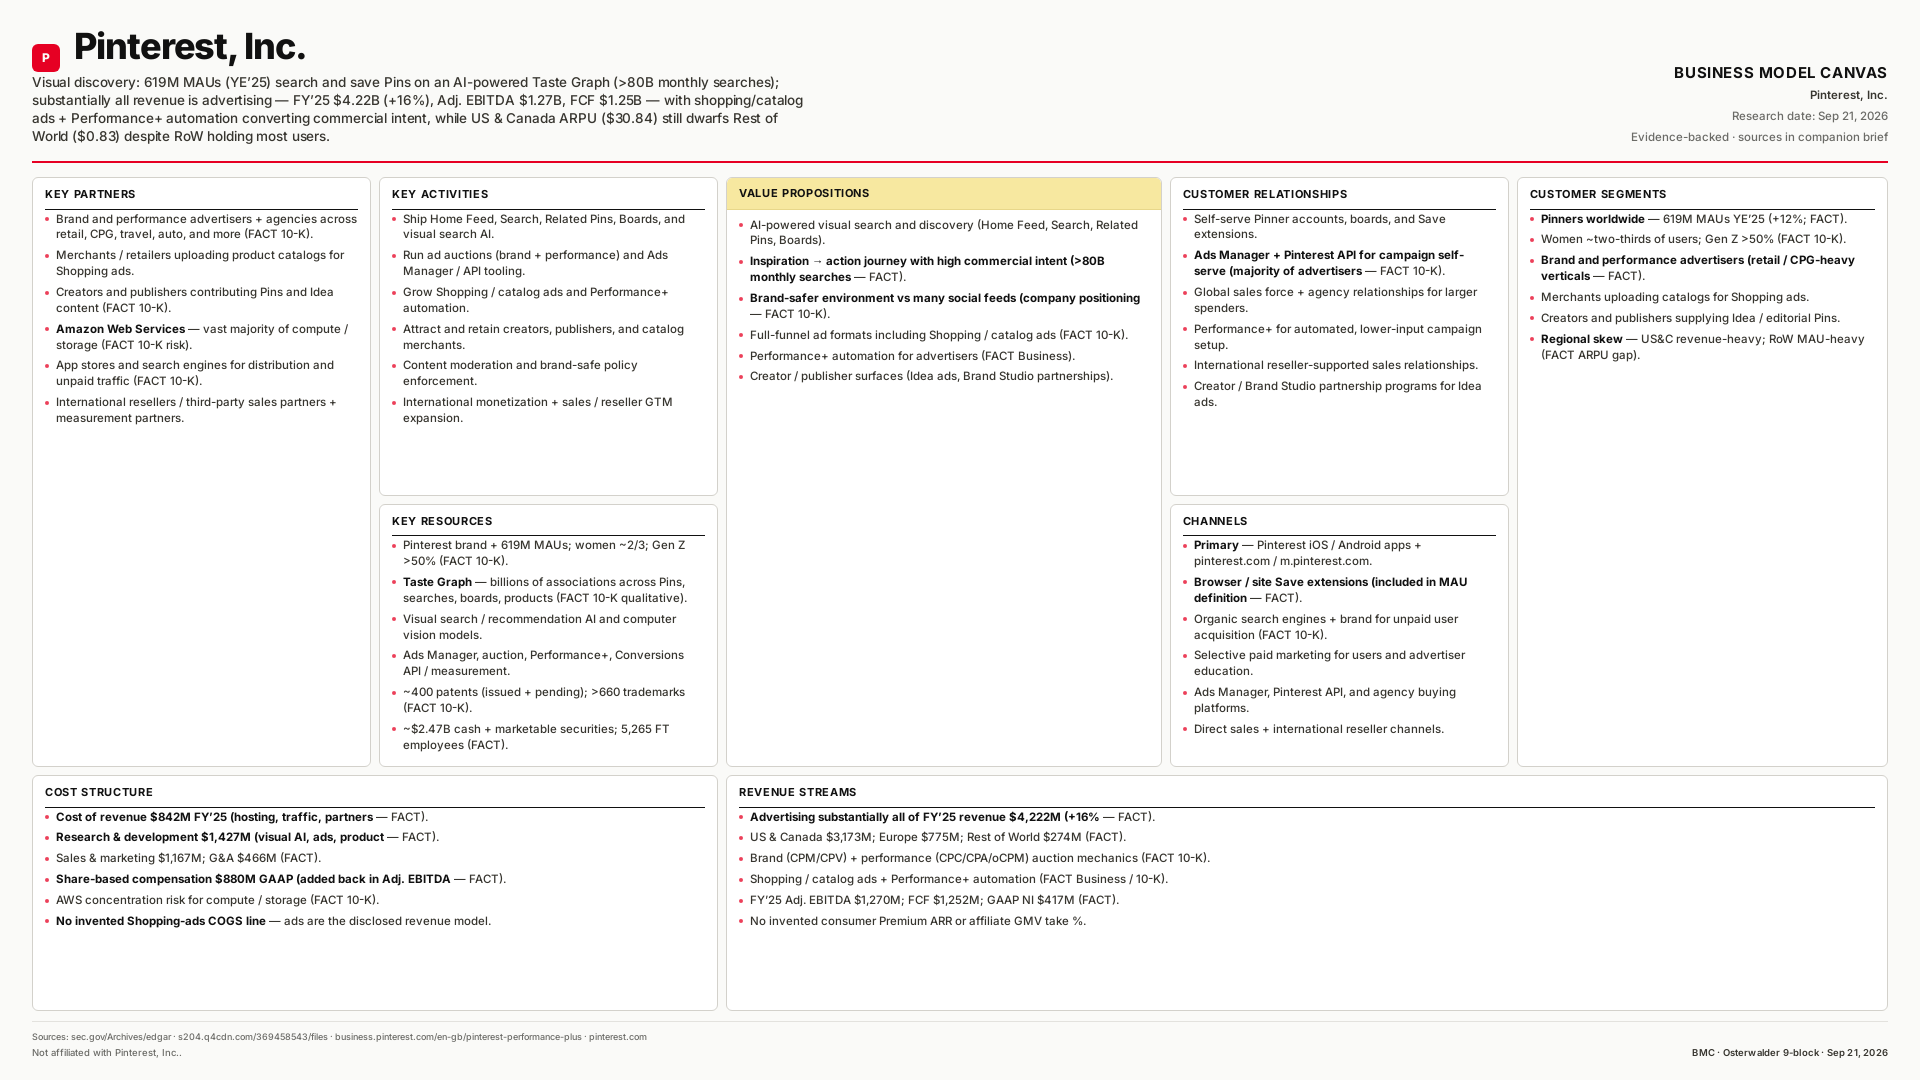

Pinterest, Inc.
Visual discovery → ads → shopping/catalog + Performance+ → creators → international ARPU catch-up.
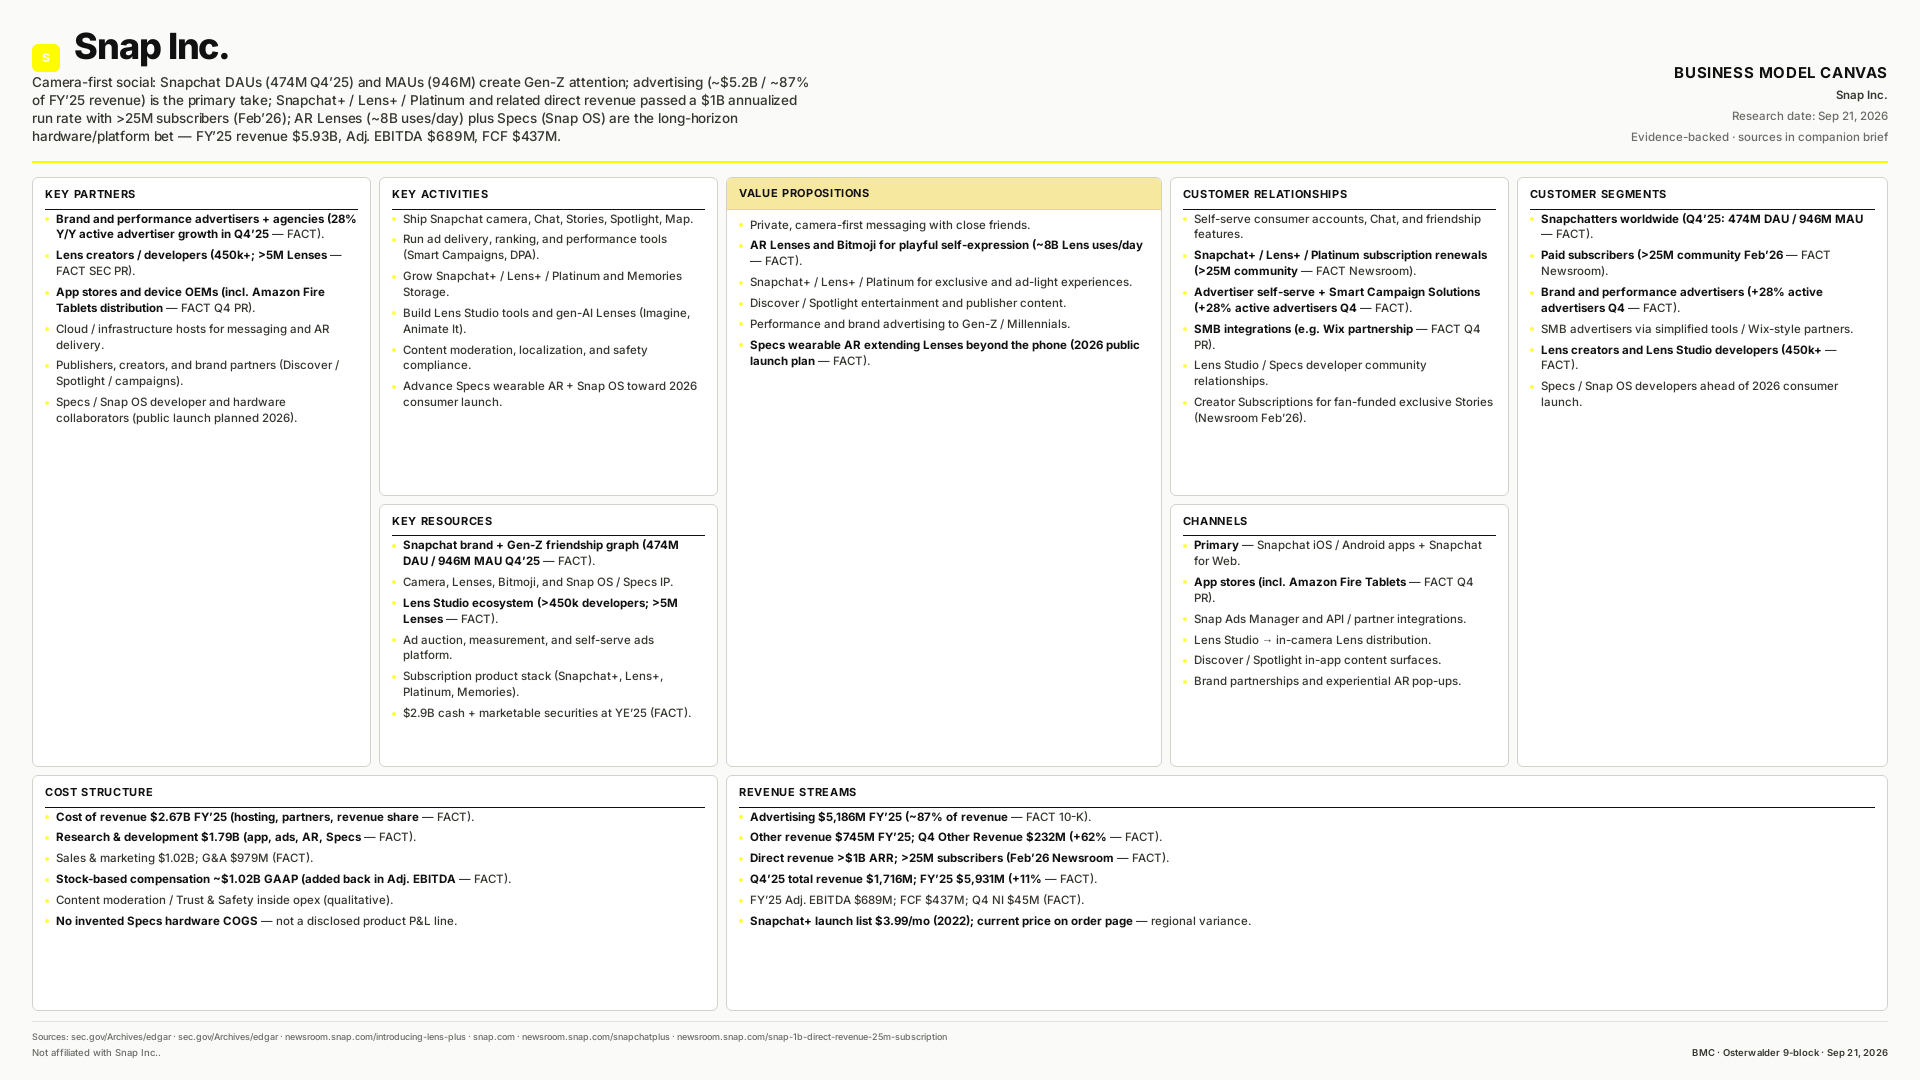

Snap Inc.
Camera/social → Snapchat+ → advertising → AR Lenses → Specs/Snap OS → content partnerships.
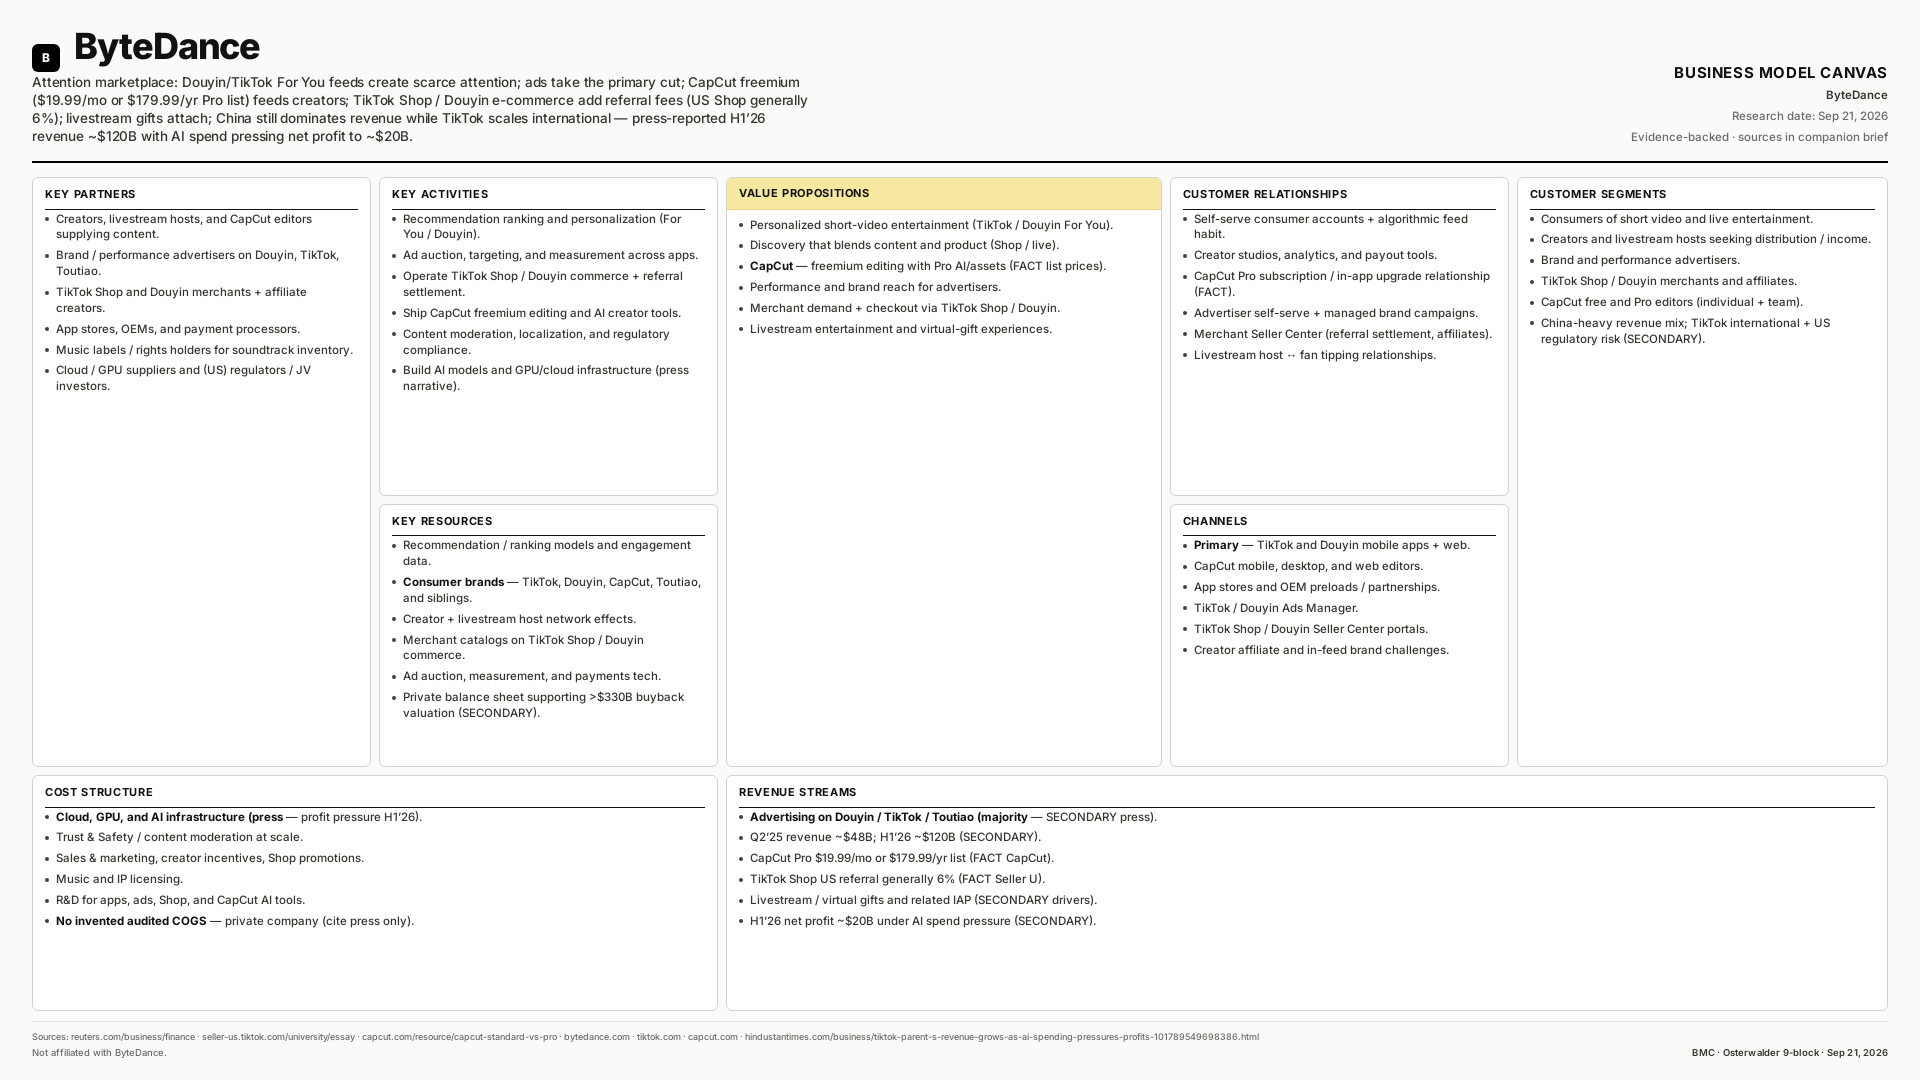

ByteDance
Attention marketplace: Douyin/TikTok For You → ads take → CapCut freemium ($19.99/$179.99) → Shop/Douyin e-commerce (US referral ~6%) → livestream gifts → intl + AI spend.
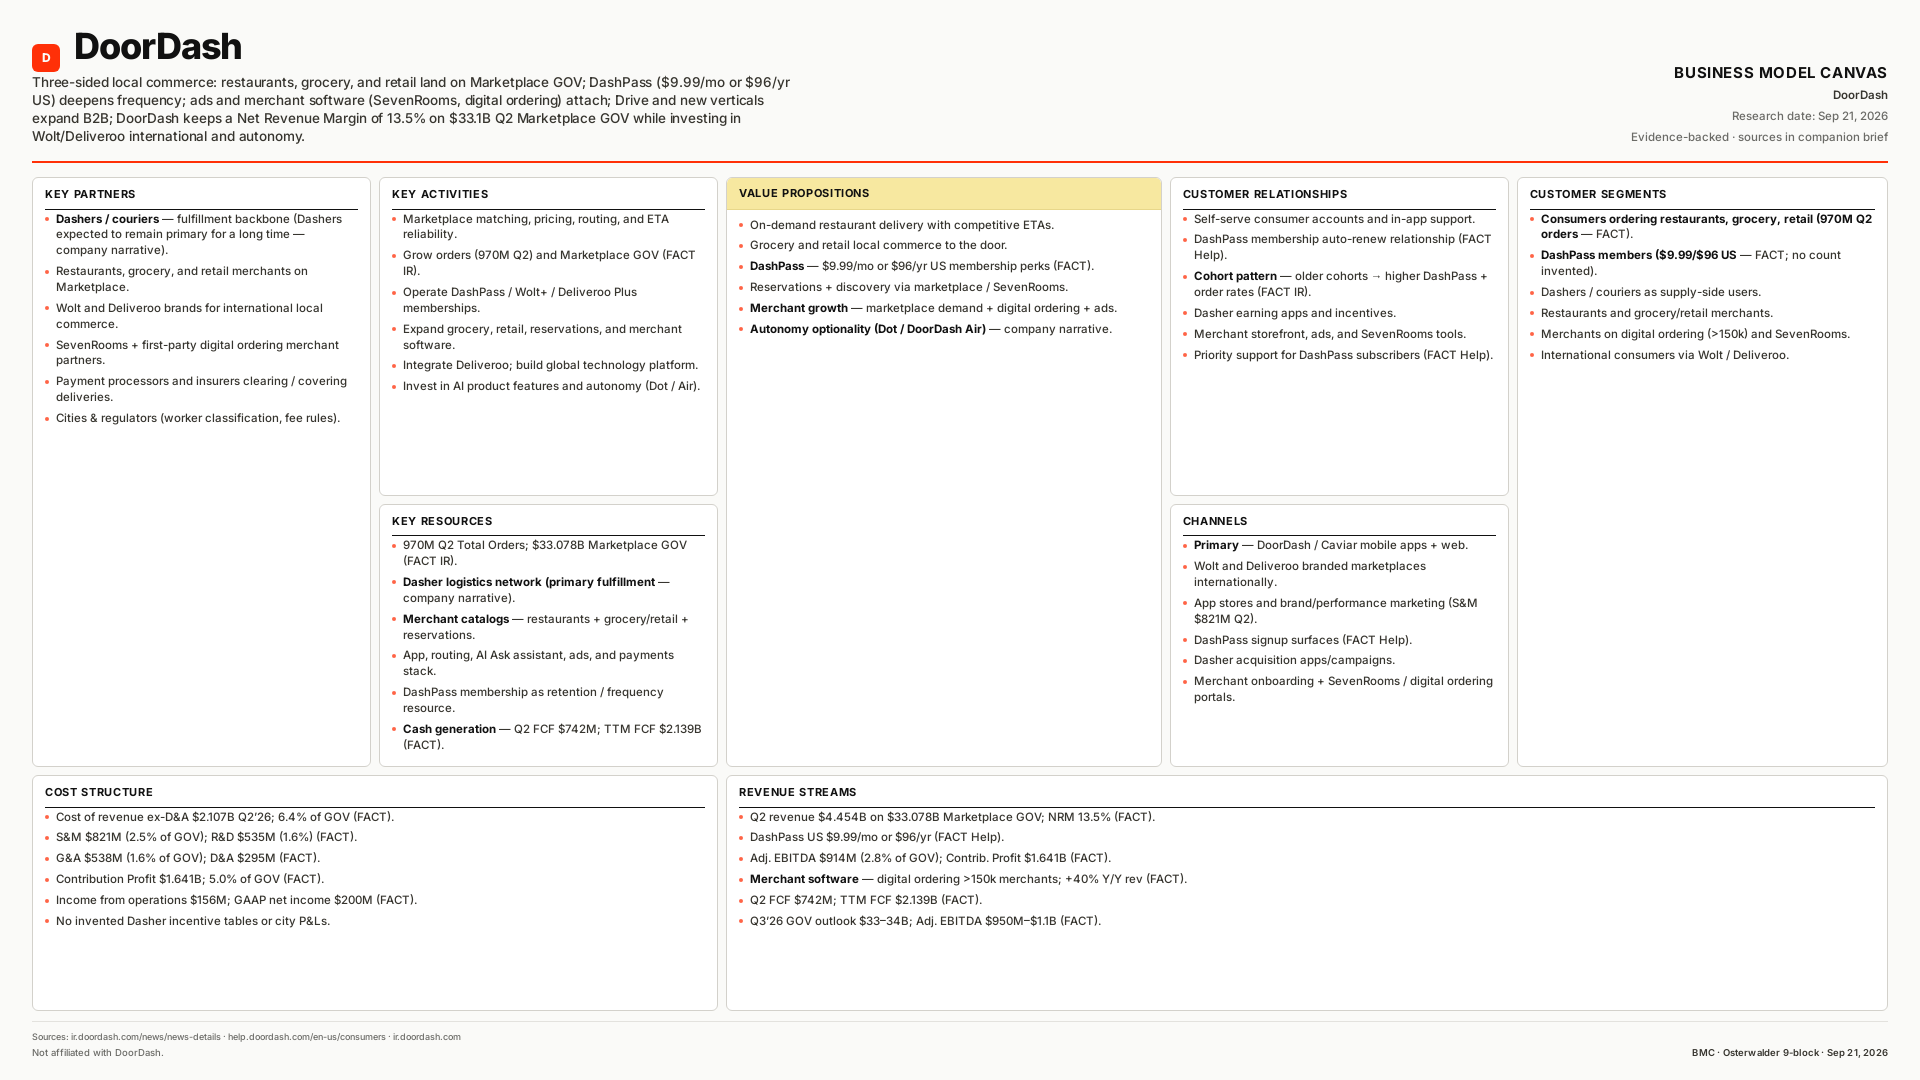

DoorDash
Three-sided local commerce: Marketplace GOV take-rate, DashPass membership, merchant software/ads, grocery & retail, then international + autonomy.
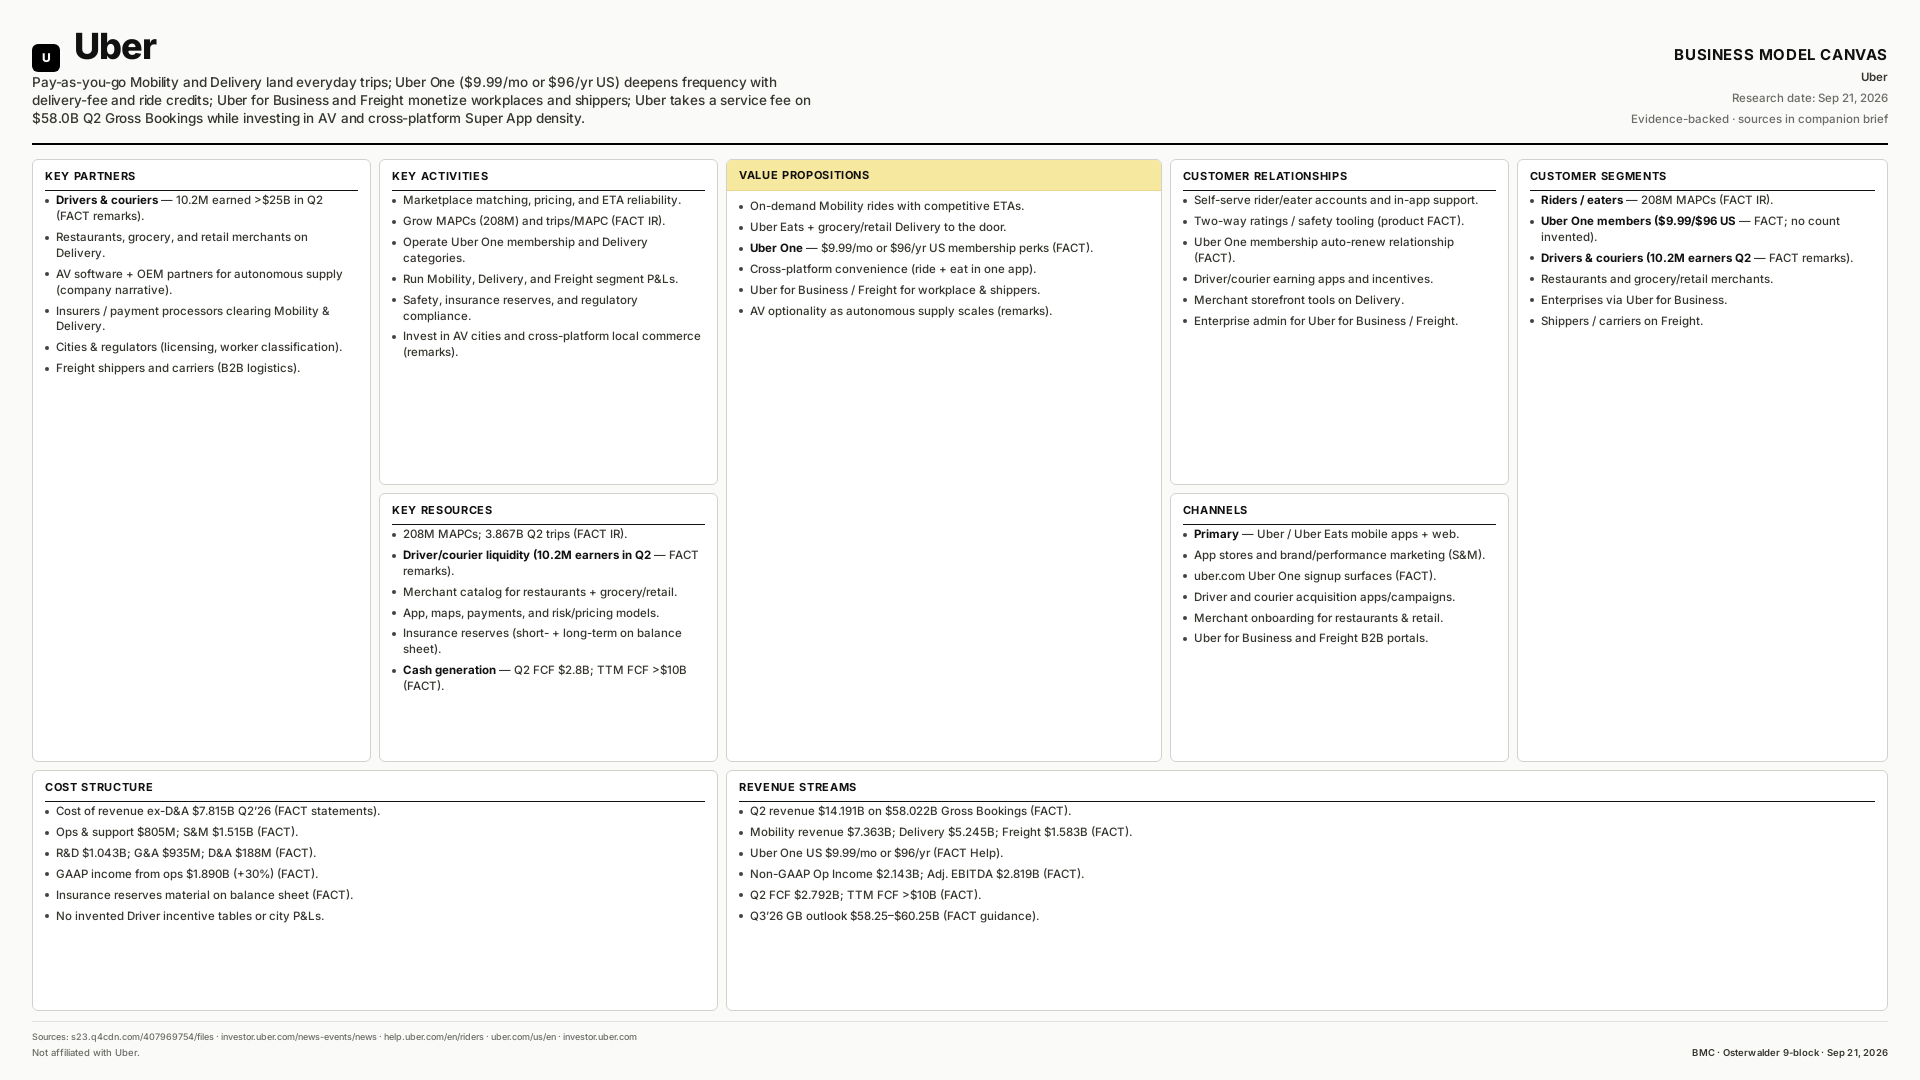
Uber
Marketplace take-rate: Mobility → Delivery → Uber One ($9.99/$96) → Business/Freight → GB fees → AV/Super App.
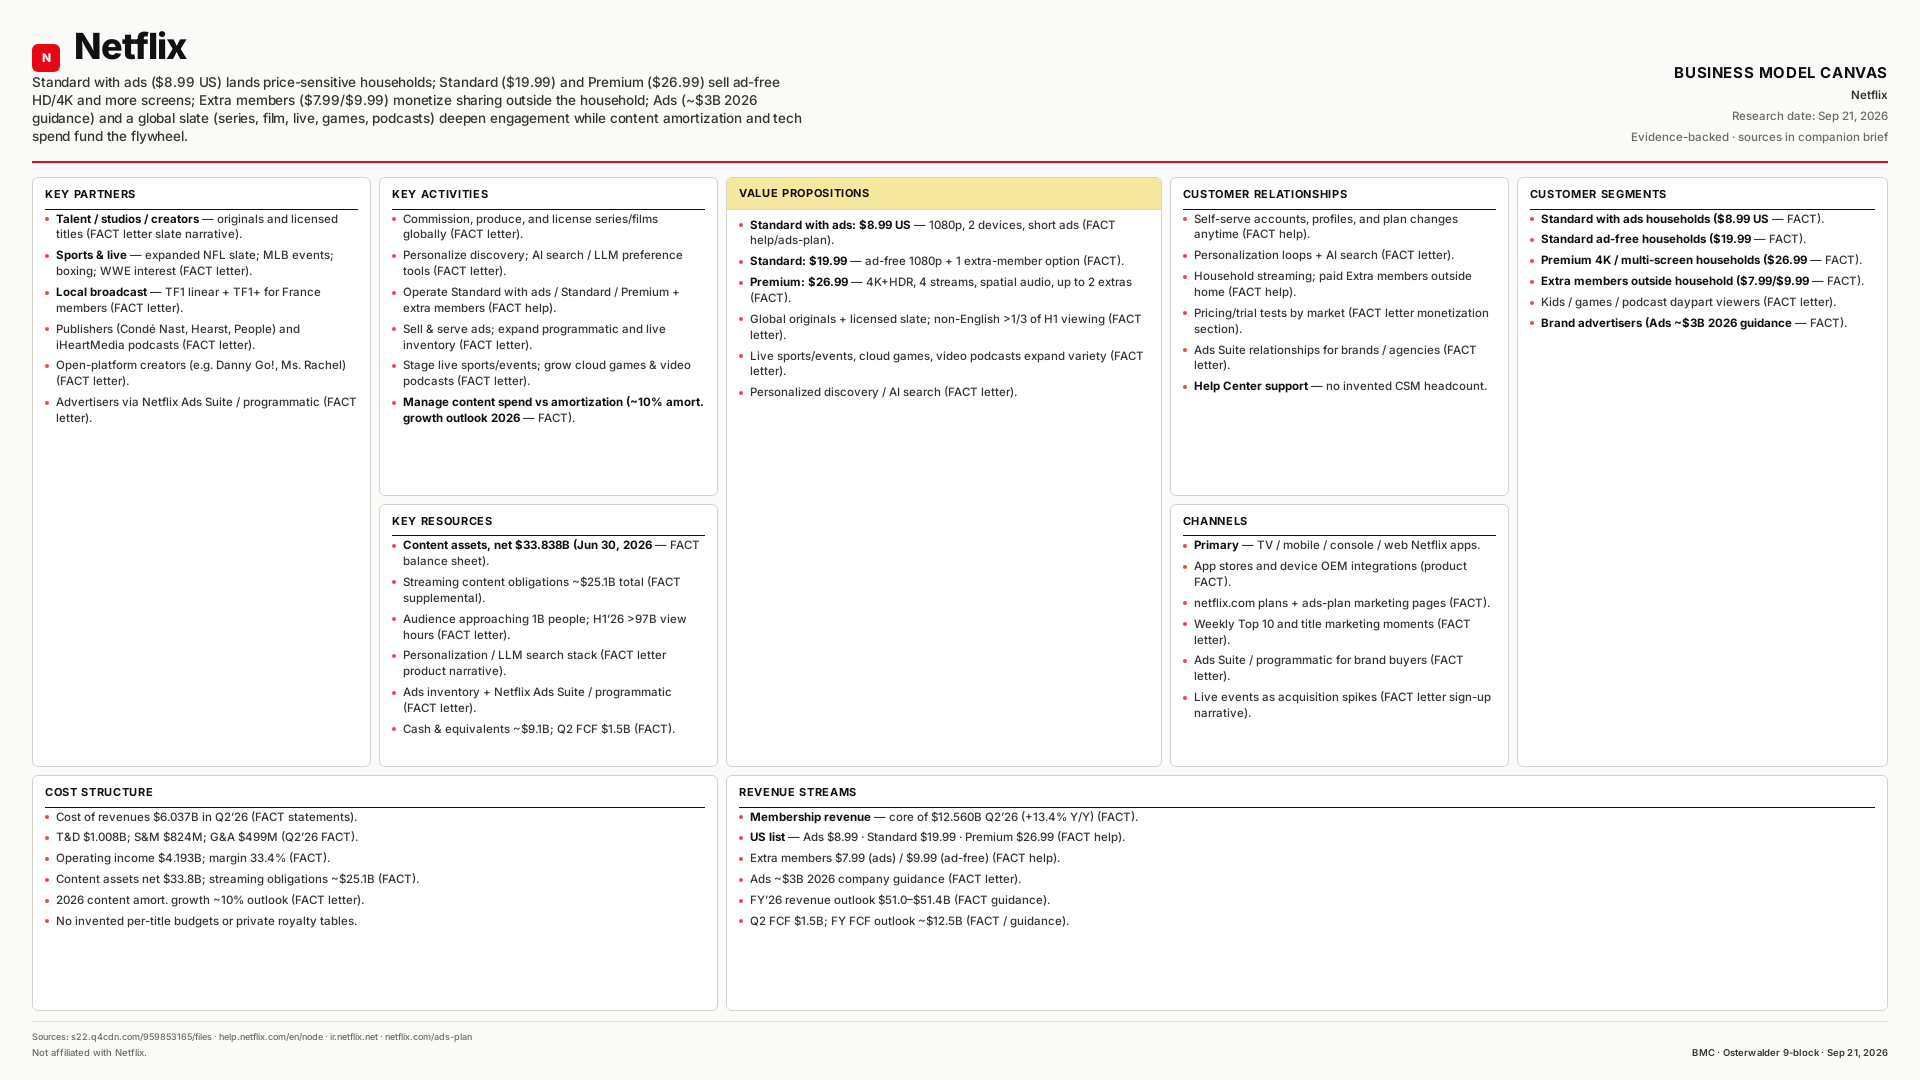
Netflix
SVOD + ads: Standard with ads → Standard → Premium → Extra members → Ads (~$3B ’26) → live/games/partners.
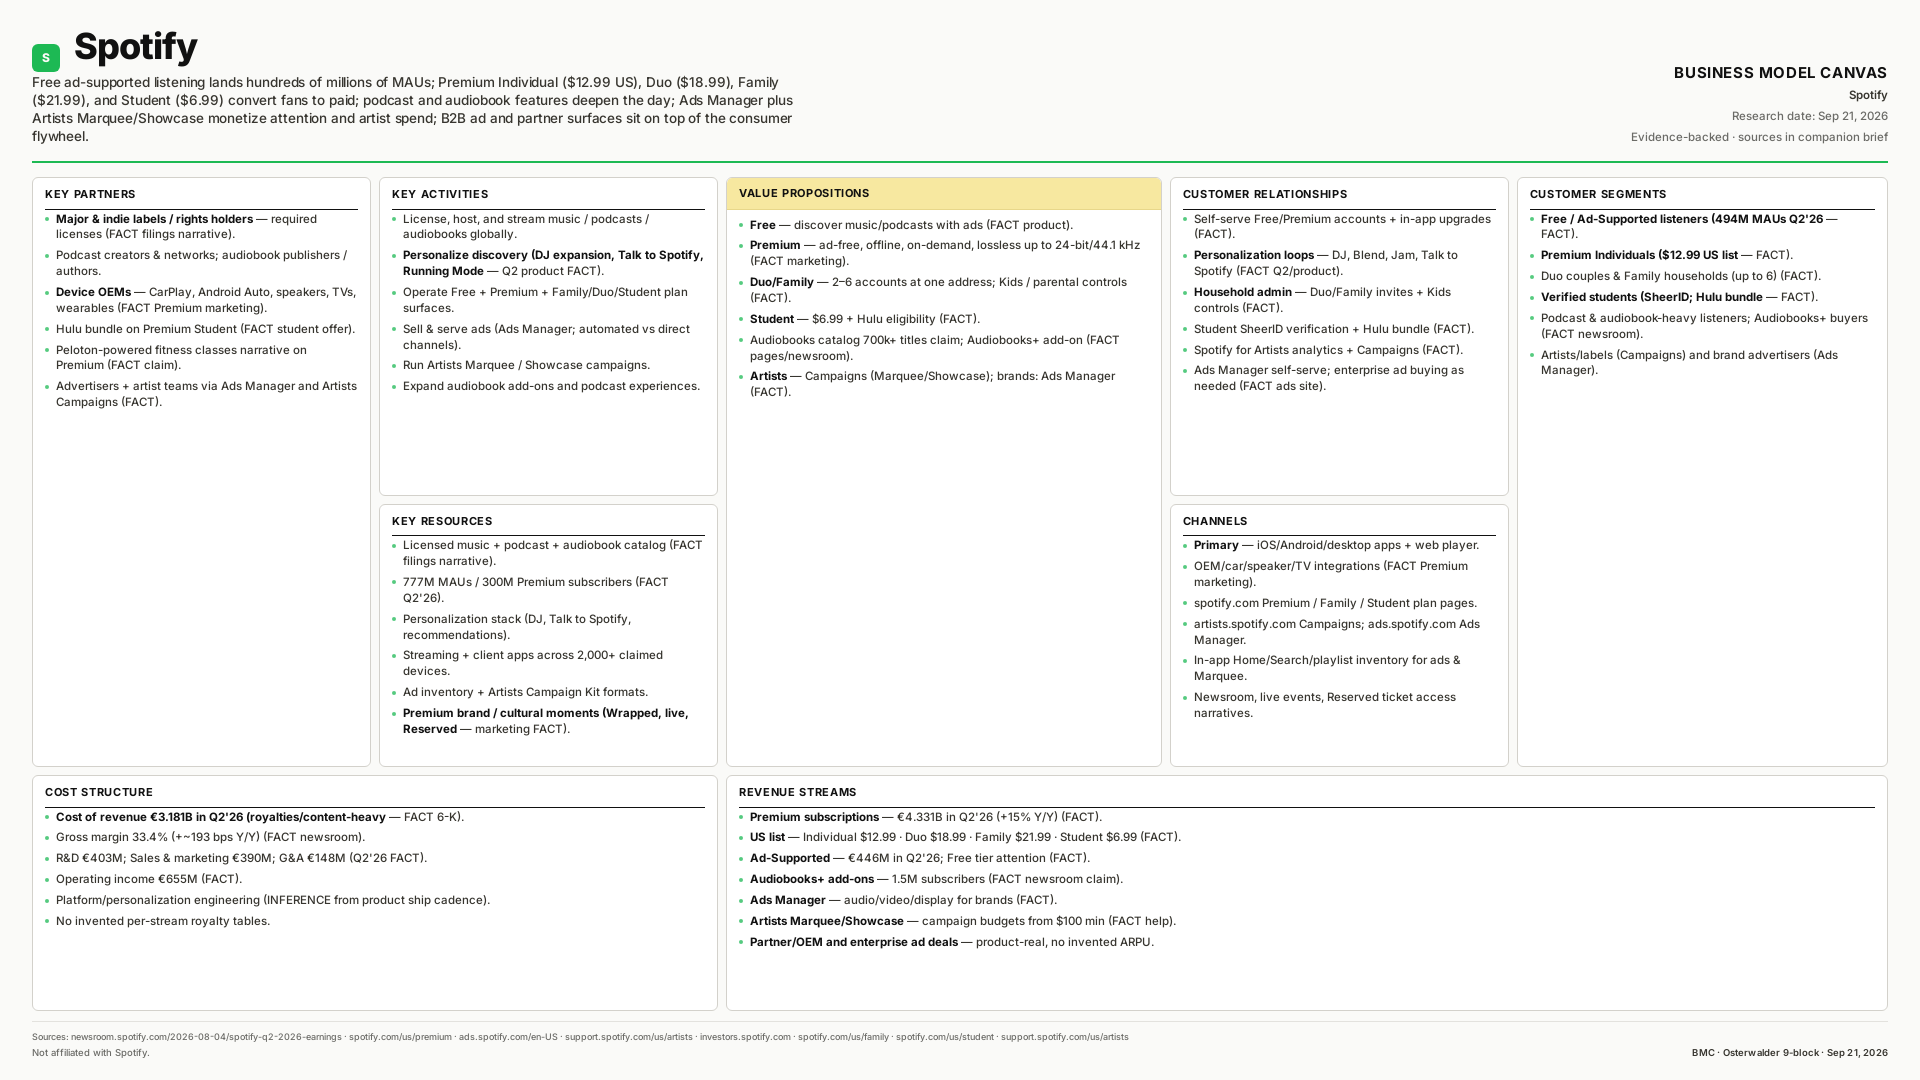
Spotify
Freemium audio: Free ads → Premium plans → podcasts/audiobooks → Ads + Artists marketplace.
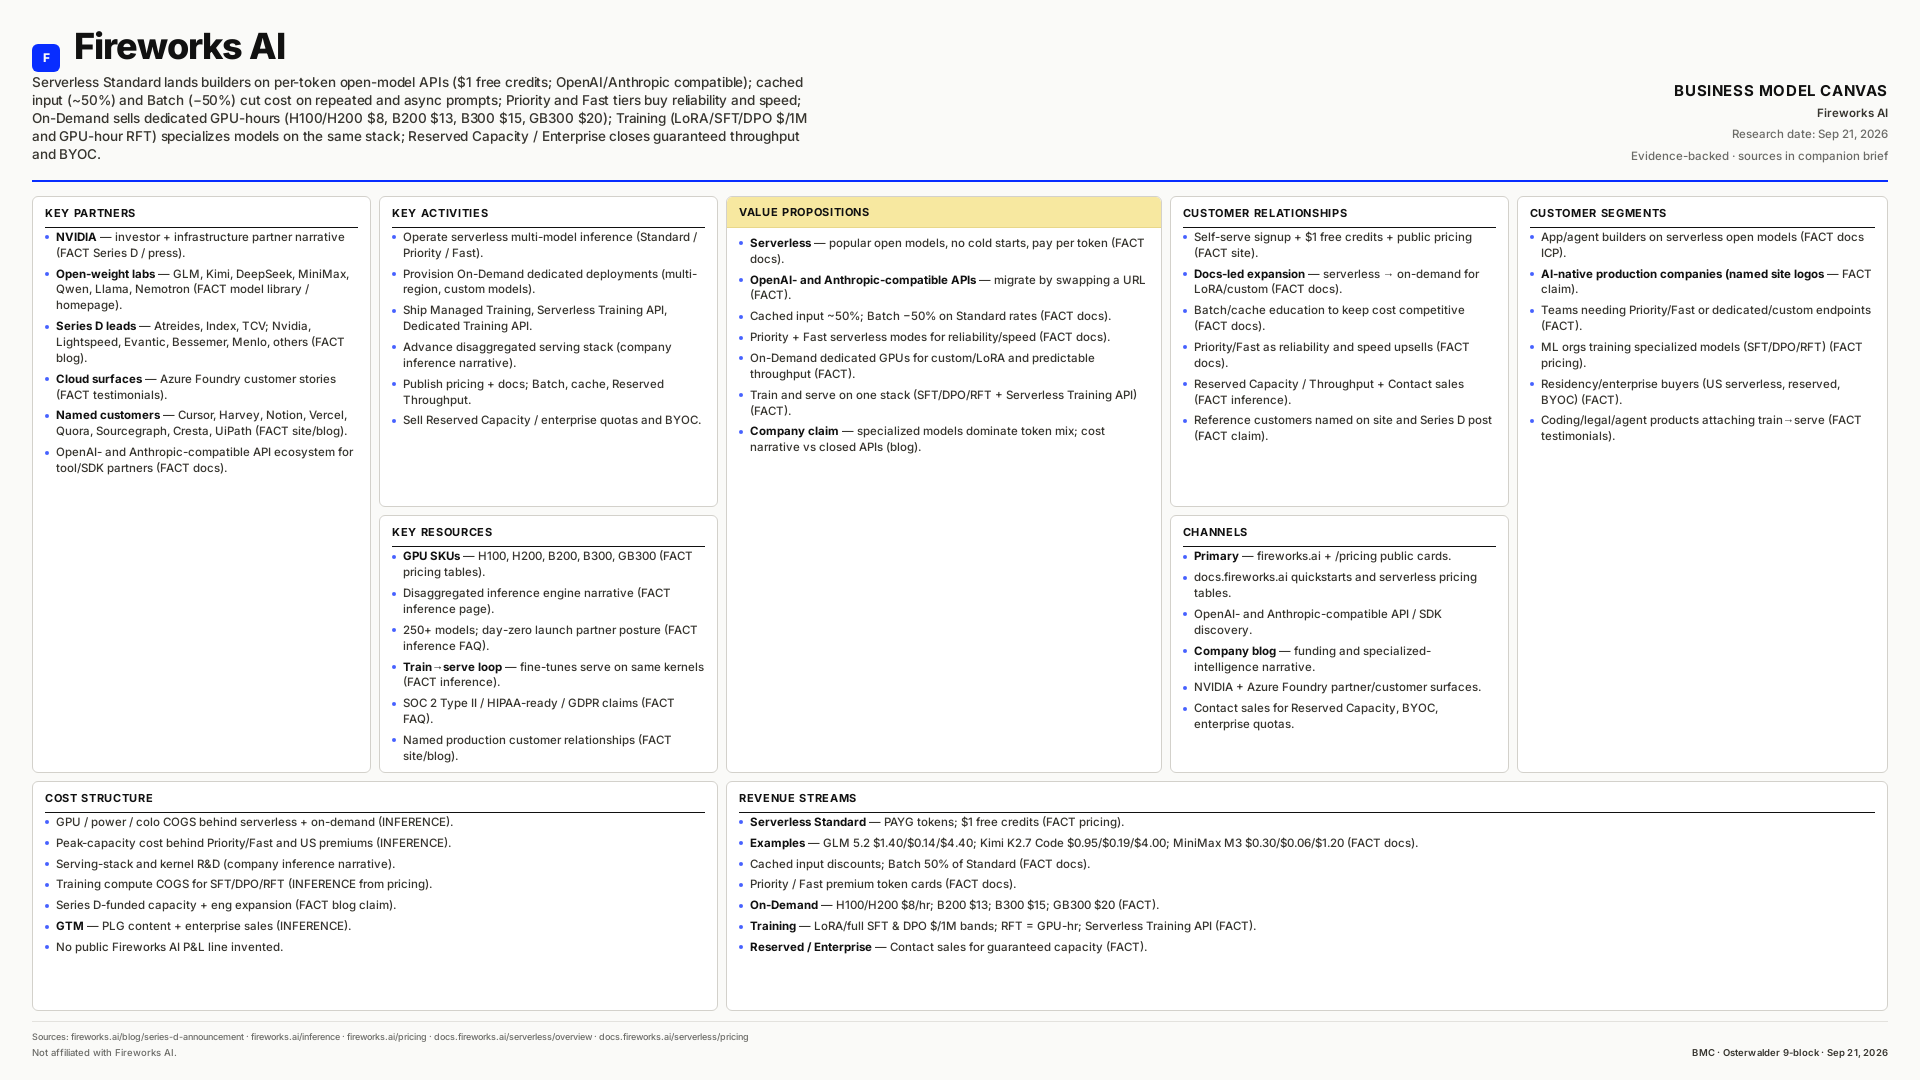
Fireworks AI
Serverless open-model inference with Priority/Fast tiers, On-Demand GPUs, and a train→serve loop for specialized intelligence.
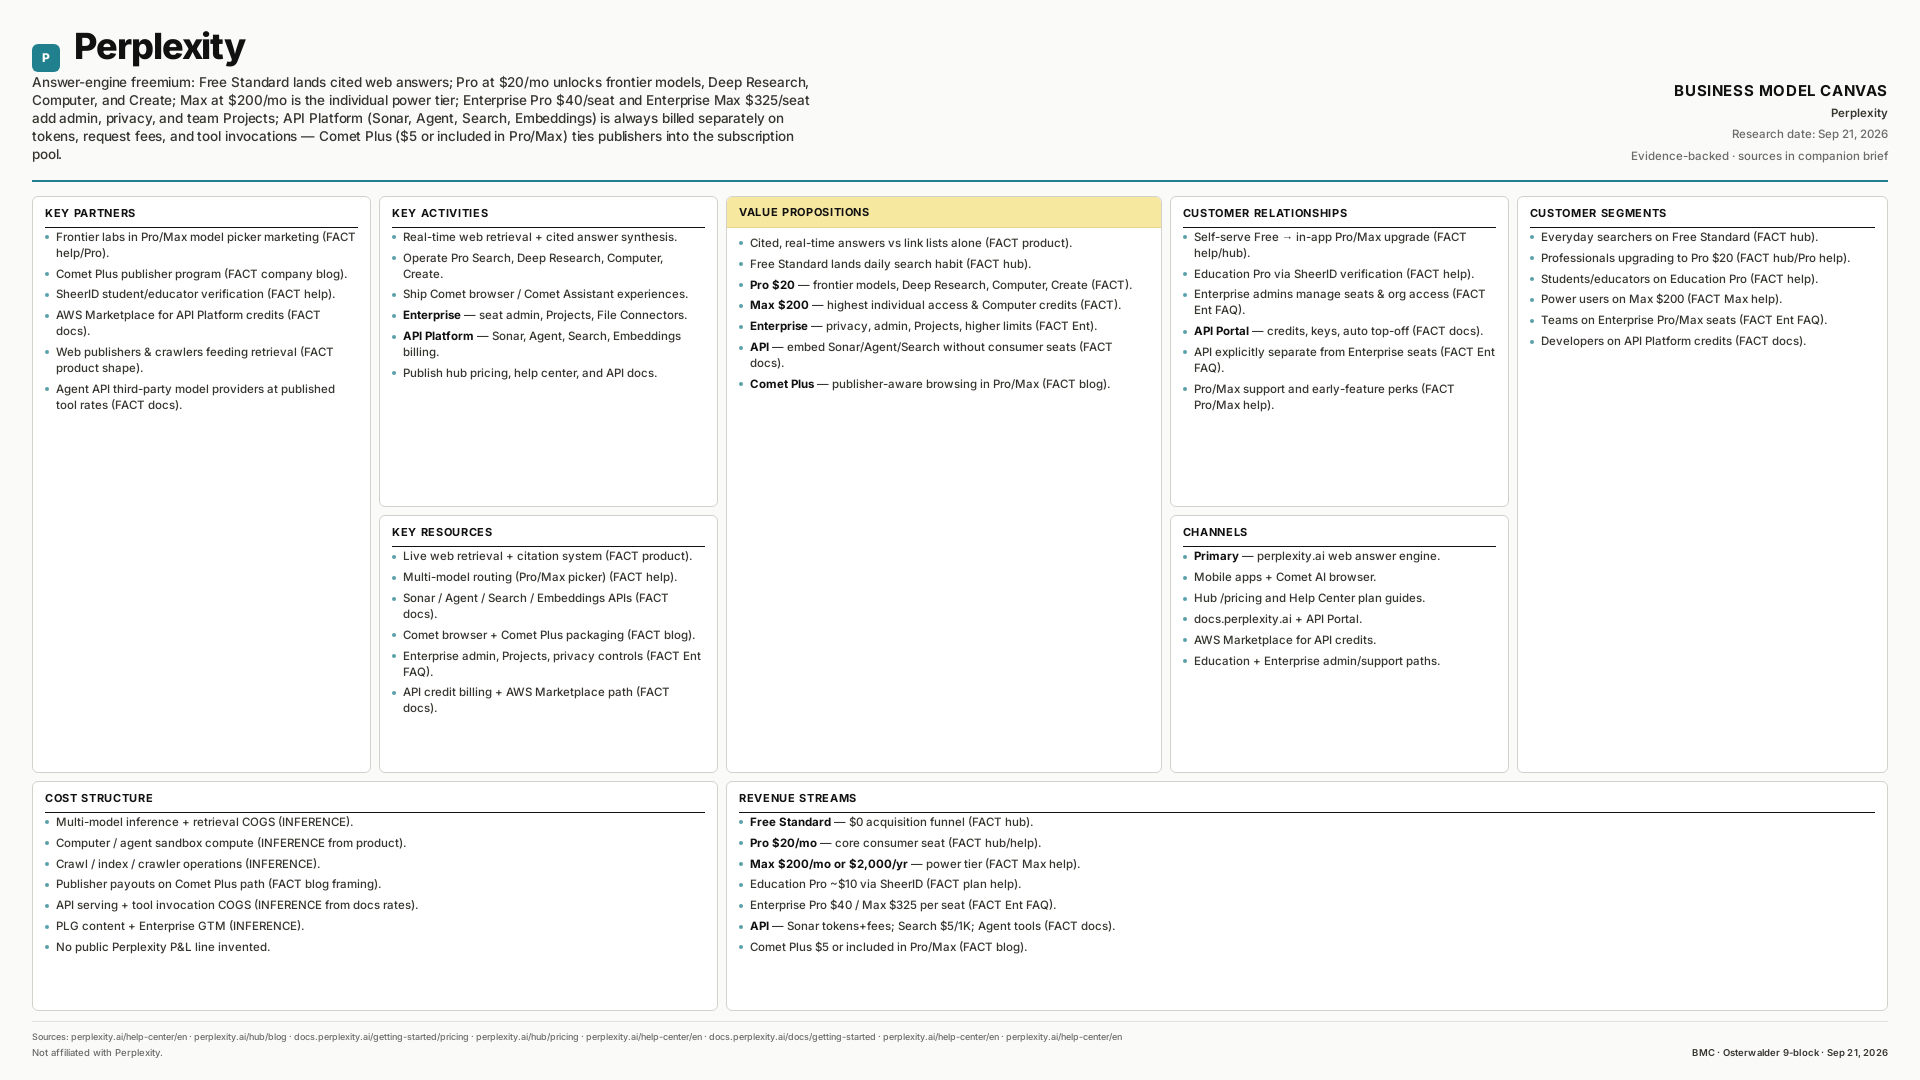
Perplexity
Answer-engine freemium: Free cited search → Pro $20 → Max $200 → Enterprise seats → API PAYG.
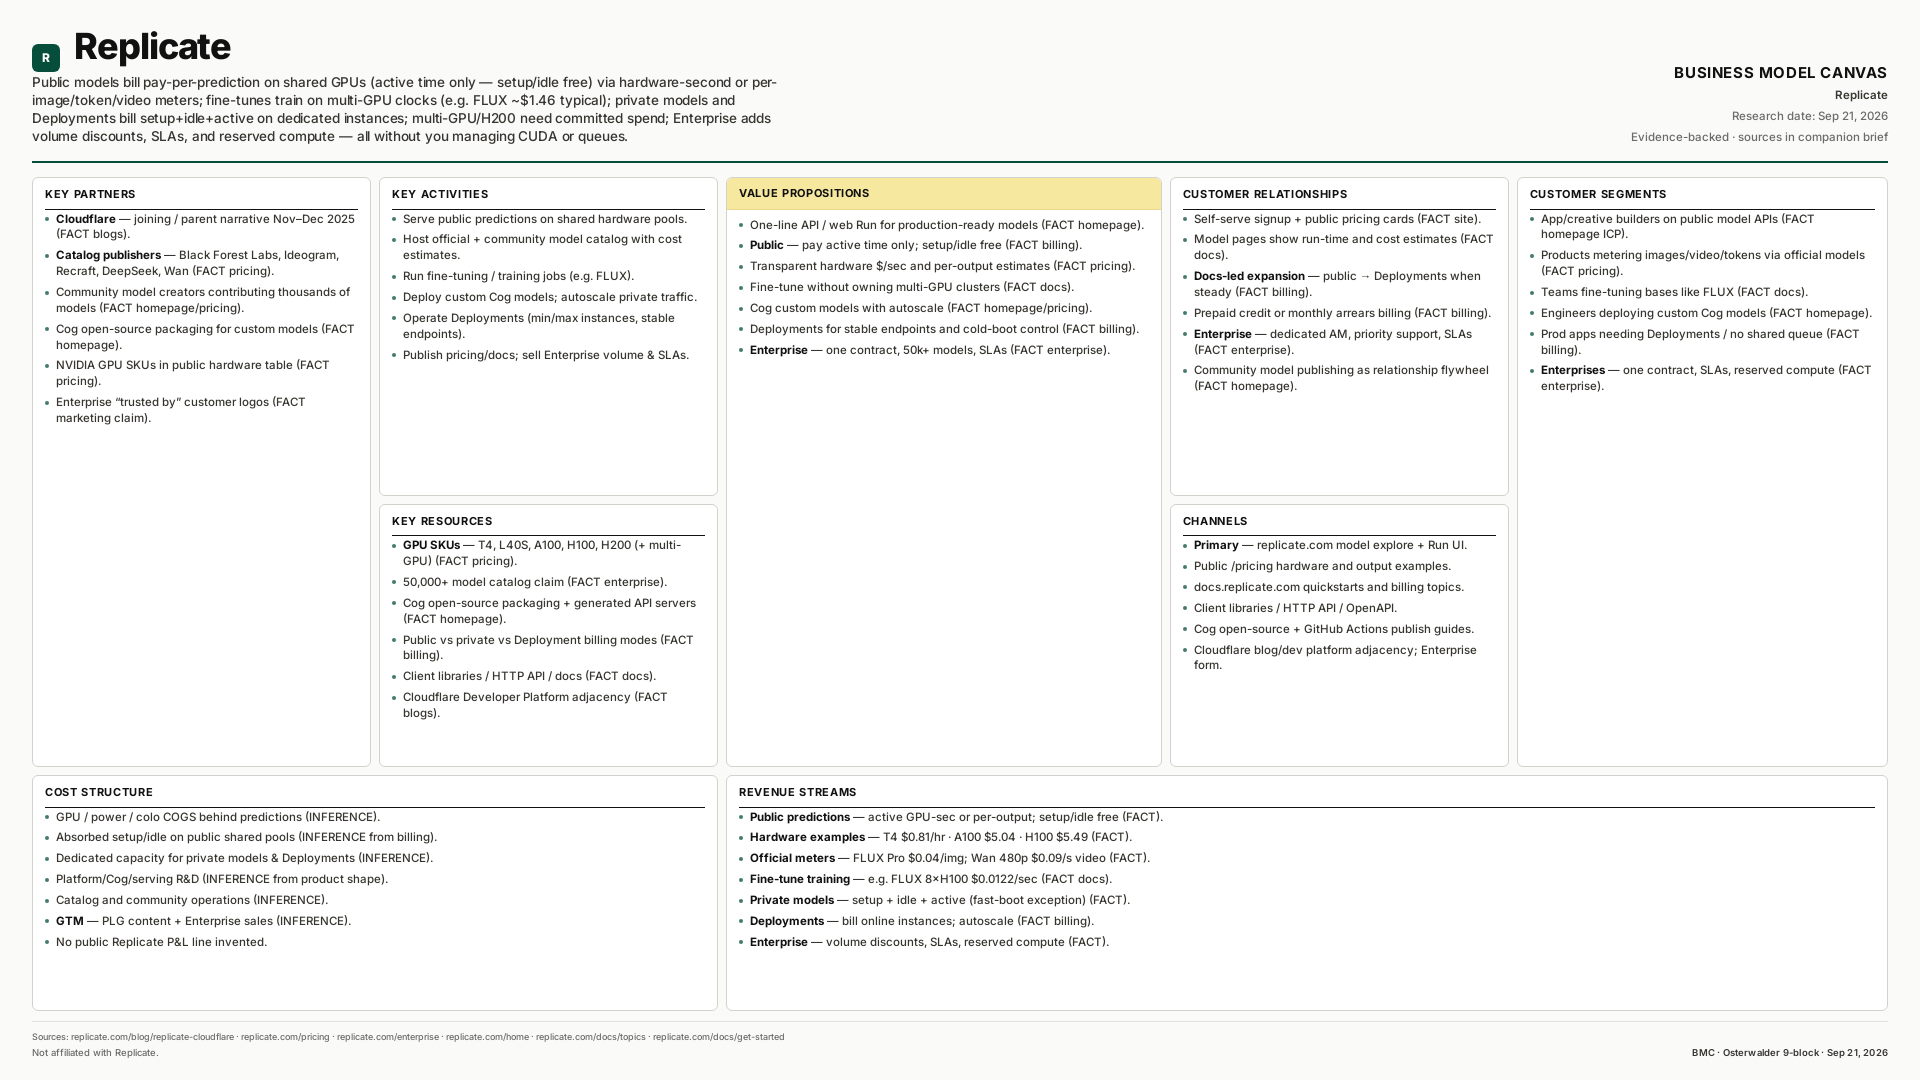
Replicate
Pay-per-prediction model marketplace: public active-only GPU-sec → fine-tune → private/Deployments → Enterprise.
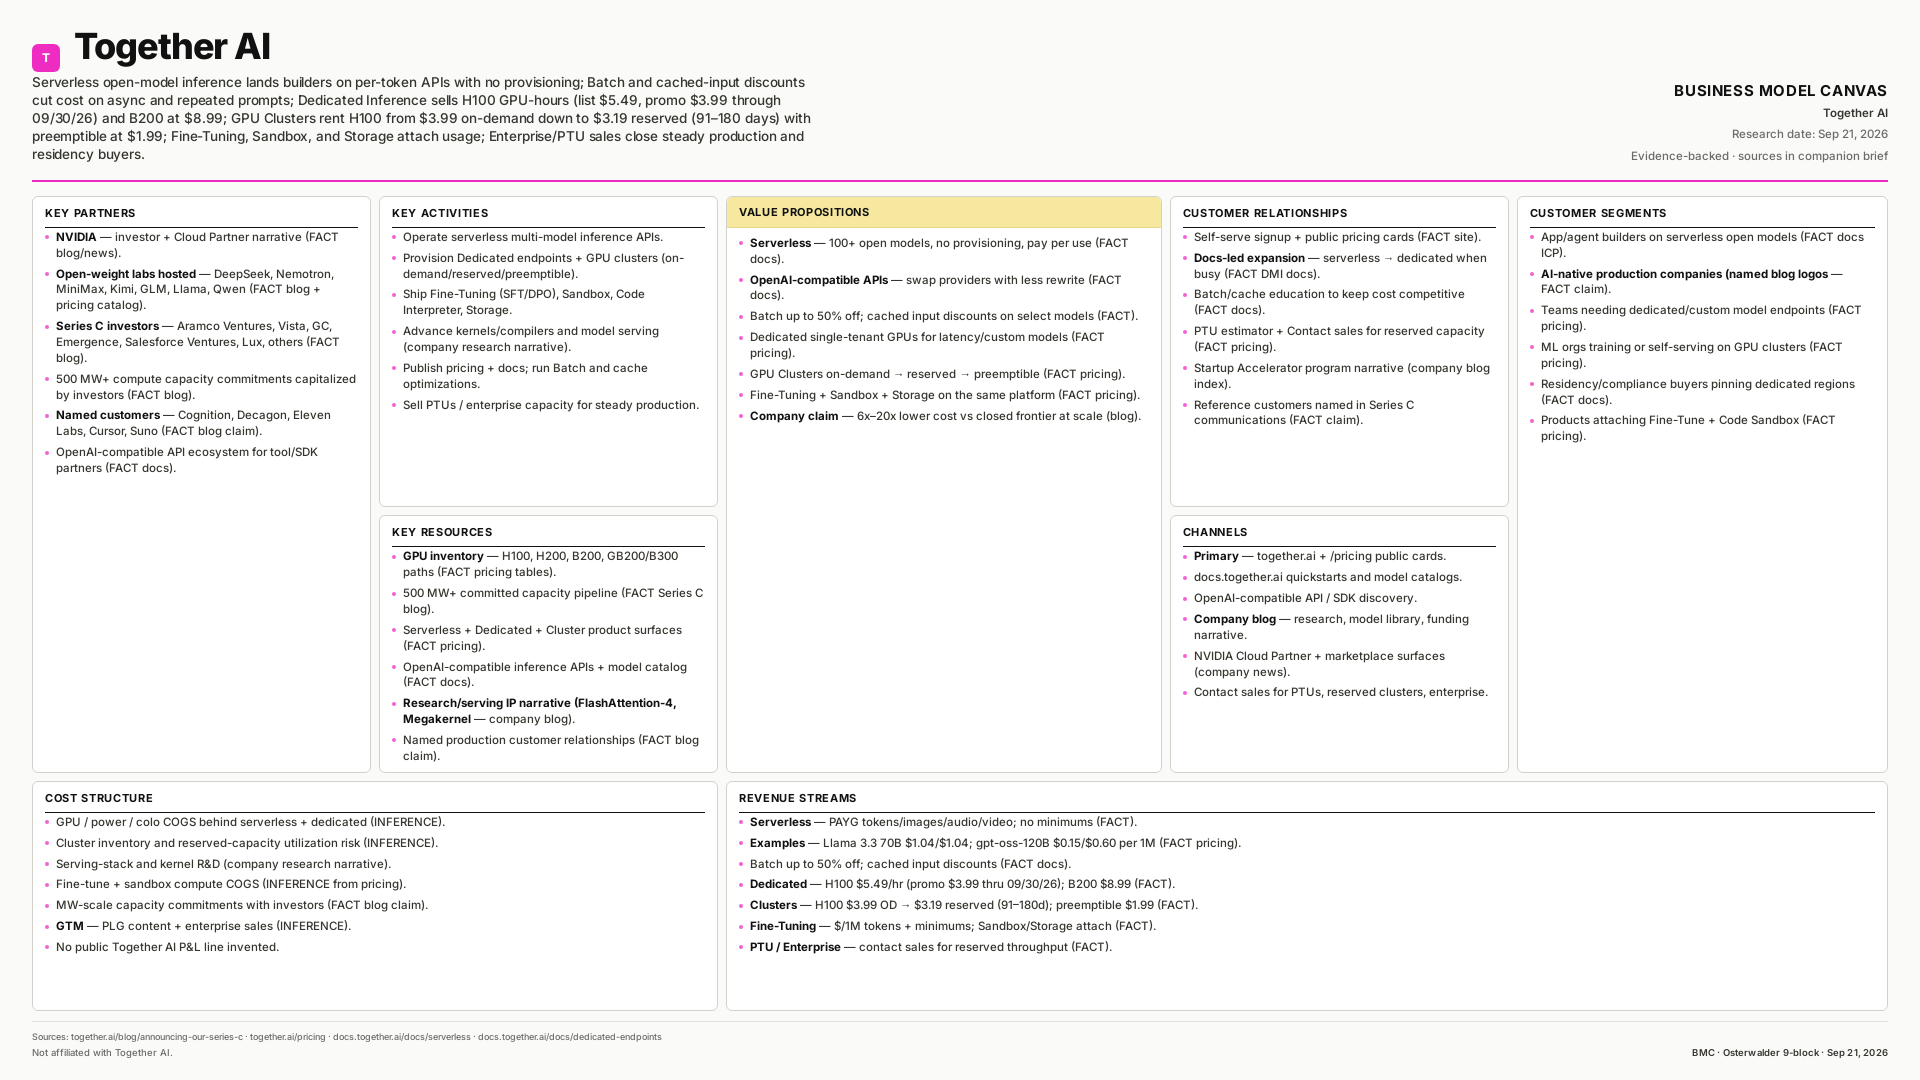
Together AI
Serverless open-model tokens land builders; Dedicated H100 GPU-hours and reserved clusters convert production traffic; Fine-tune and Sandbox attach; Enterprise/PTU closes steady capacity.
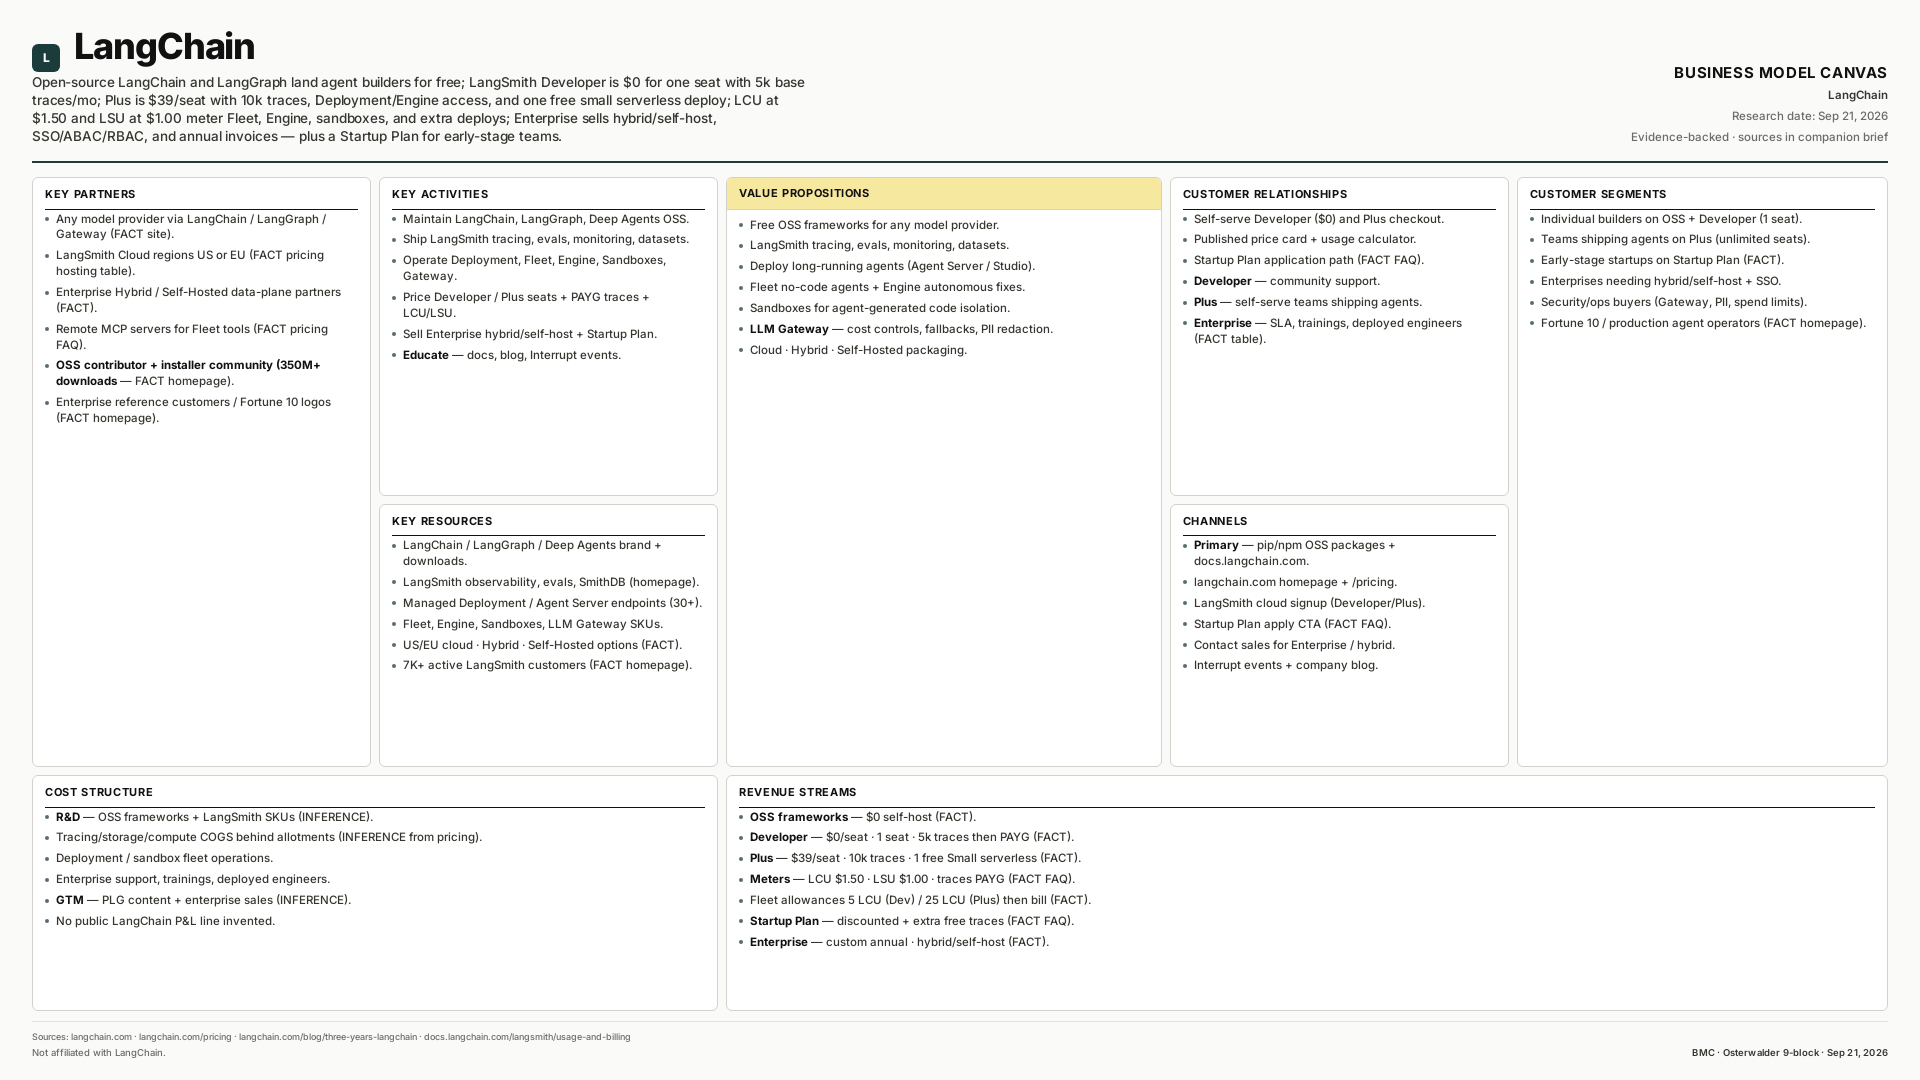
LangChain
Open-source frameworks land builders; LangSmith Developer is free for one seat; Plus at $39/seat plus LCU/LSU meters expands teams; Enterprise closes hybrid/self-host buyers.
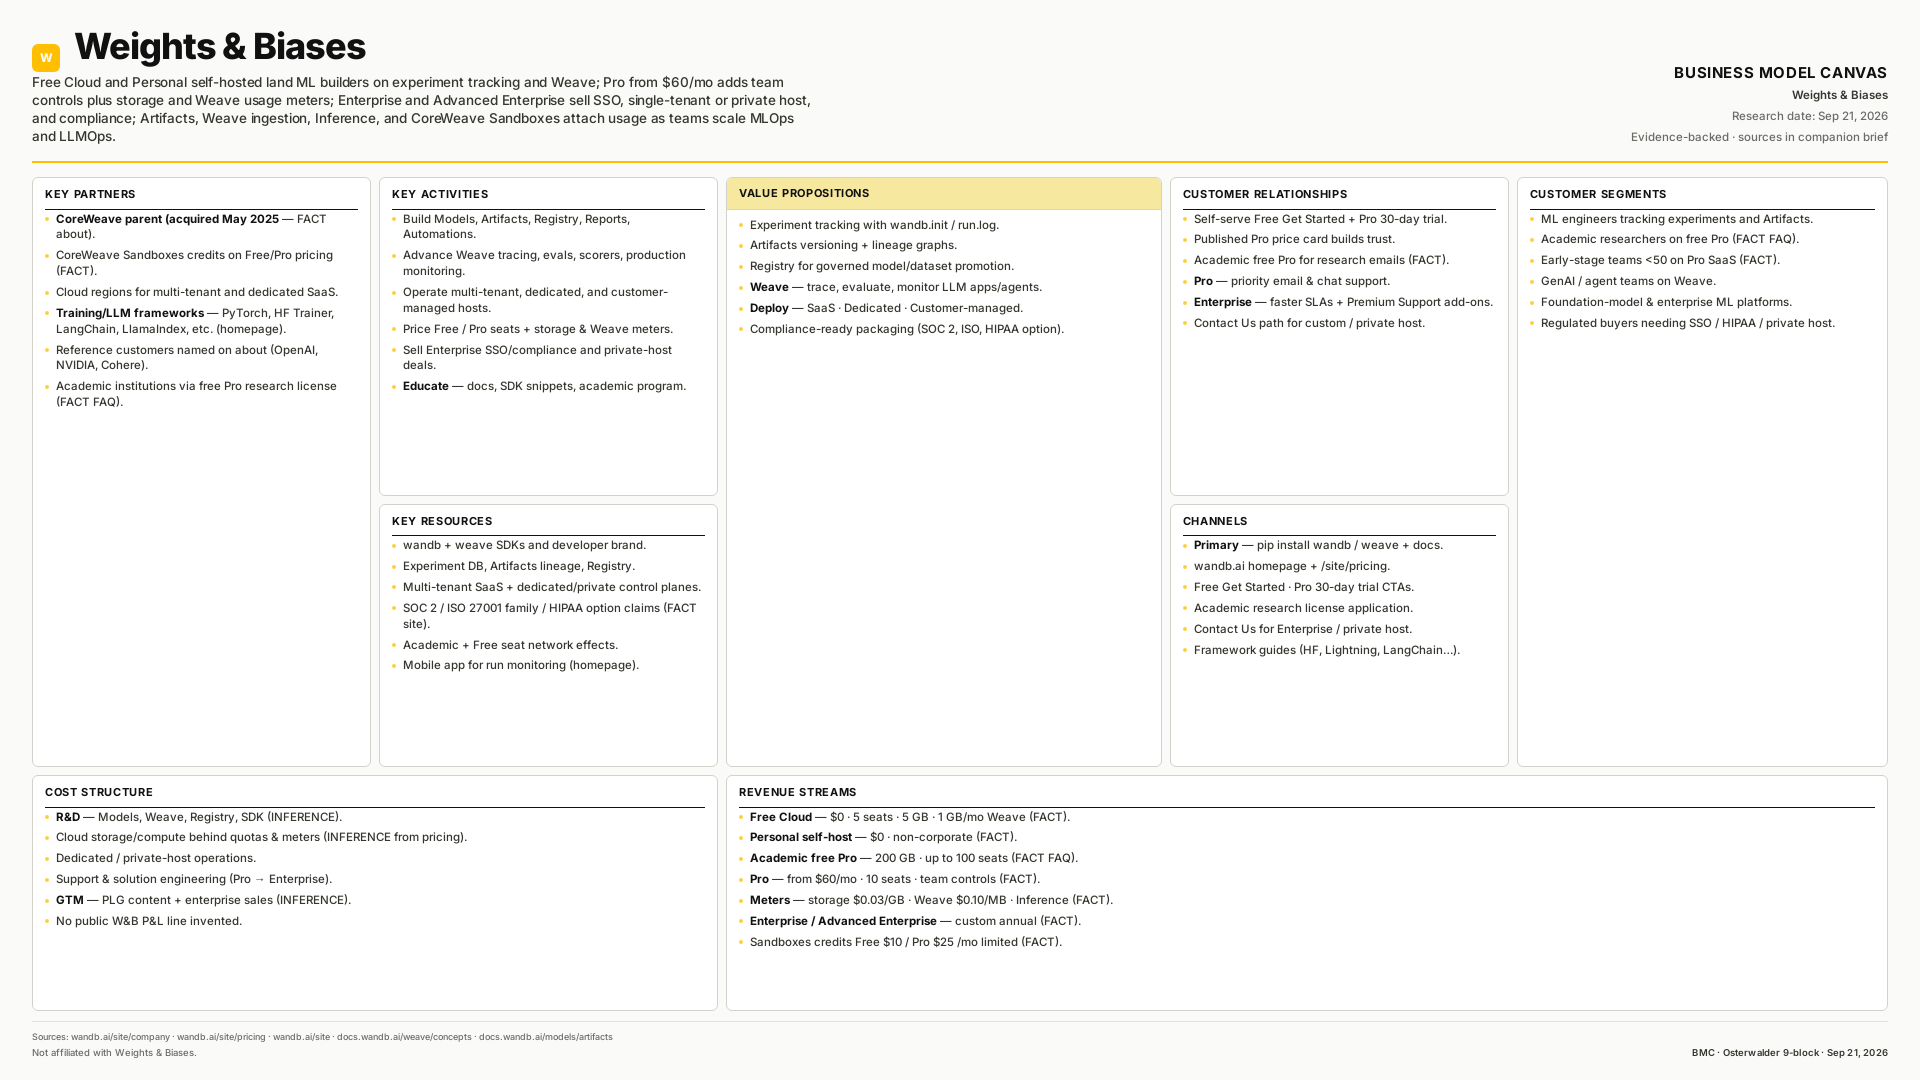
Weights & Biases
Free and Personal land builders on experiment tracking and Weave; Pro from $60/mo plus storage and Weave meters expands teams; Enterprise and private host close security buyers.

Anyscale
Open-source Ray lands builders; $100 Hosted credits and PAYG AC/hr scale managed Ray; BYOC and committed contracts take production into your VPC.

CoreWeave
Spot and on-demand GPU hours land teams on an AI-native cloud; reserved capacity and multi-year take-or-pay contracts scale labs, enterprises, and hyperscalers.
Groq
Free Console land → Developer pay-per-token LPU API → Enterprise LoRA/dedicated → GroqRack / partner capacity.
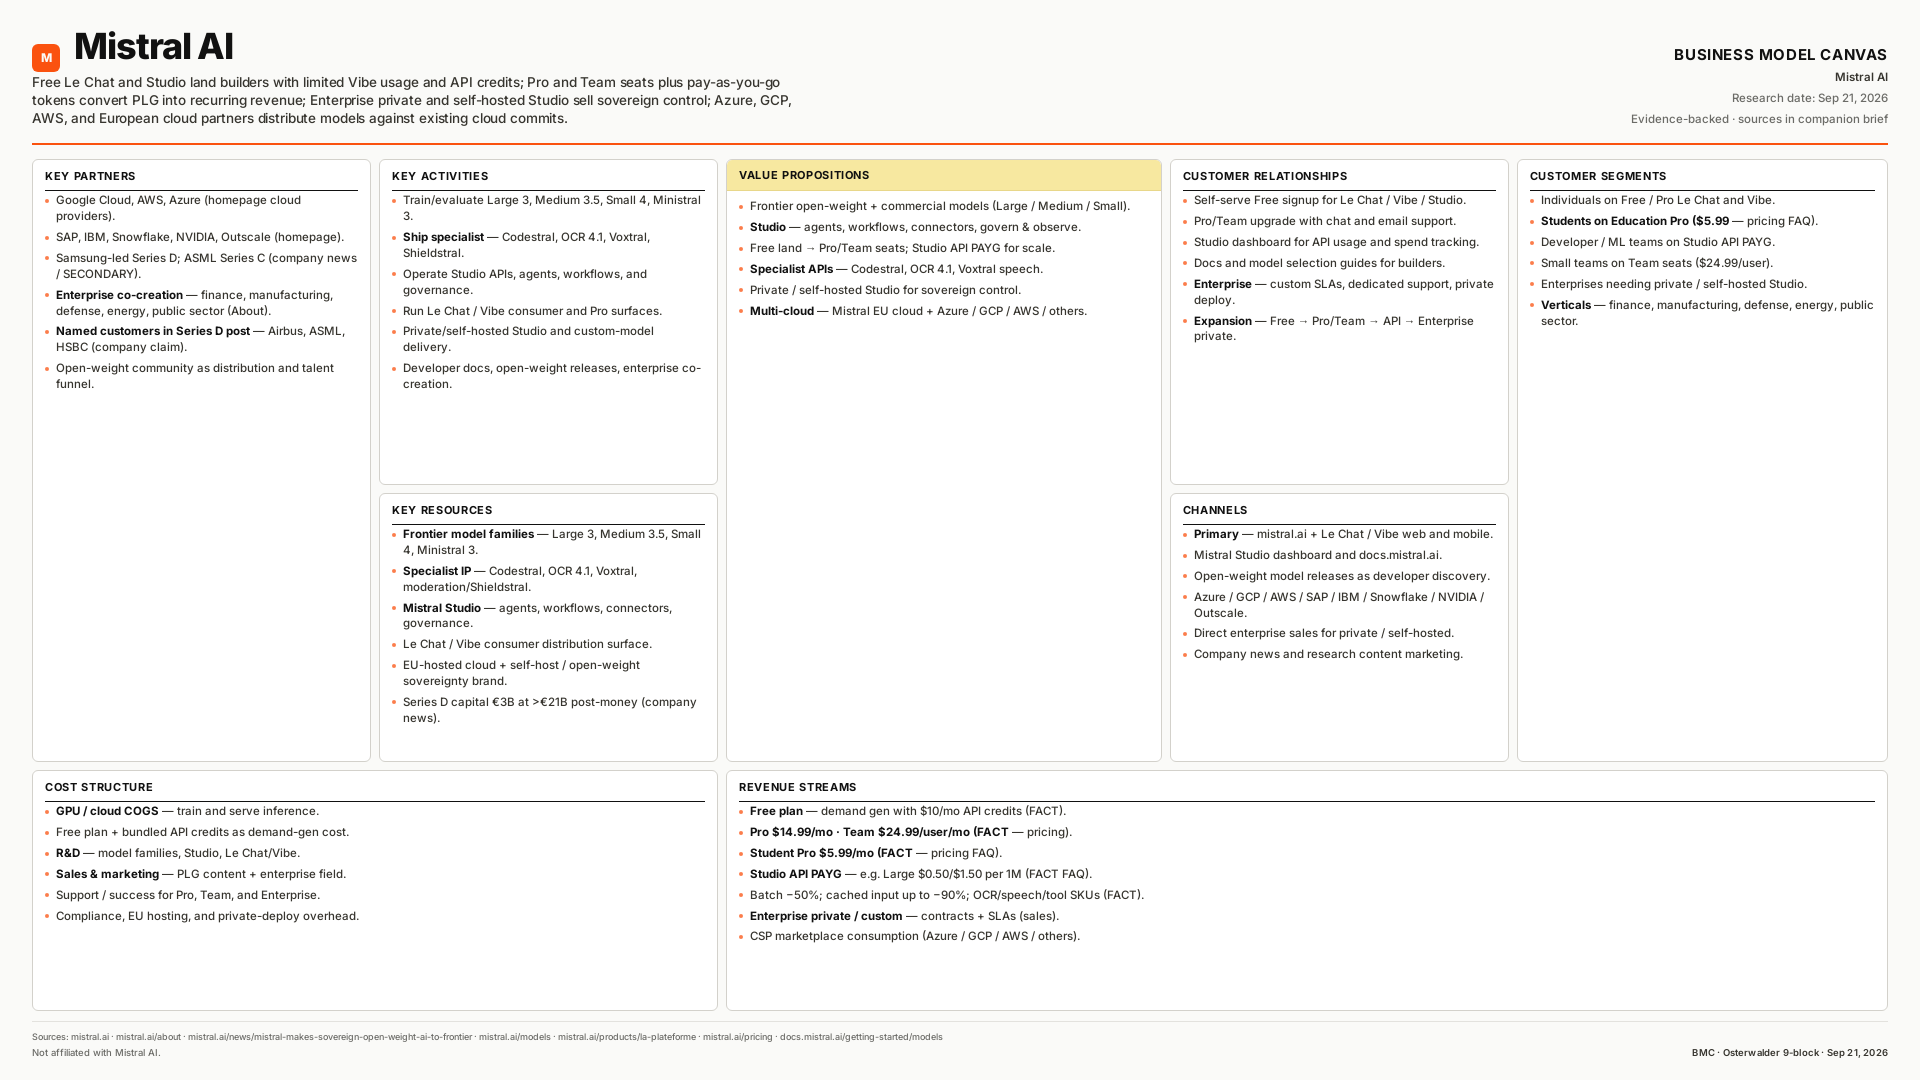

Mistral AI
Free Le Chat/Studio land → Pro/Team seats + API PAYG → Enterprise private/sovereign → hyperscaler marketplaces.
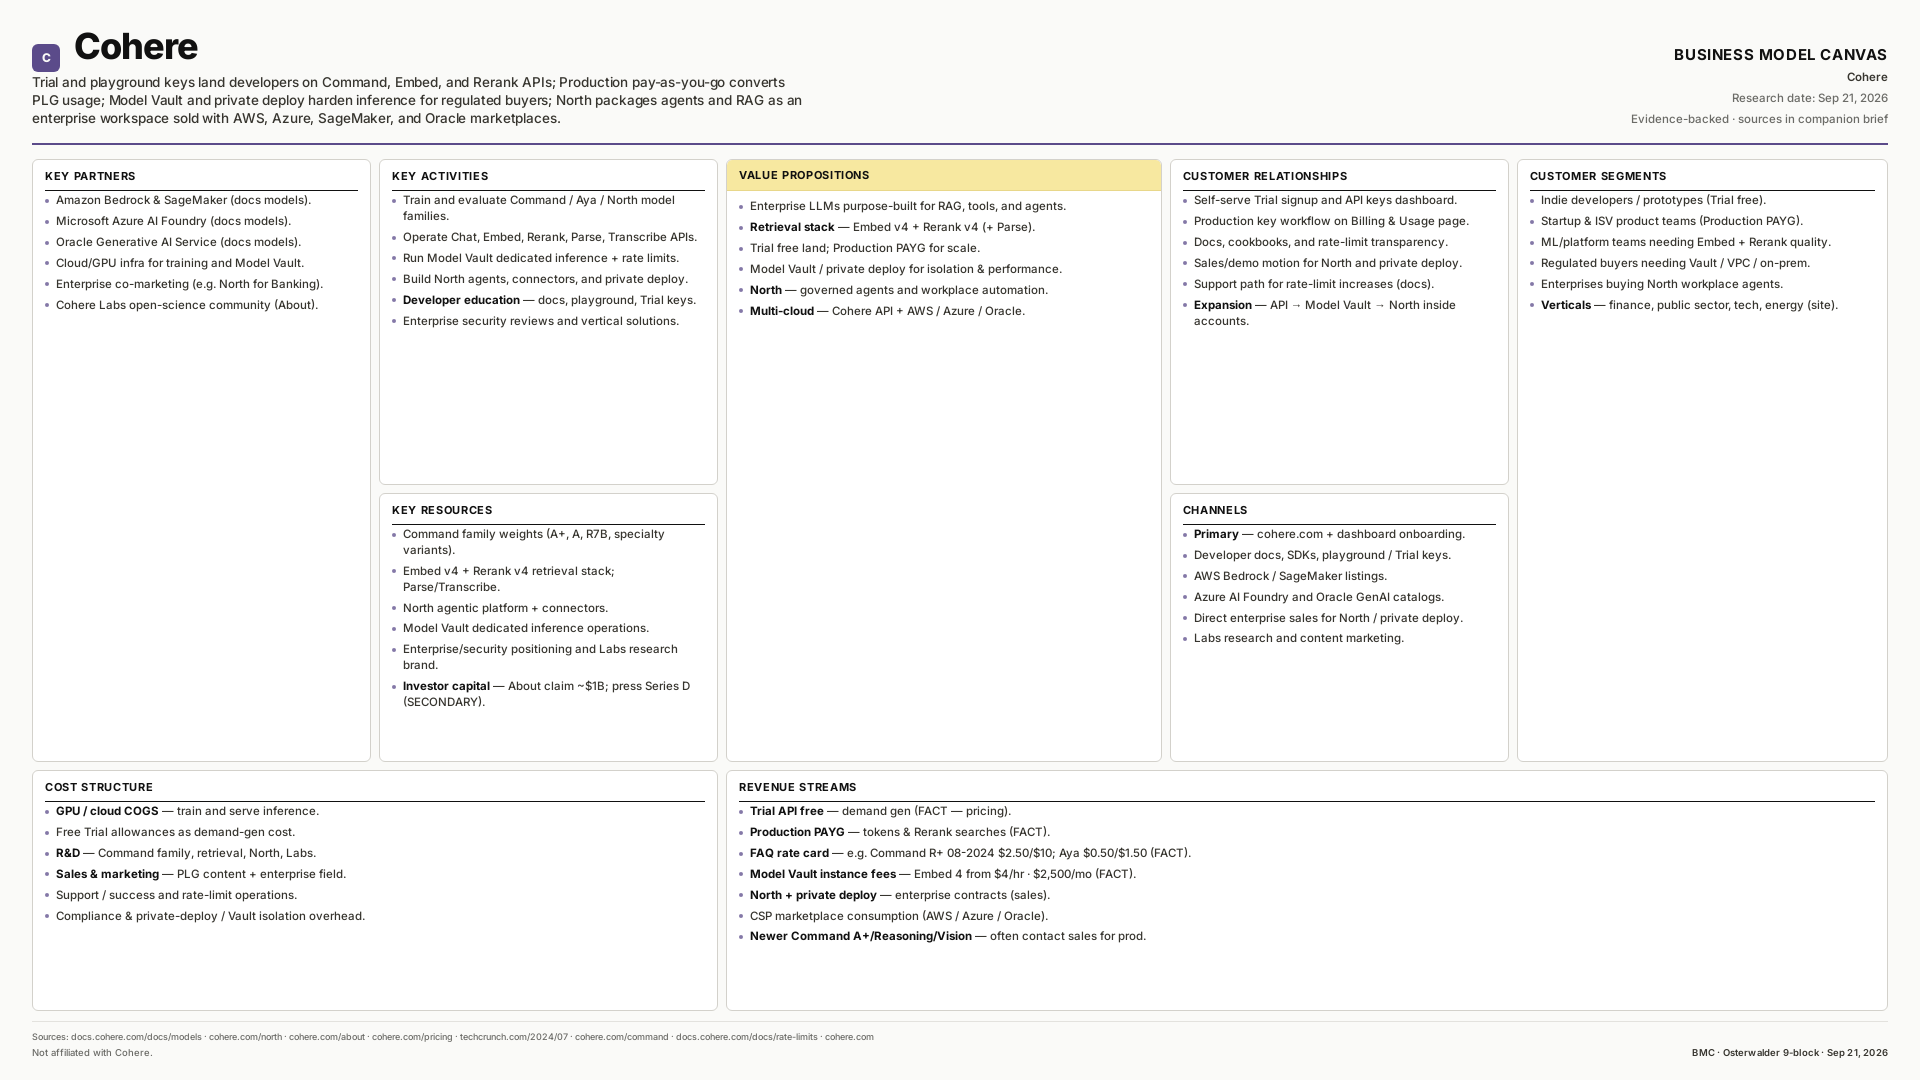
Cohere
Trial and playground keys land developers on Command, Embed, and Rerank APIs; Production pay-as-you-go converts PLG usage; Model Vault and private deploy harden inference; North packages agents and RAG with hyperscaler marketplaces.
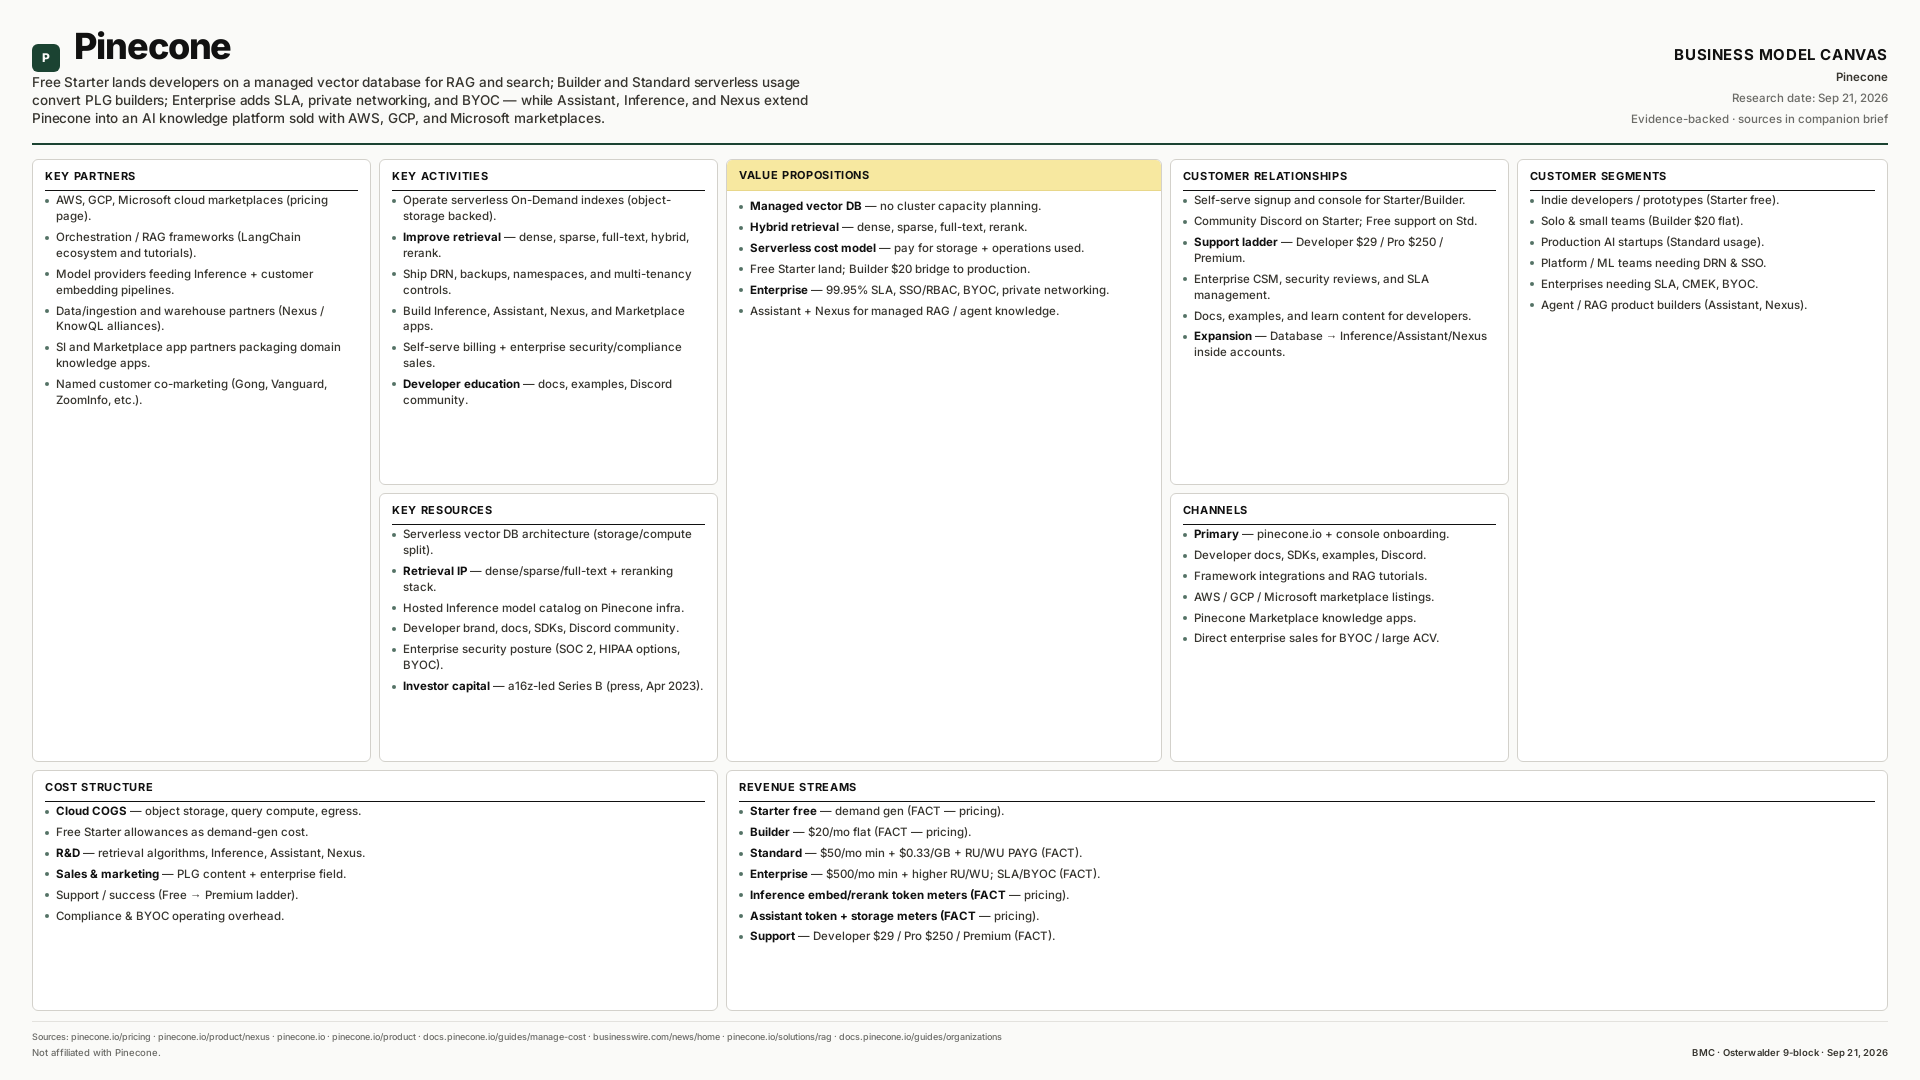
Pinecone
Free Starter lands developers on a managed vector database for RAG and search; Builder and Standard serverless usage convert PLG builders; Enterprise adds SLA, private networking, and BYOC — while Assistant, Inference, and Nexus extend into an AI knowledge platform.
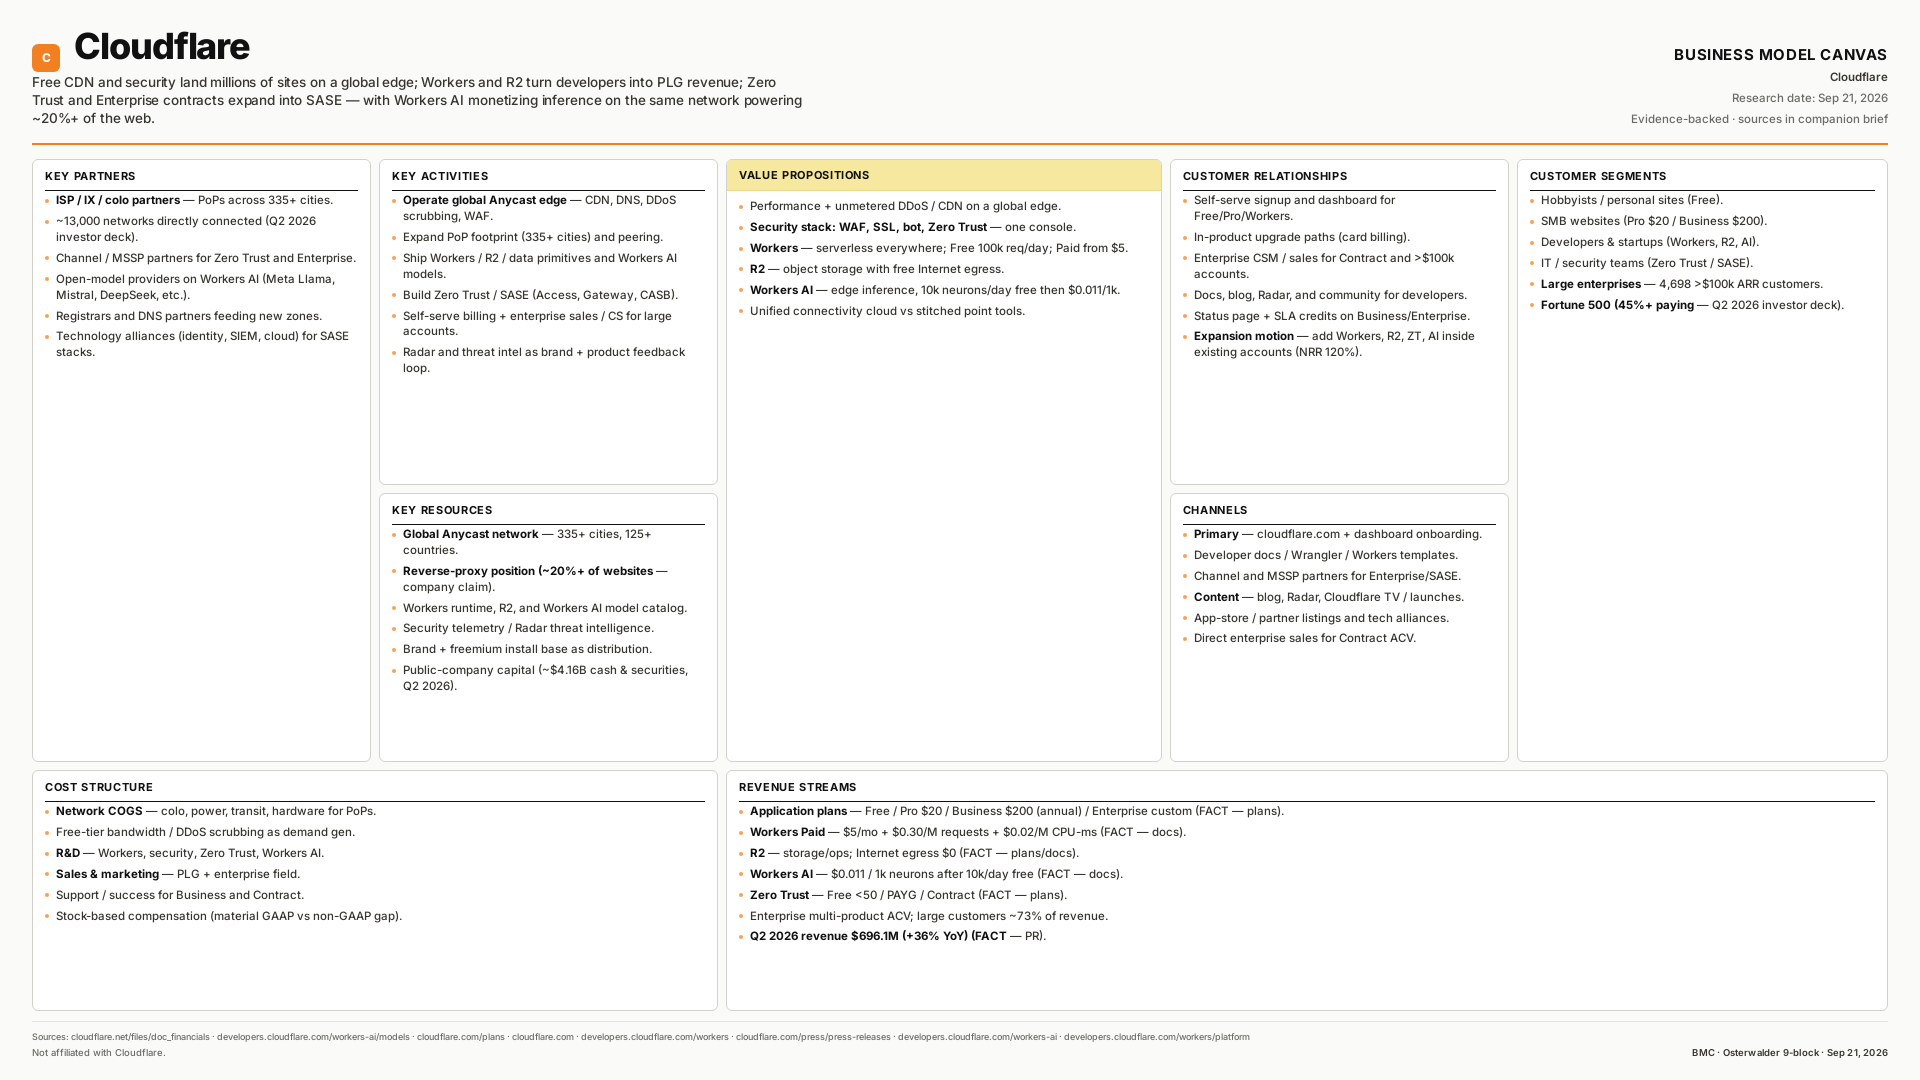

Cloudflare
Free CDN and security land millions of sites on a global edge; Workers and R2 turn developers into PLG revenue; Zero Trust and Enterprise expand into SASE — with Workers AI on the same network.
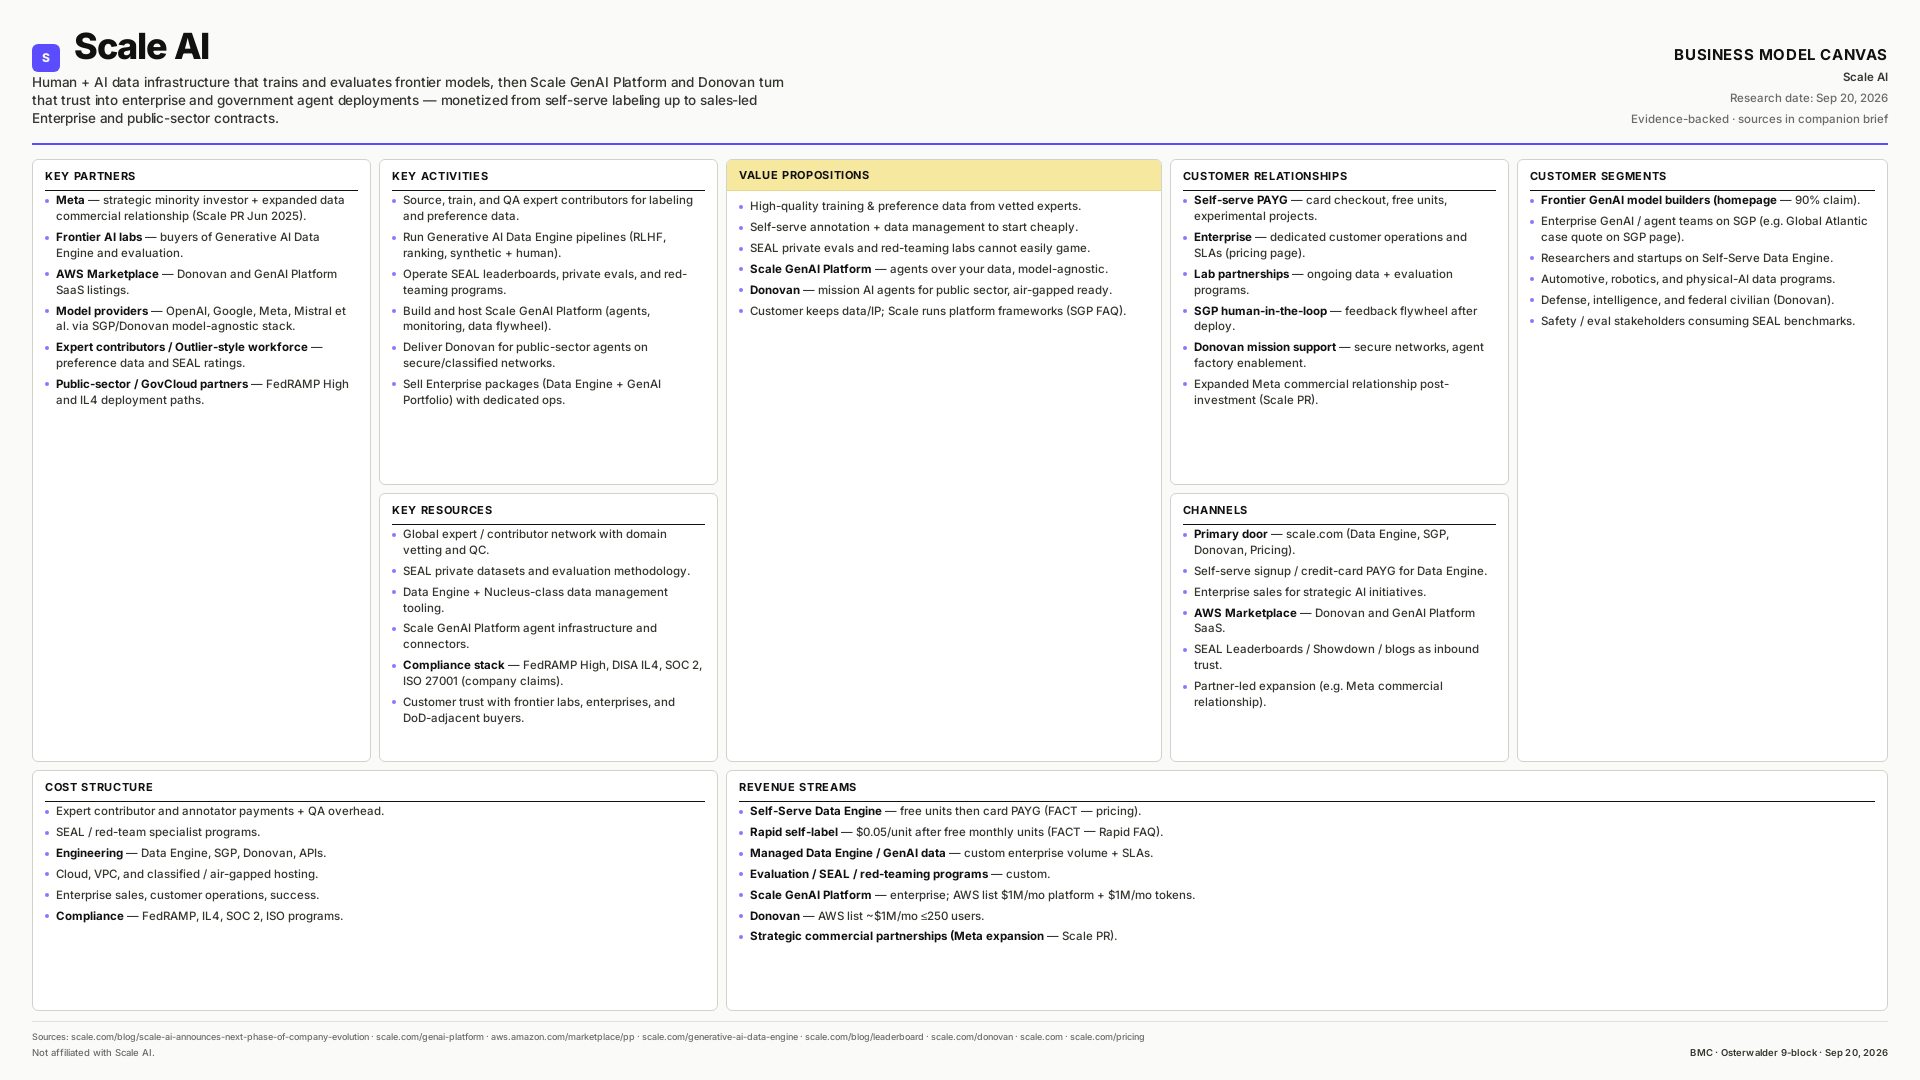

Scale AI
Human + AI data infrastructure that trains and evaluates frontier models, then Scale GenAI Platform and Donovan turn that trust into enterprise and government agent deployments.
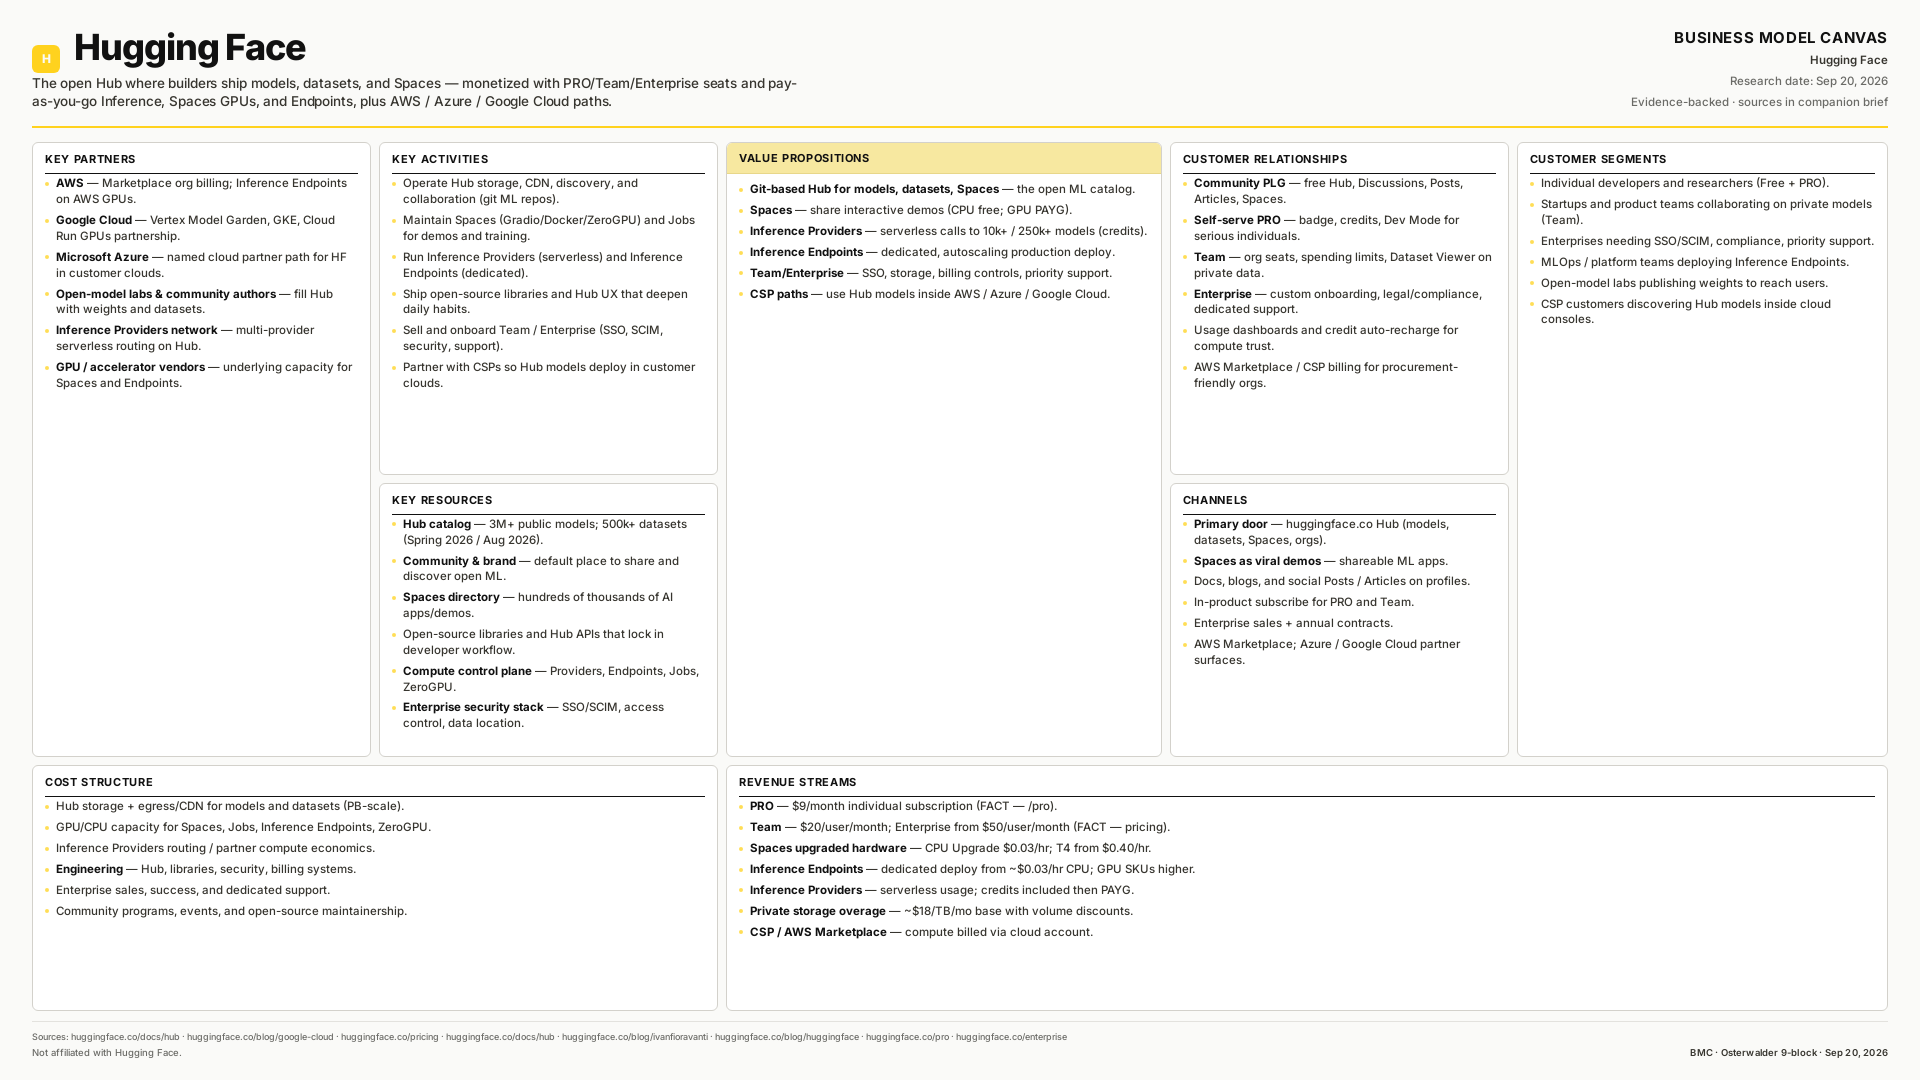

Hugging Face
The open Hub where builders ship models, datasets, and Spaces — monetized with PRO/Team/Enterprise seats and pay-as-you-go Inference, Spaces GPUs, and Endpoints, plus AWS / Azure / Google Cloud paths.
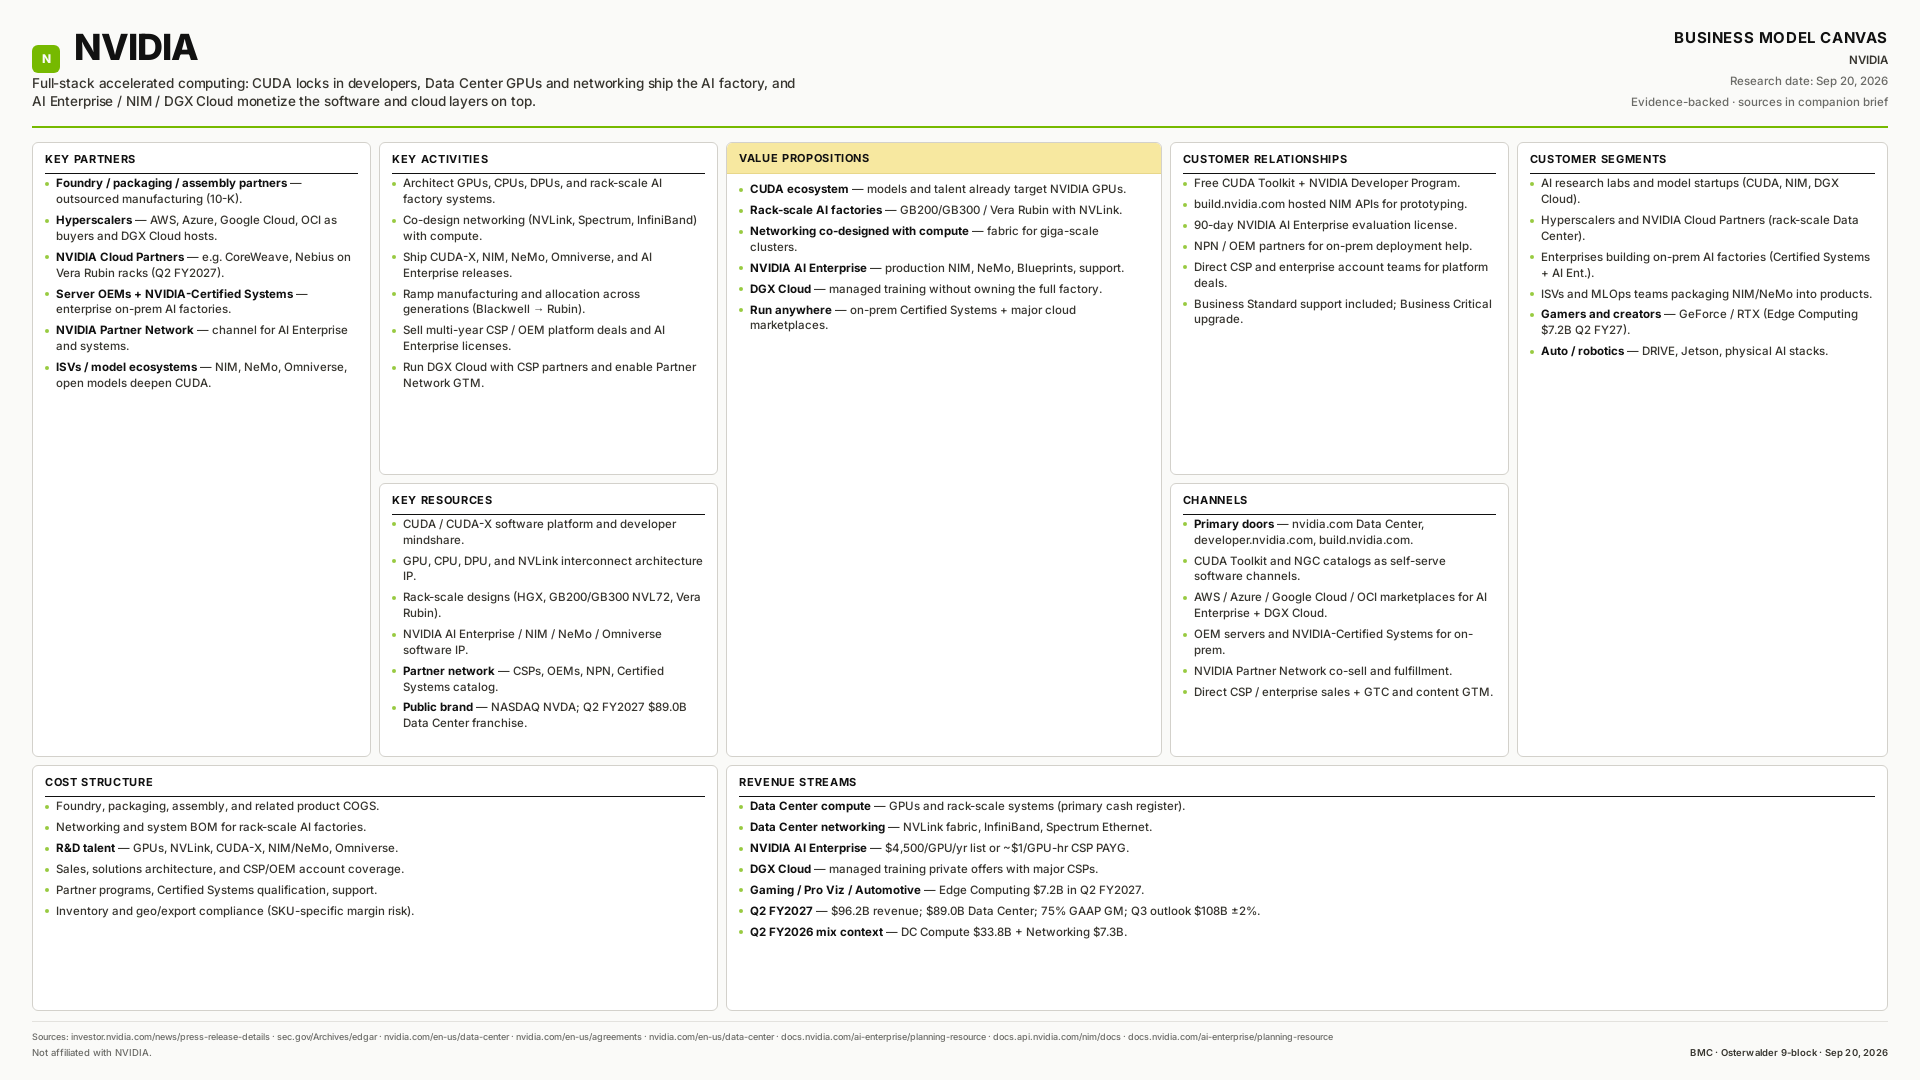

NVIDIA
Full-stack accelerated computing: CUDA locks in developers, Data Center GPUs and networking ship the AI factory, and AI Enterprise / NIM / DGX Cloud monetize the software and cloud layers on top.
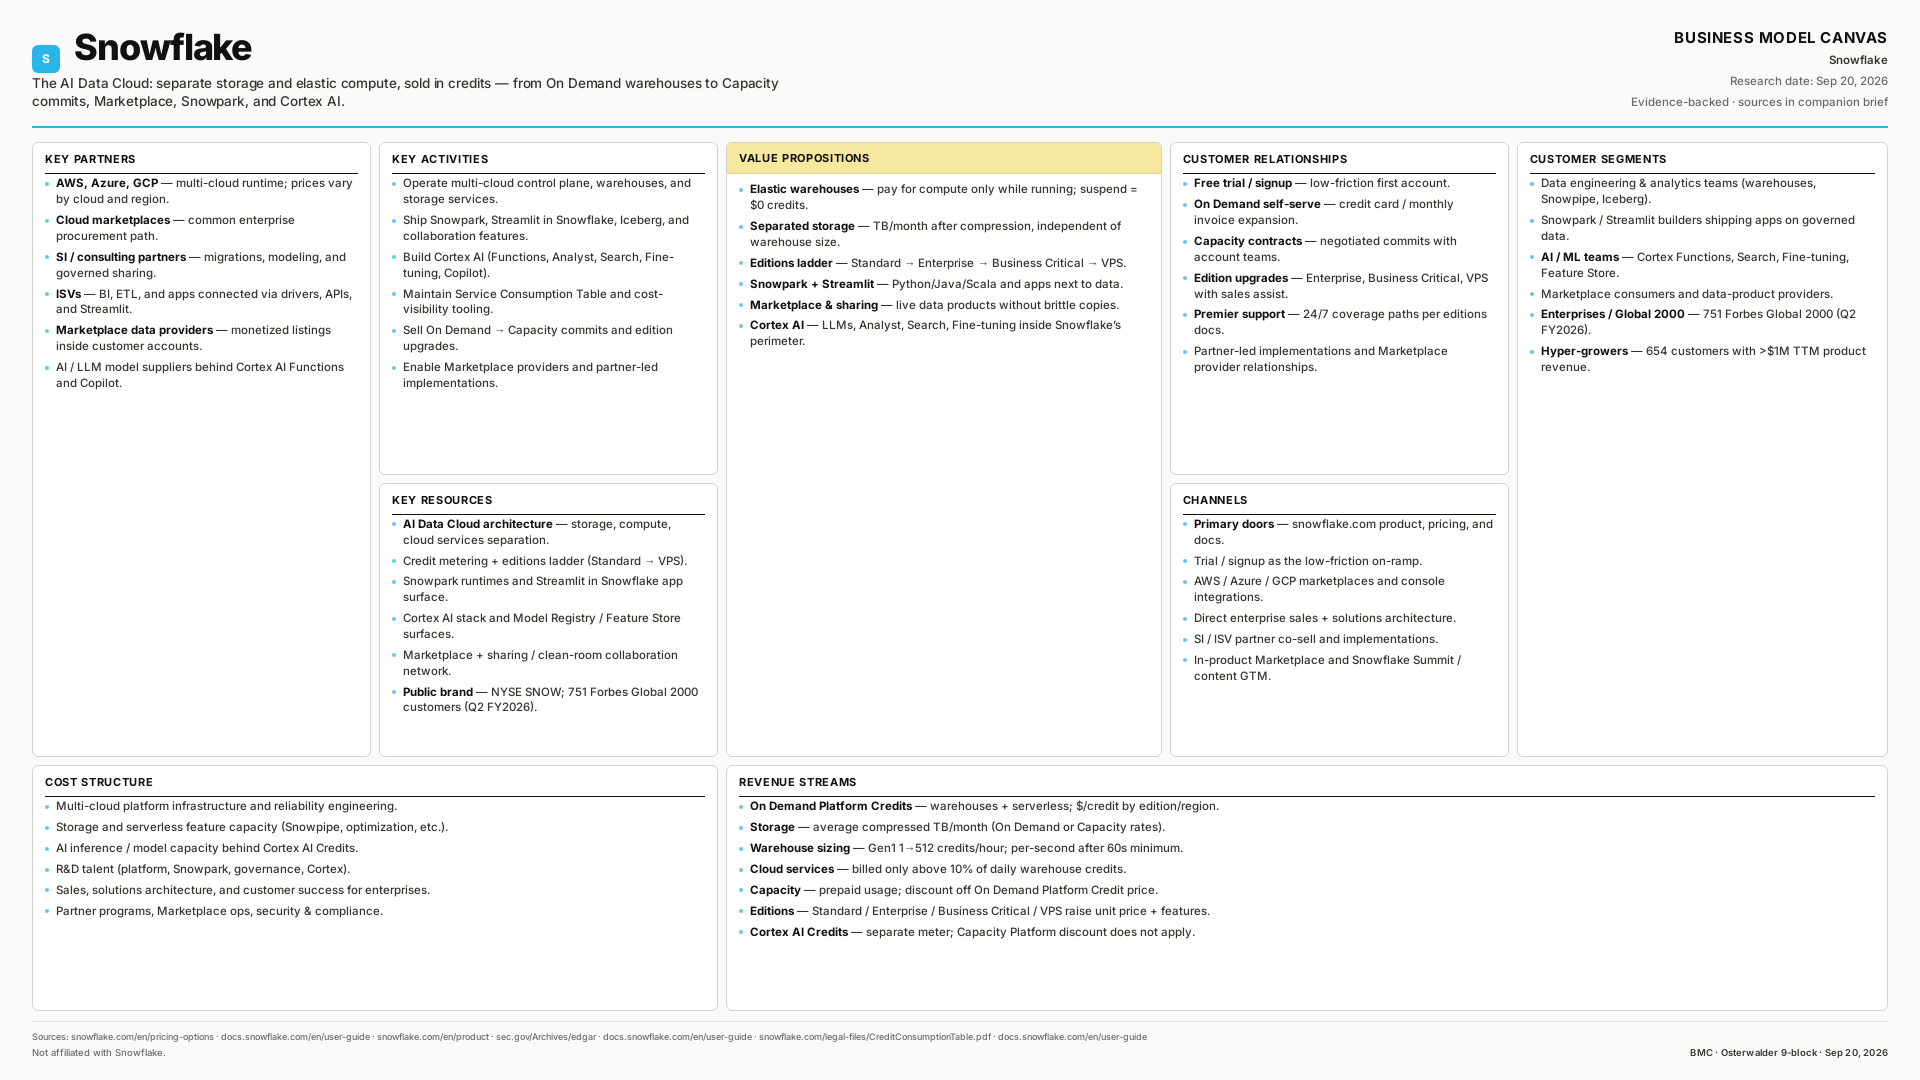
Snowflake
The AI Data Cloud: separate storage and elastic compute, sold in credits — from On Demand warehouses to Capacity commits, Marketplace, Snowpark, and Cortex AI.
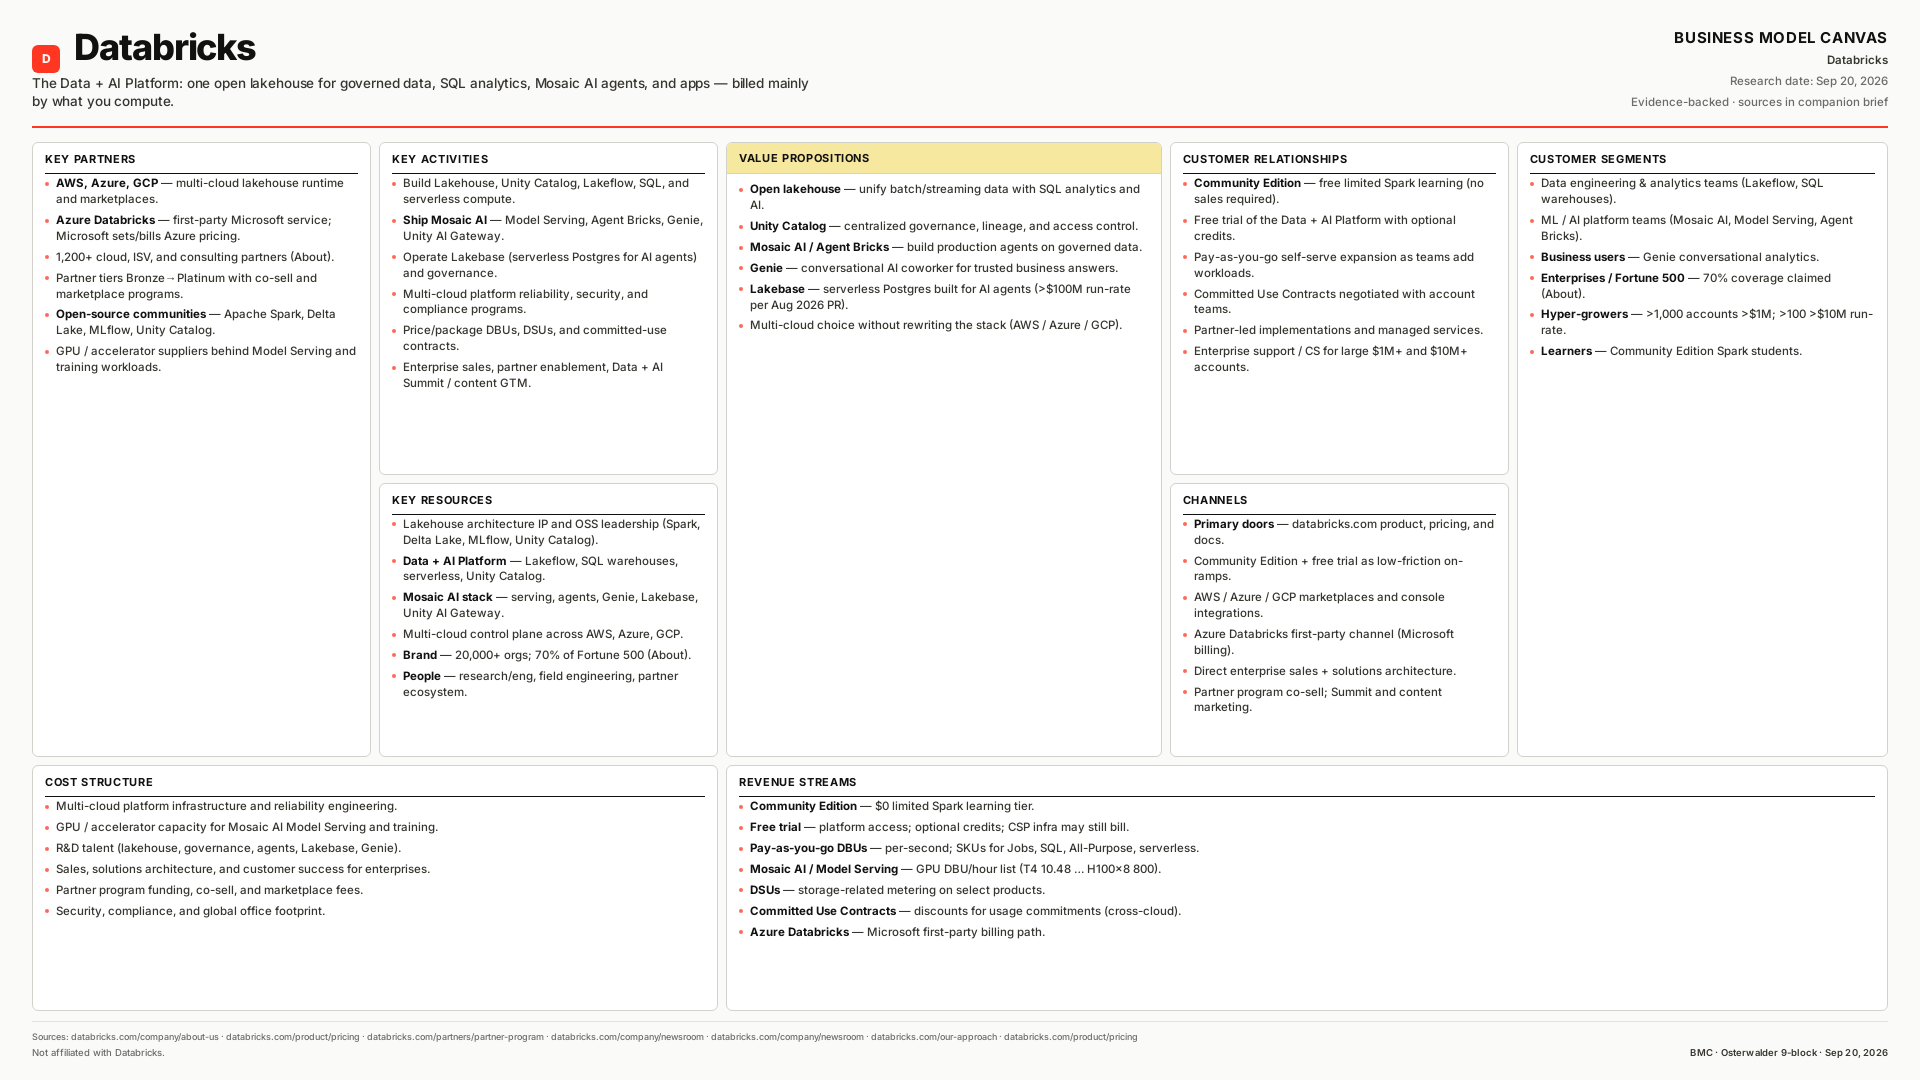

Databricks
The Data + AI Platform: one open lakehouse for governed data, SQL analytics, Mosaic AI agents, and apps — billed mainly by what you compute.
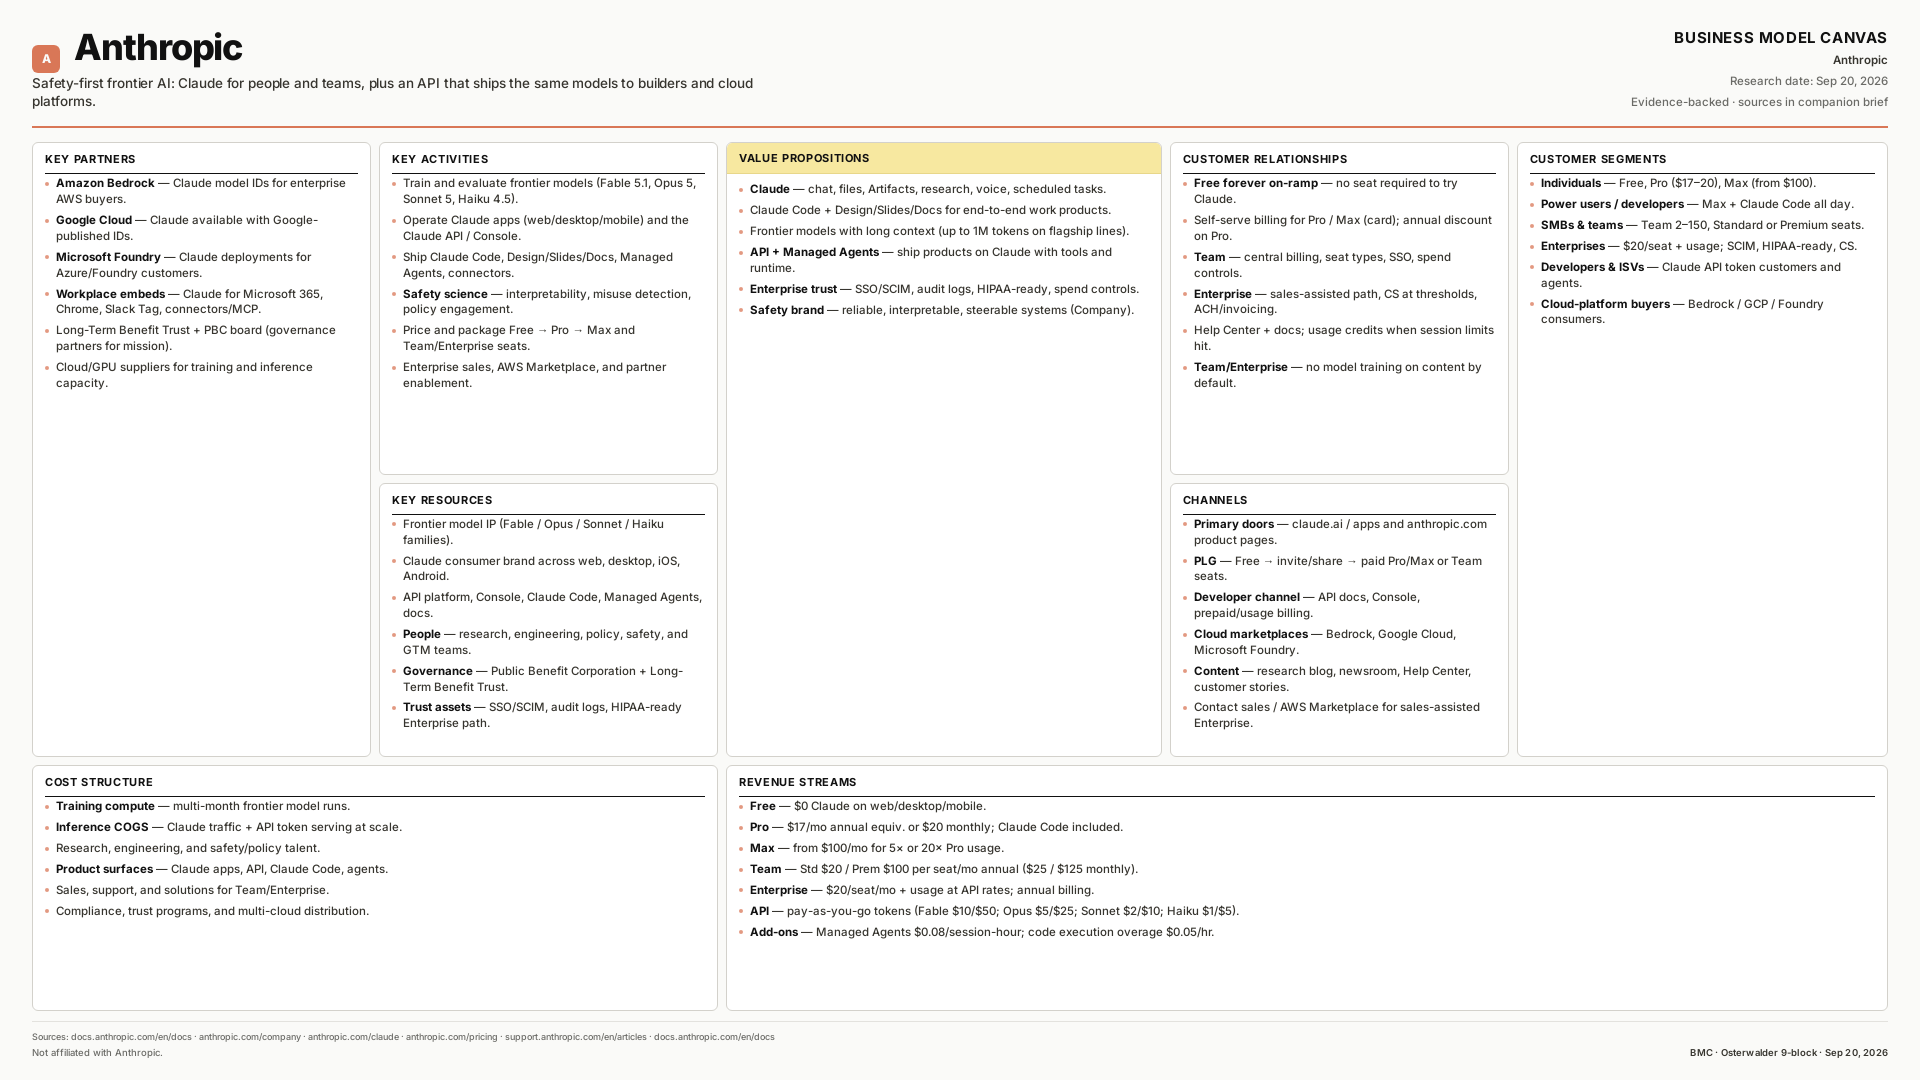

Anthropic
Safety-first frontier AI: Claude for people and teams, plus an API that ships the same models to builders and cloud platforms.
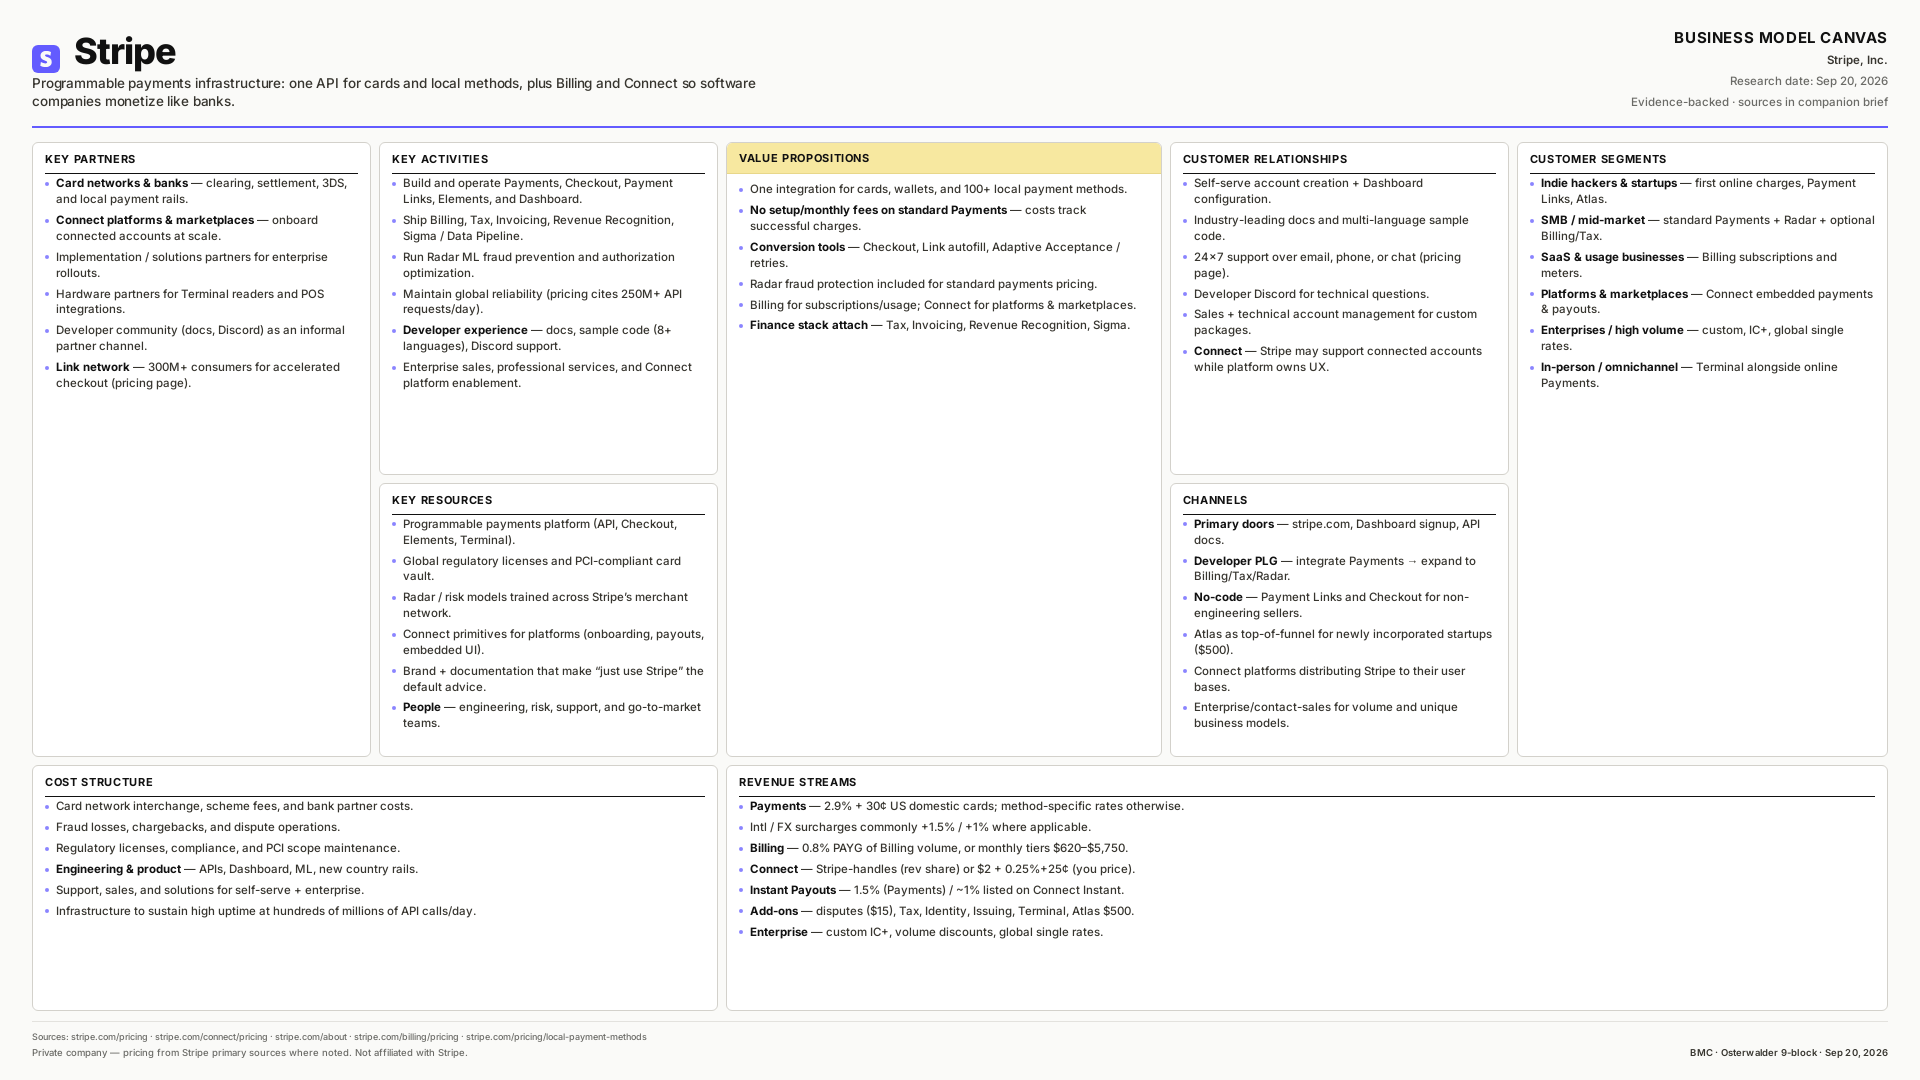

Stripe
Programmable payments infrastructure: one API for cards and local methods, plus Billing and Connect so software companies monetize like banks.
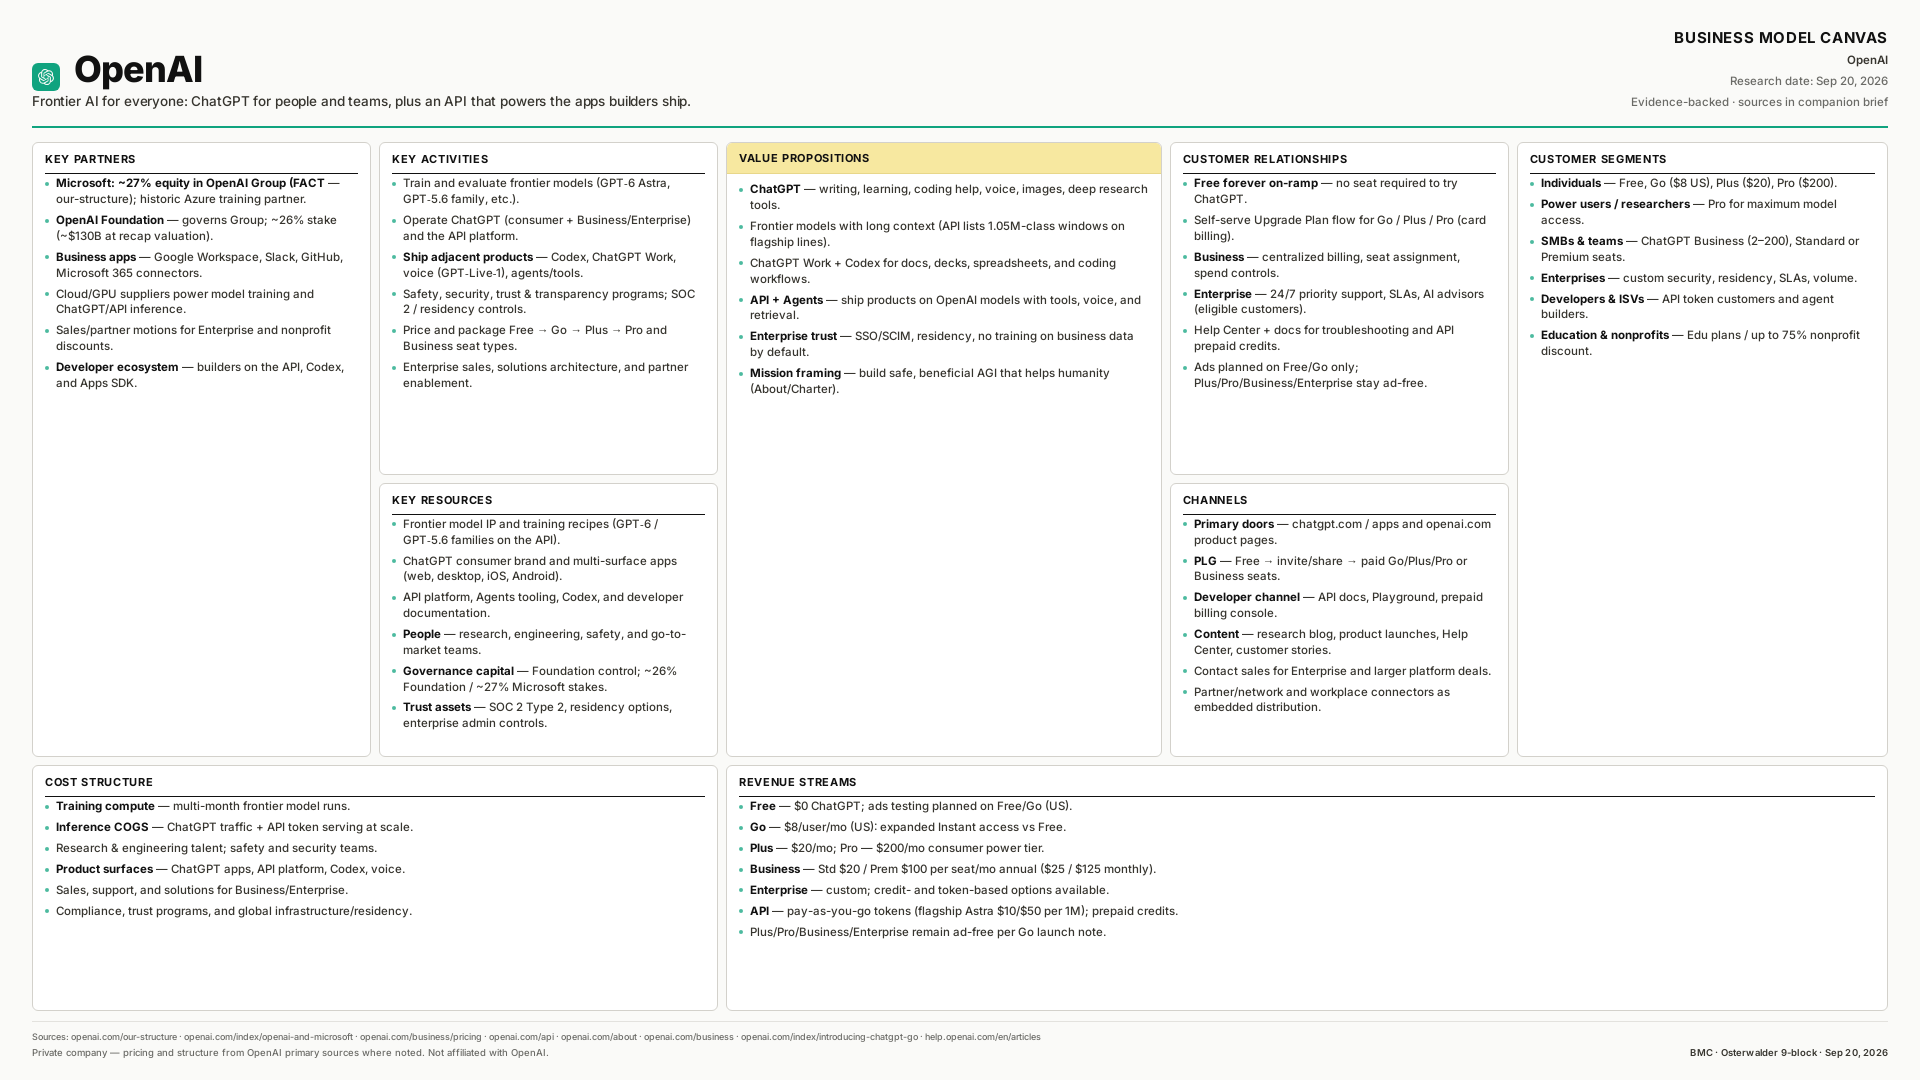

OpenAI
Frontier AI for everyone: ChatGPT for people and teams, plus an API that powers the apps builders ship.
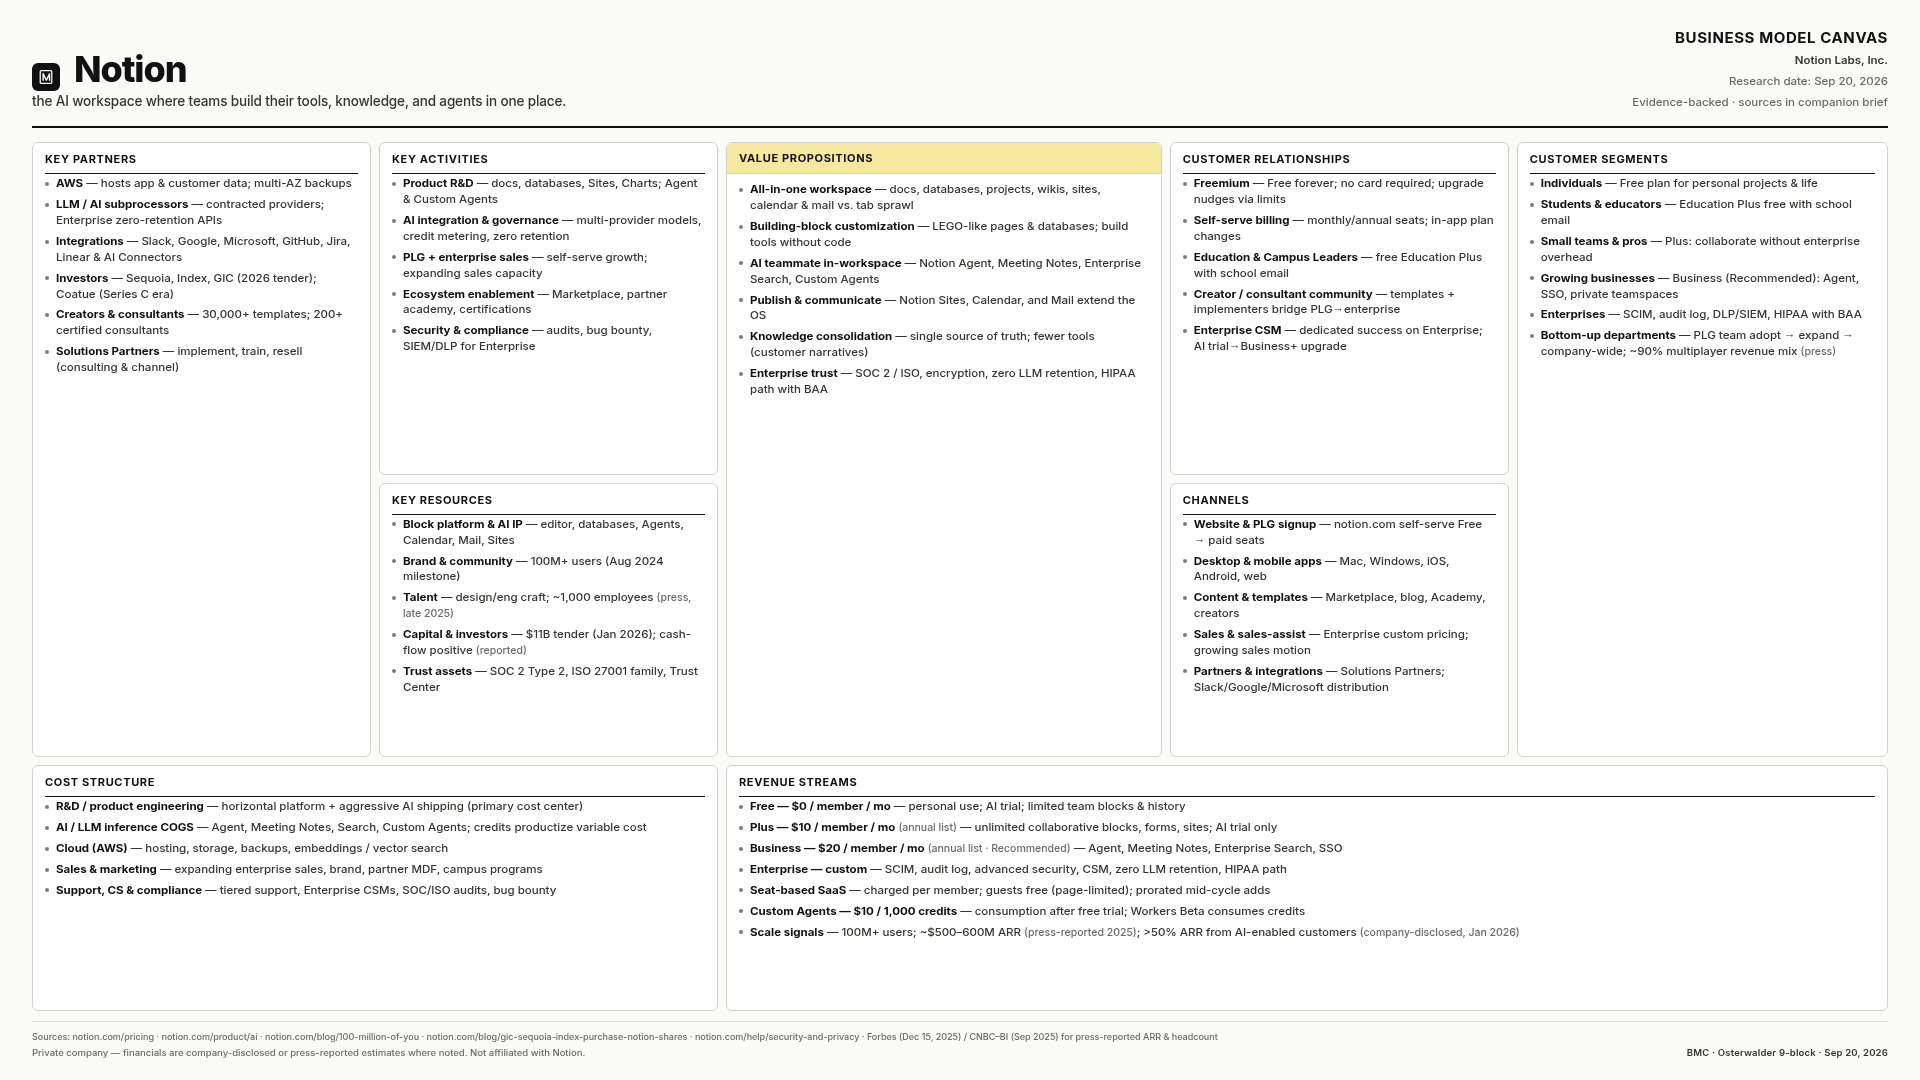

Notion Labs
The AI workspace where teams build tools, knowledge, and agents in one place.